

You are here
News Feeds
Sharks Can Hear Sounds Nearly 250 Feet Away and Find the Source
Sound travels through the ocean carrying clues about potential prey, predators and other animals, giving sharks an important way to detect what they cannot yet see.
Portada
Main page
assembly:2026:indonesia:difusion_cover_bangungreport.jpg - created
es:assembly:2026:indonesia:difusion_cover_bandung_esp.jpg - creado
Serie de entrevistas realizadas durante la Asamblea del TGA 2026 en Bandung, Indonesia
es:assembly:2026:indonesia:esp_poster_voices.jpg - creado
Series of interviews conducted during the 2026 GTA Assembly in Bandung, Indonesia
assembly:2026:indonesia:poster_voices.jpg - created
Hidden Heroes 2026: Champions Empowering Communities for Action
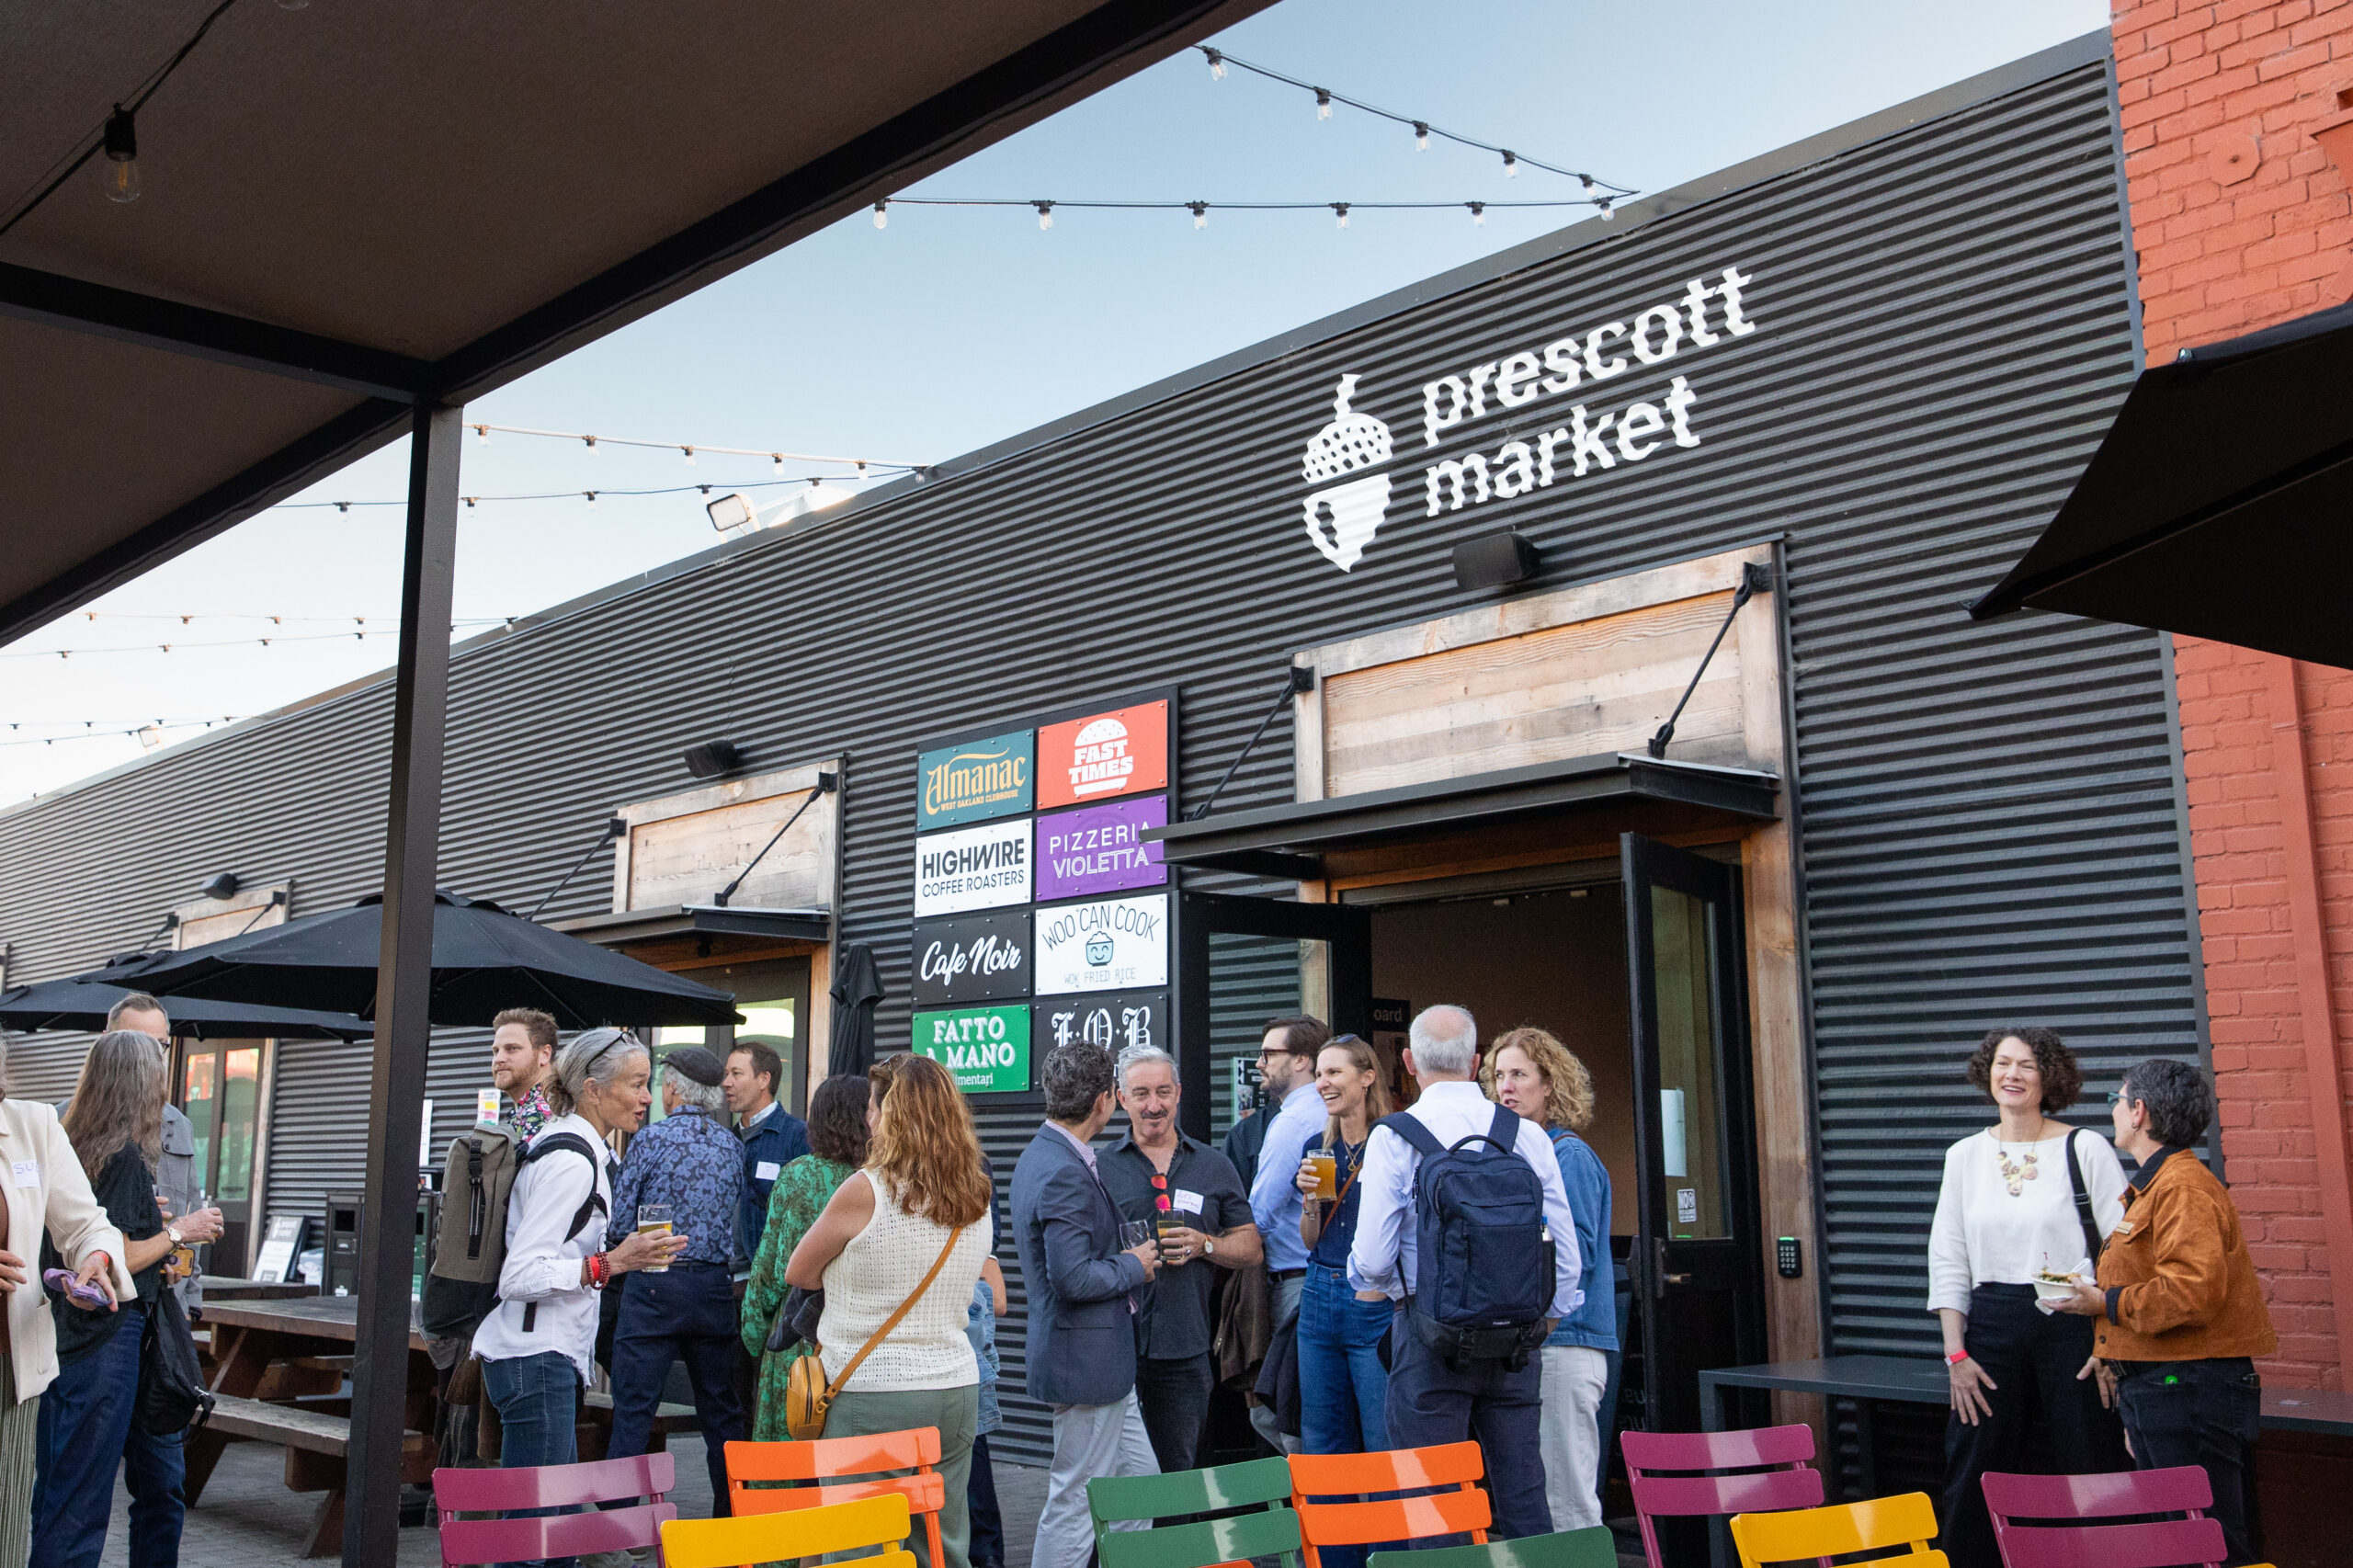
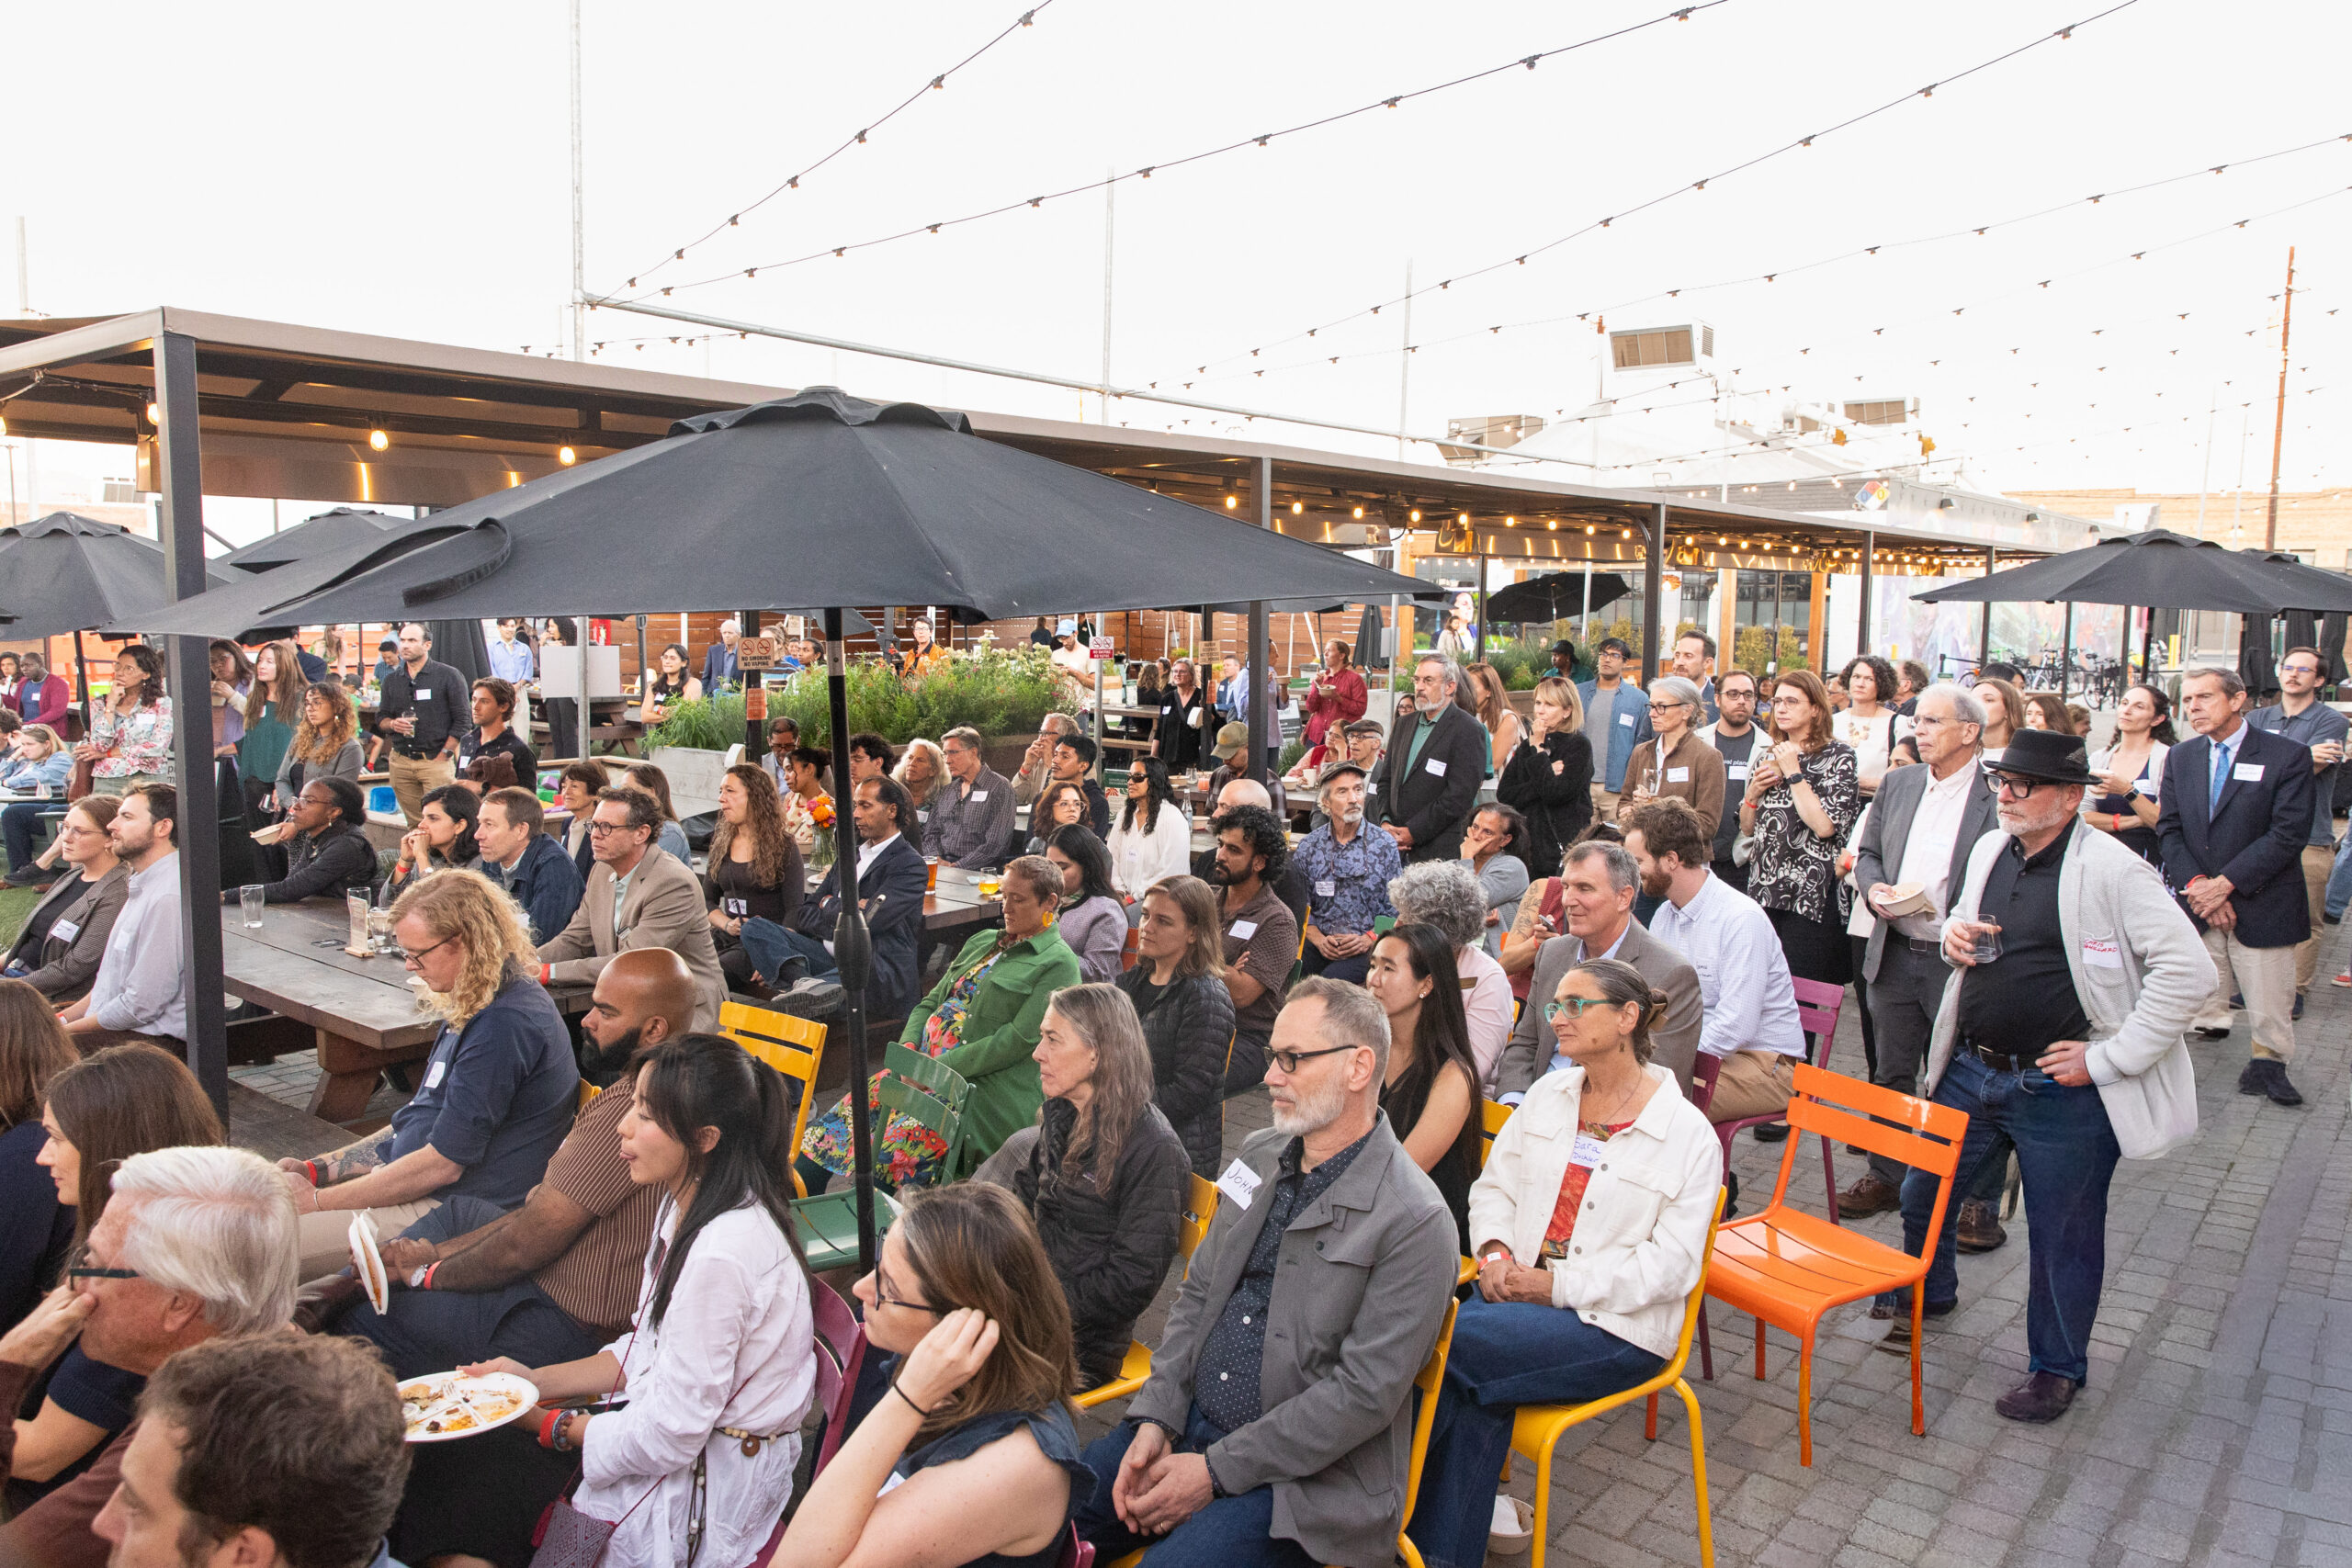
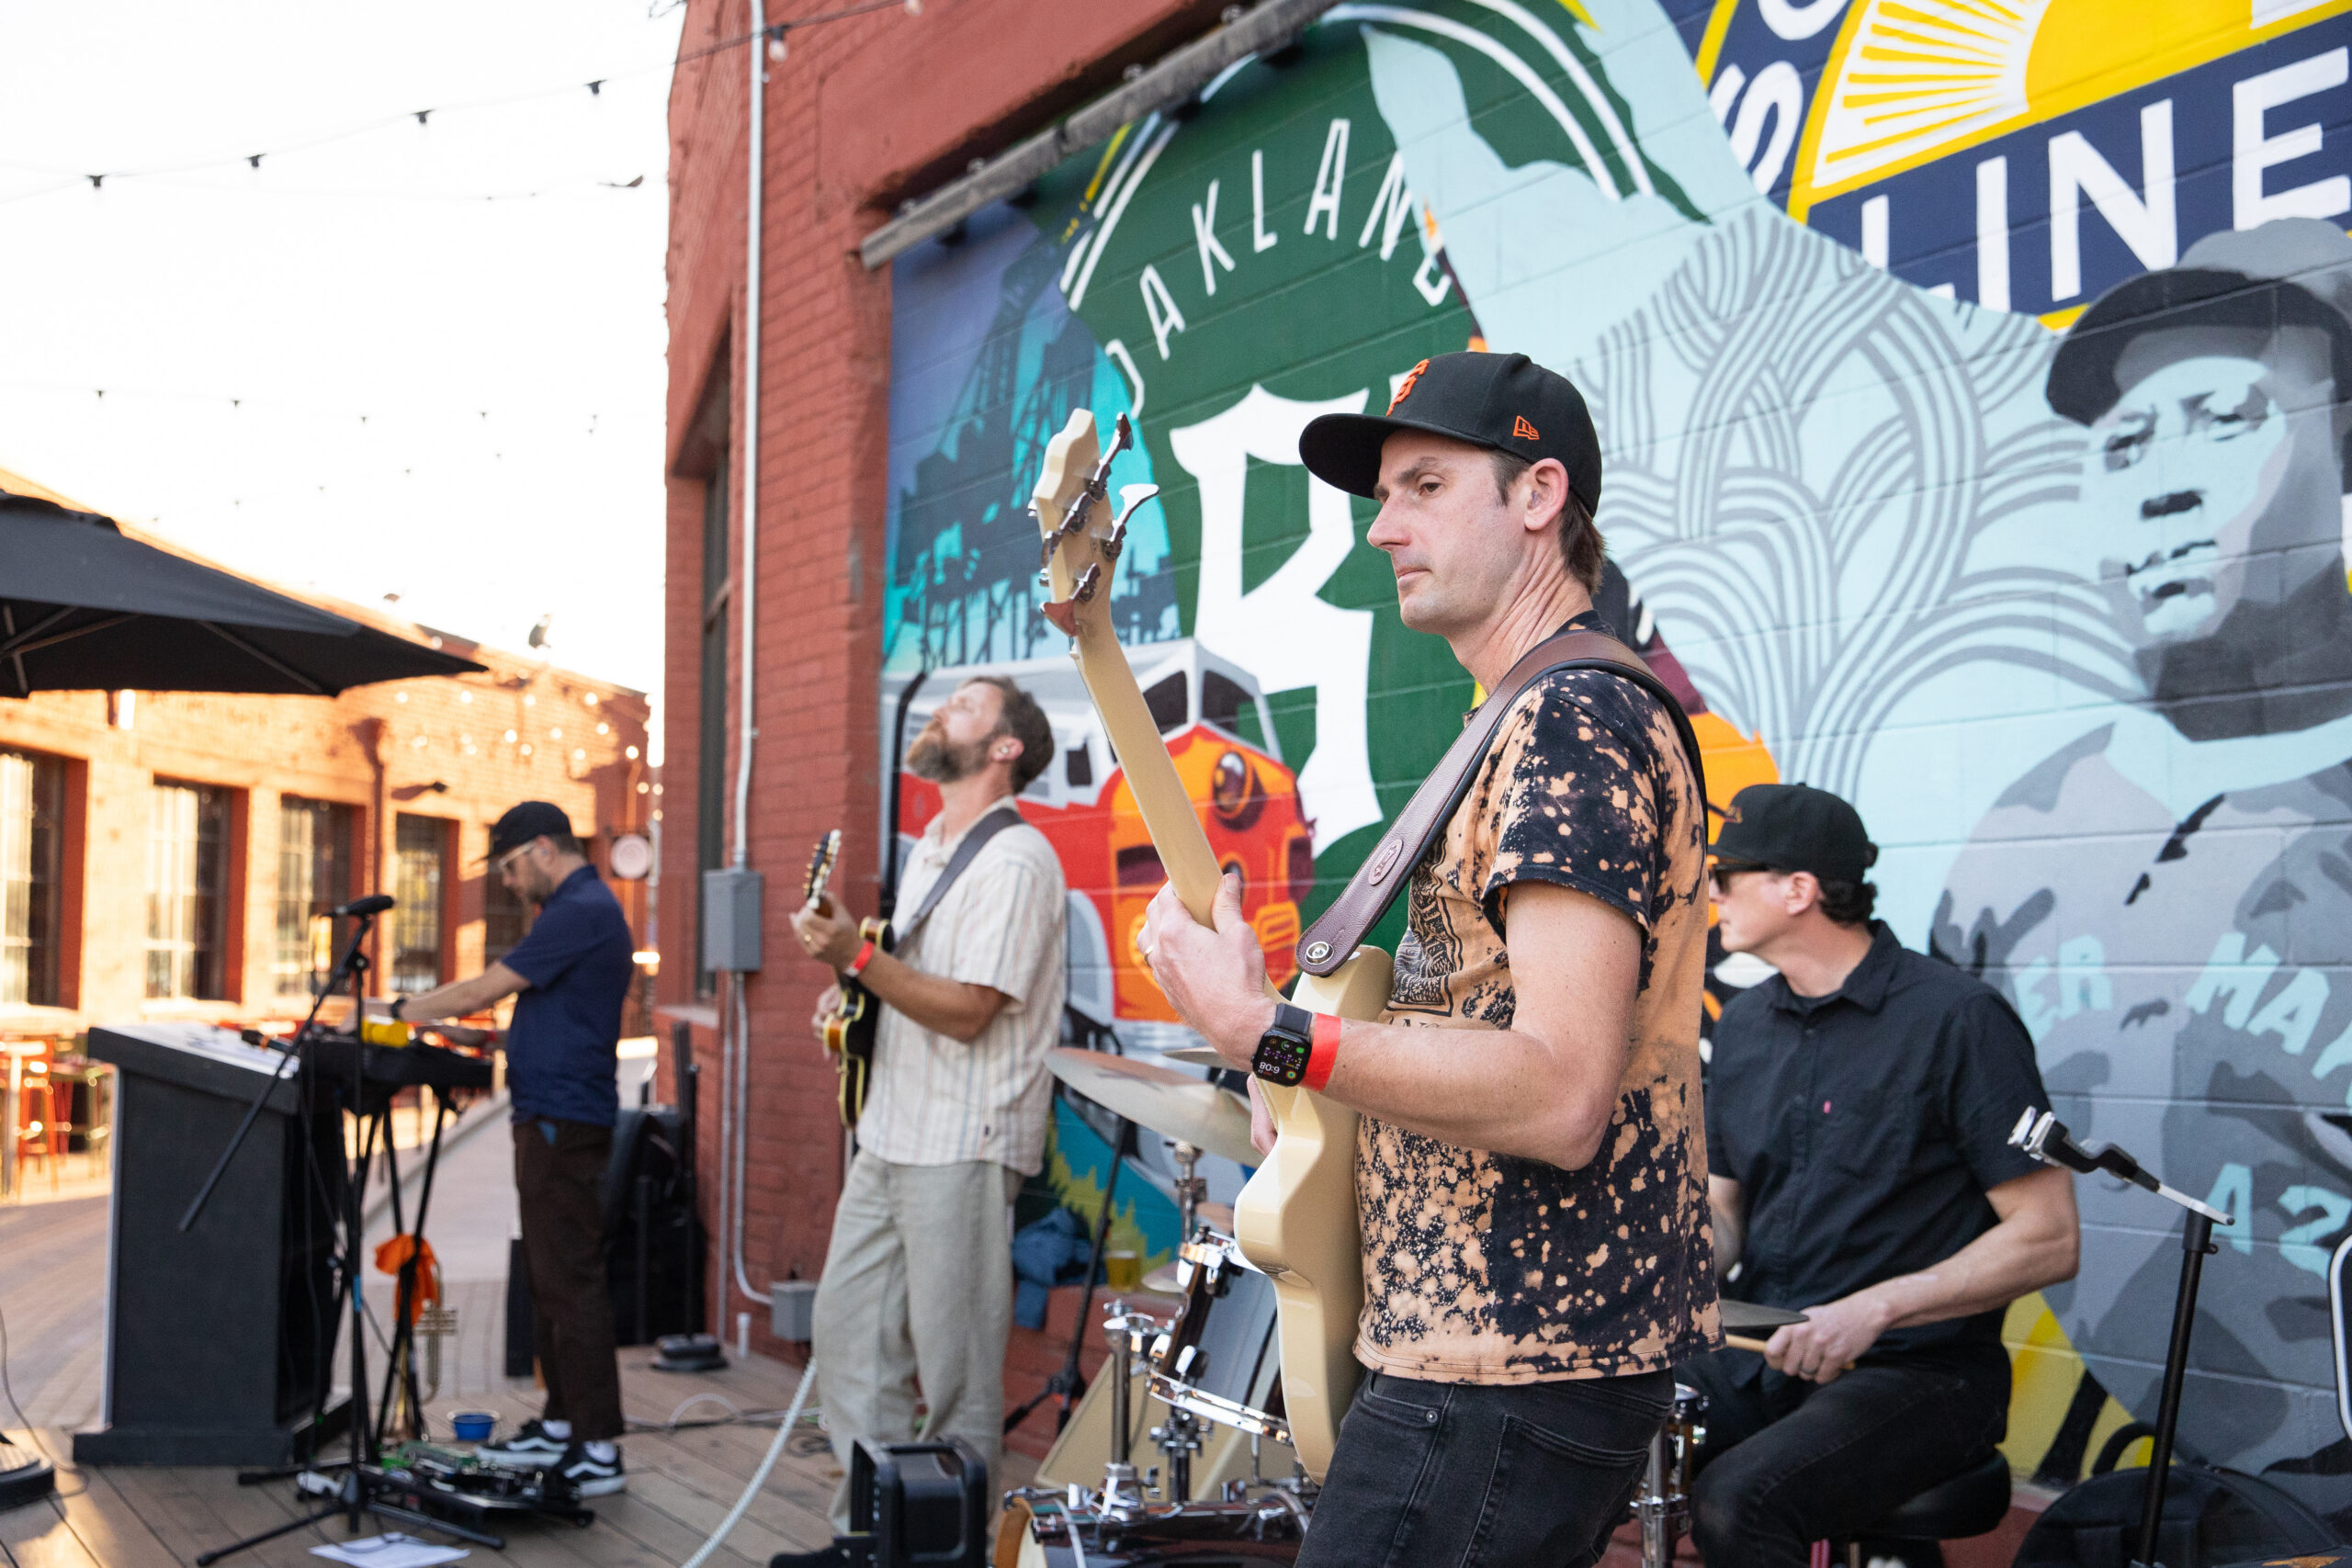
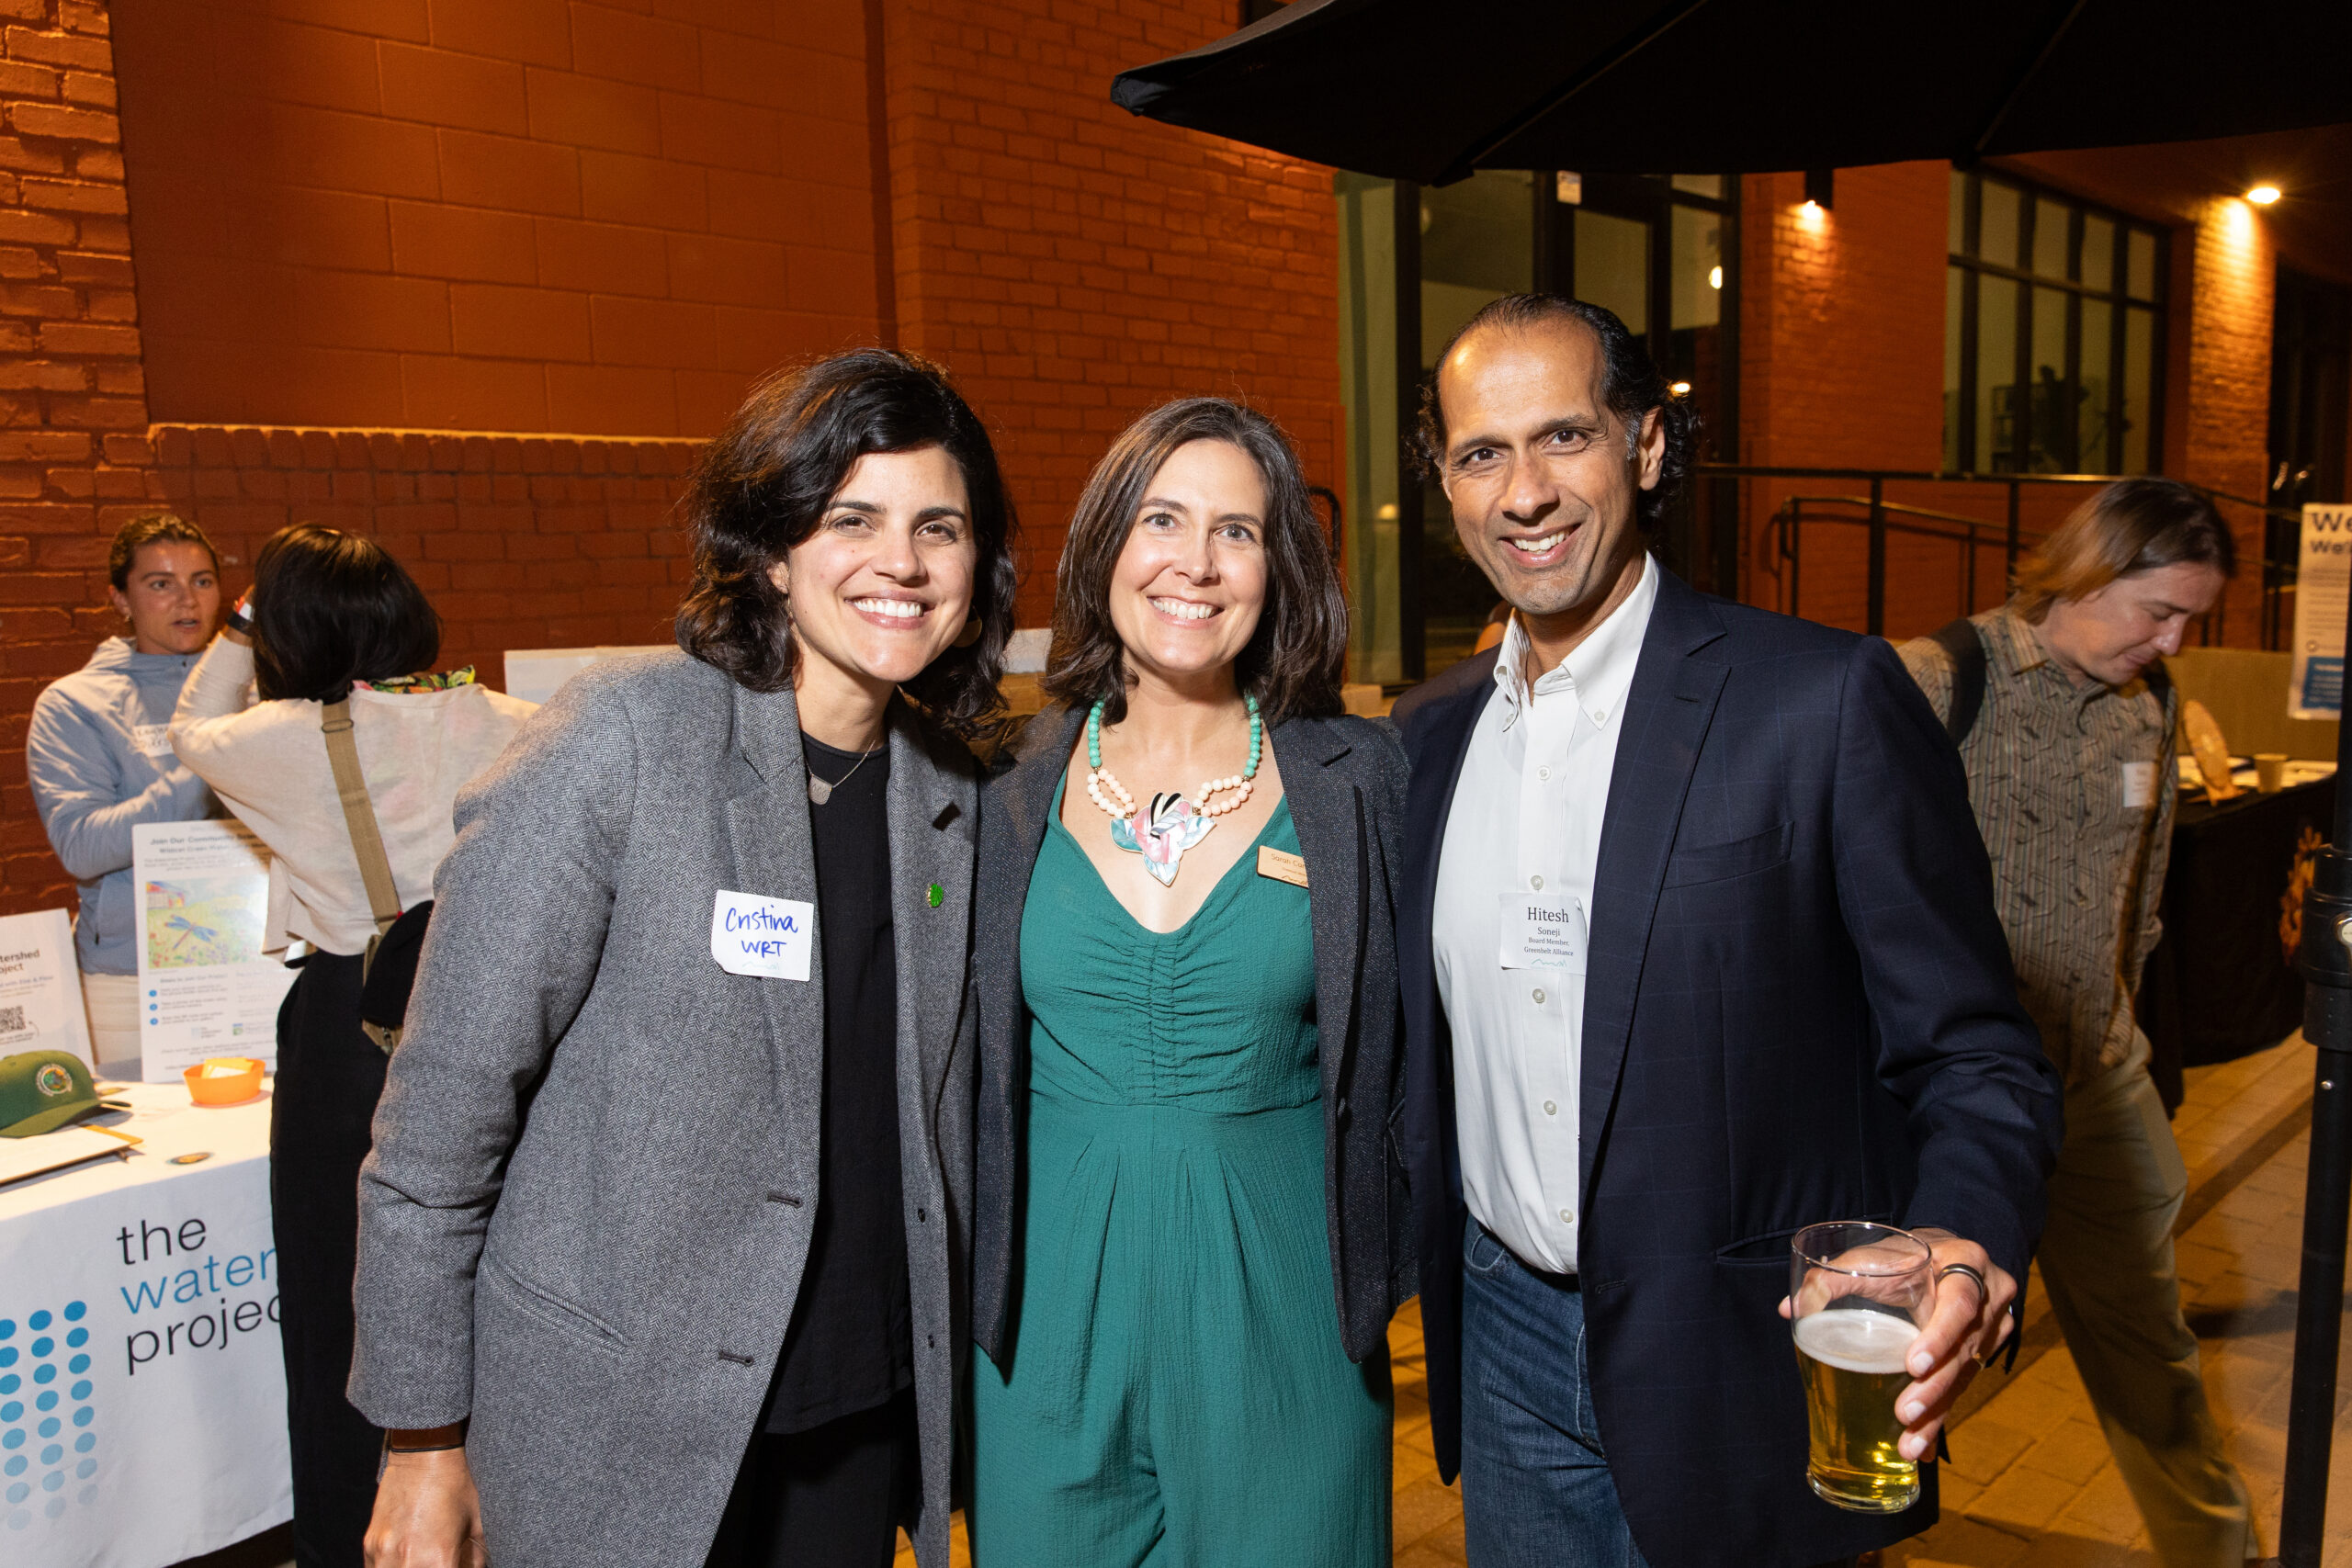
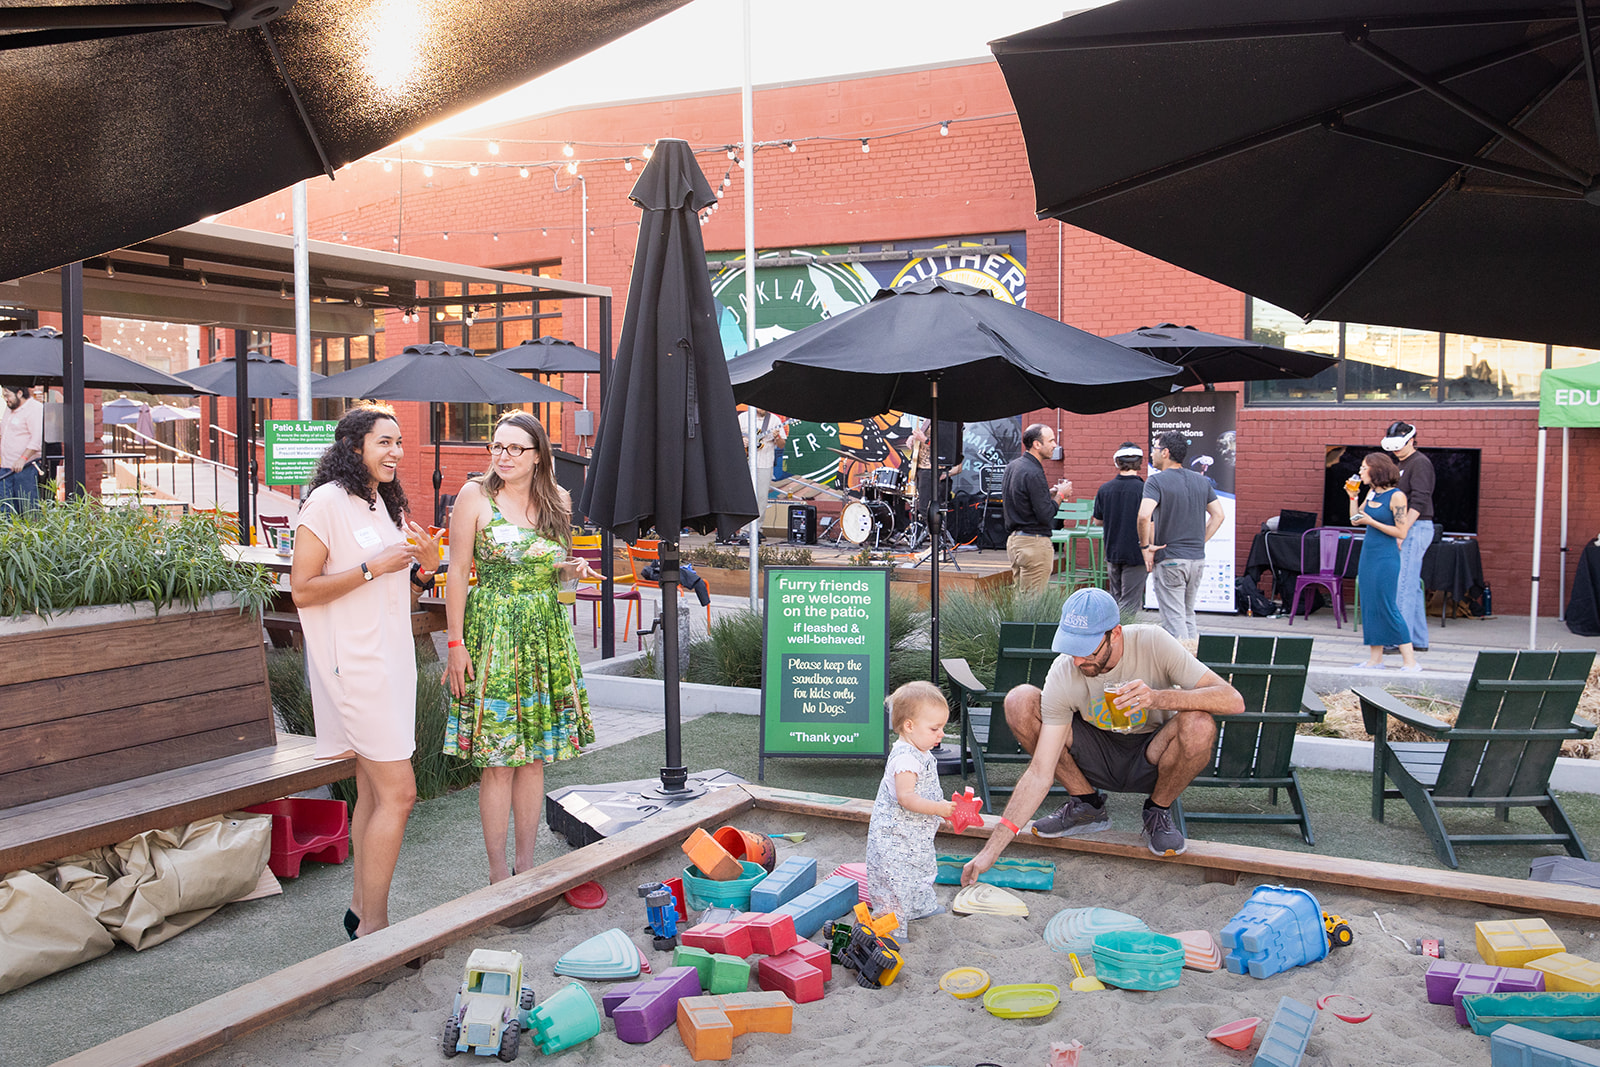
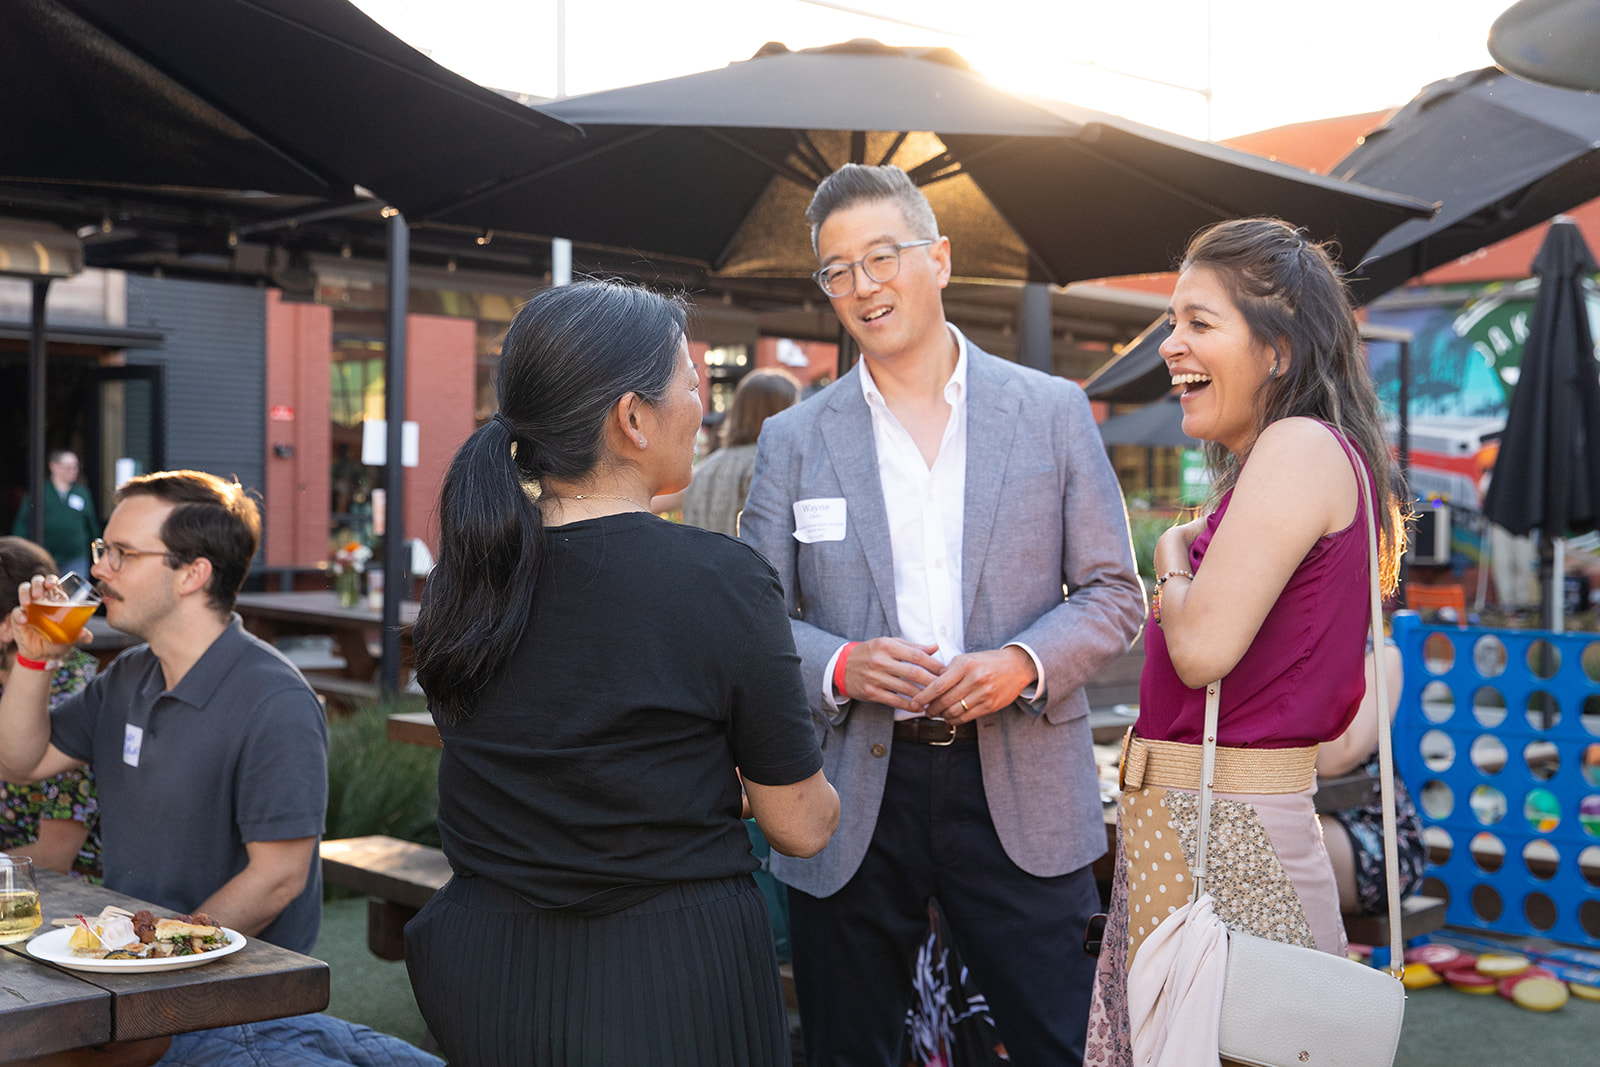
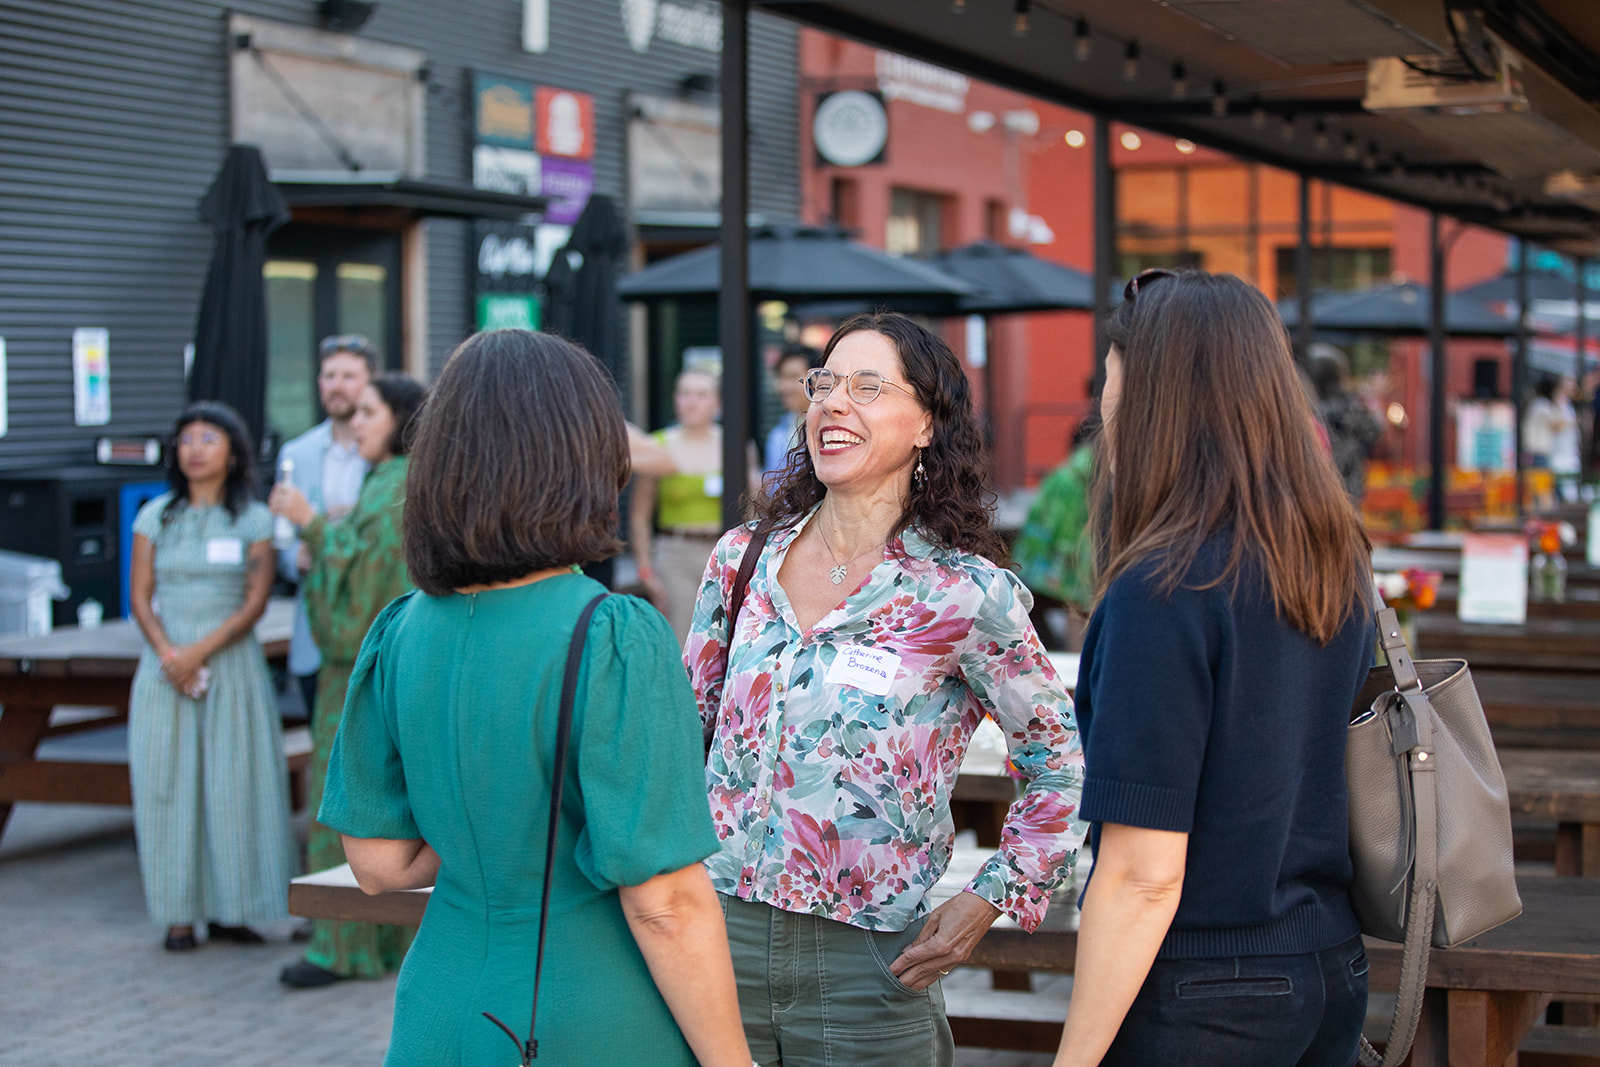
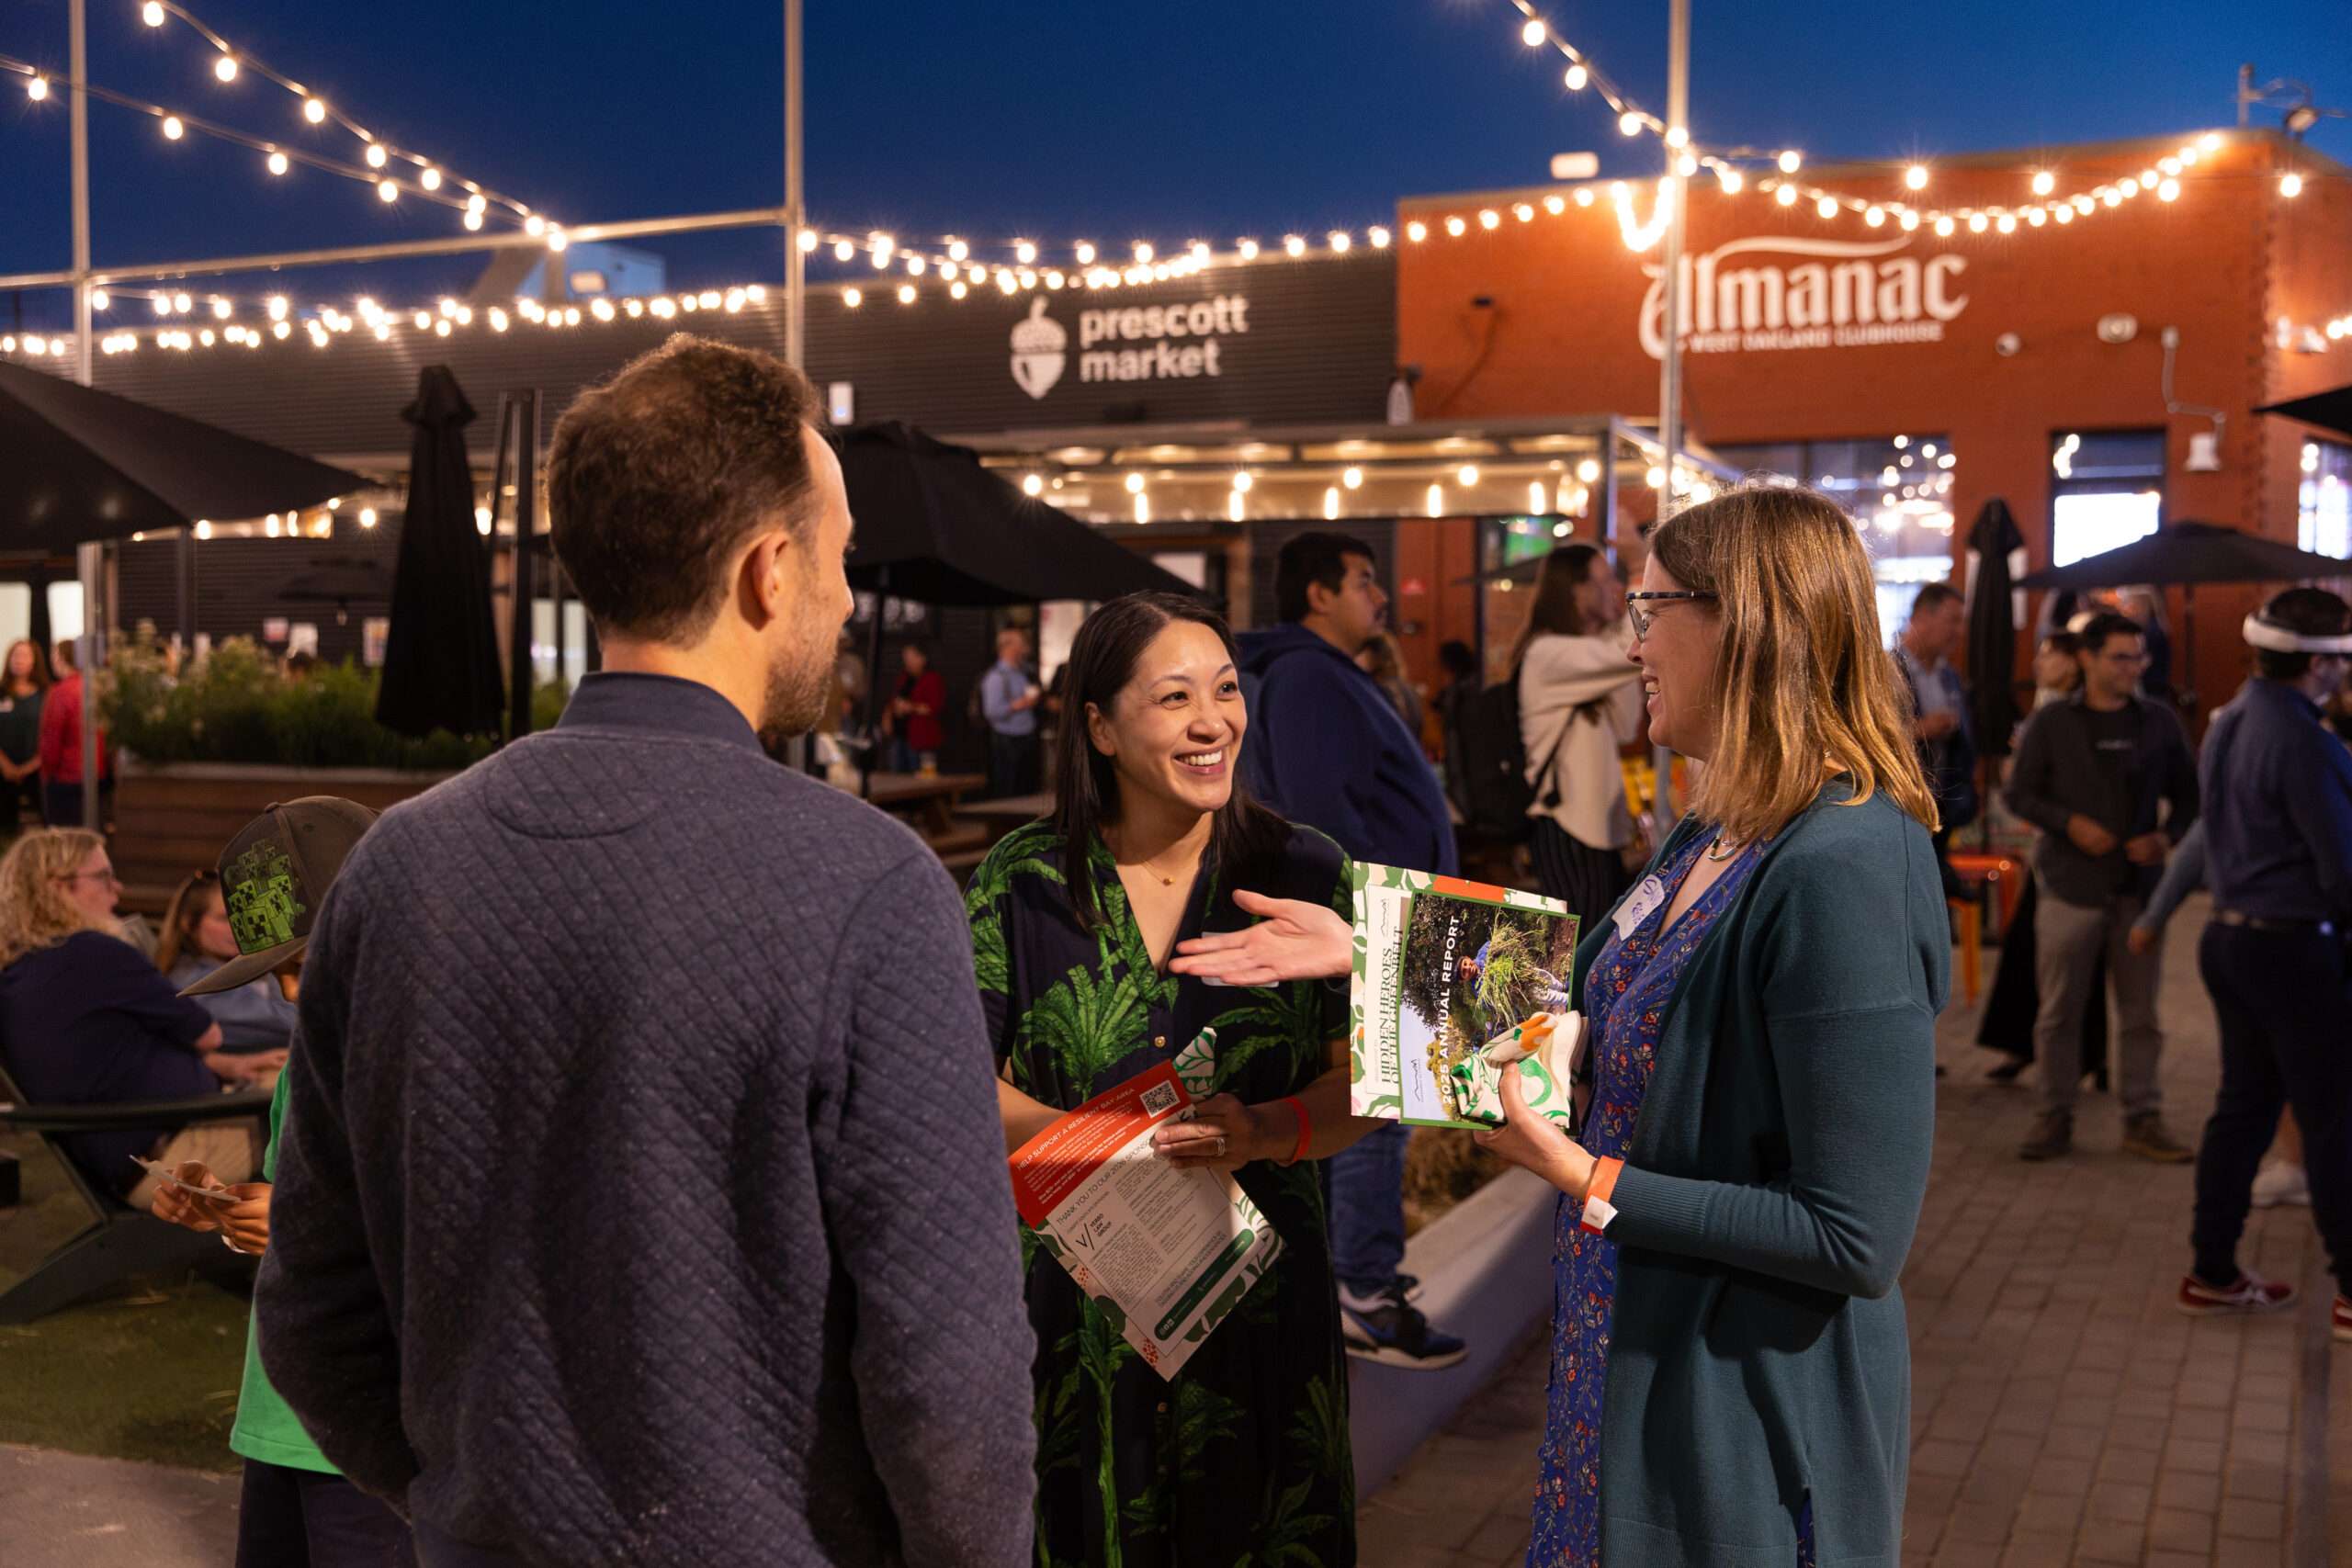
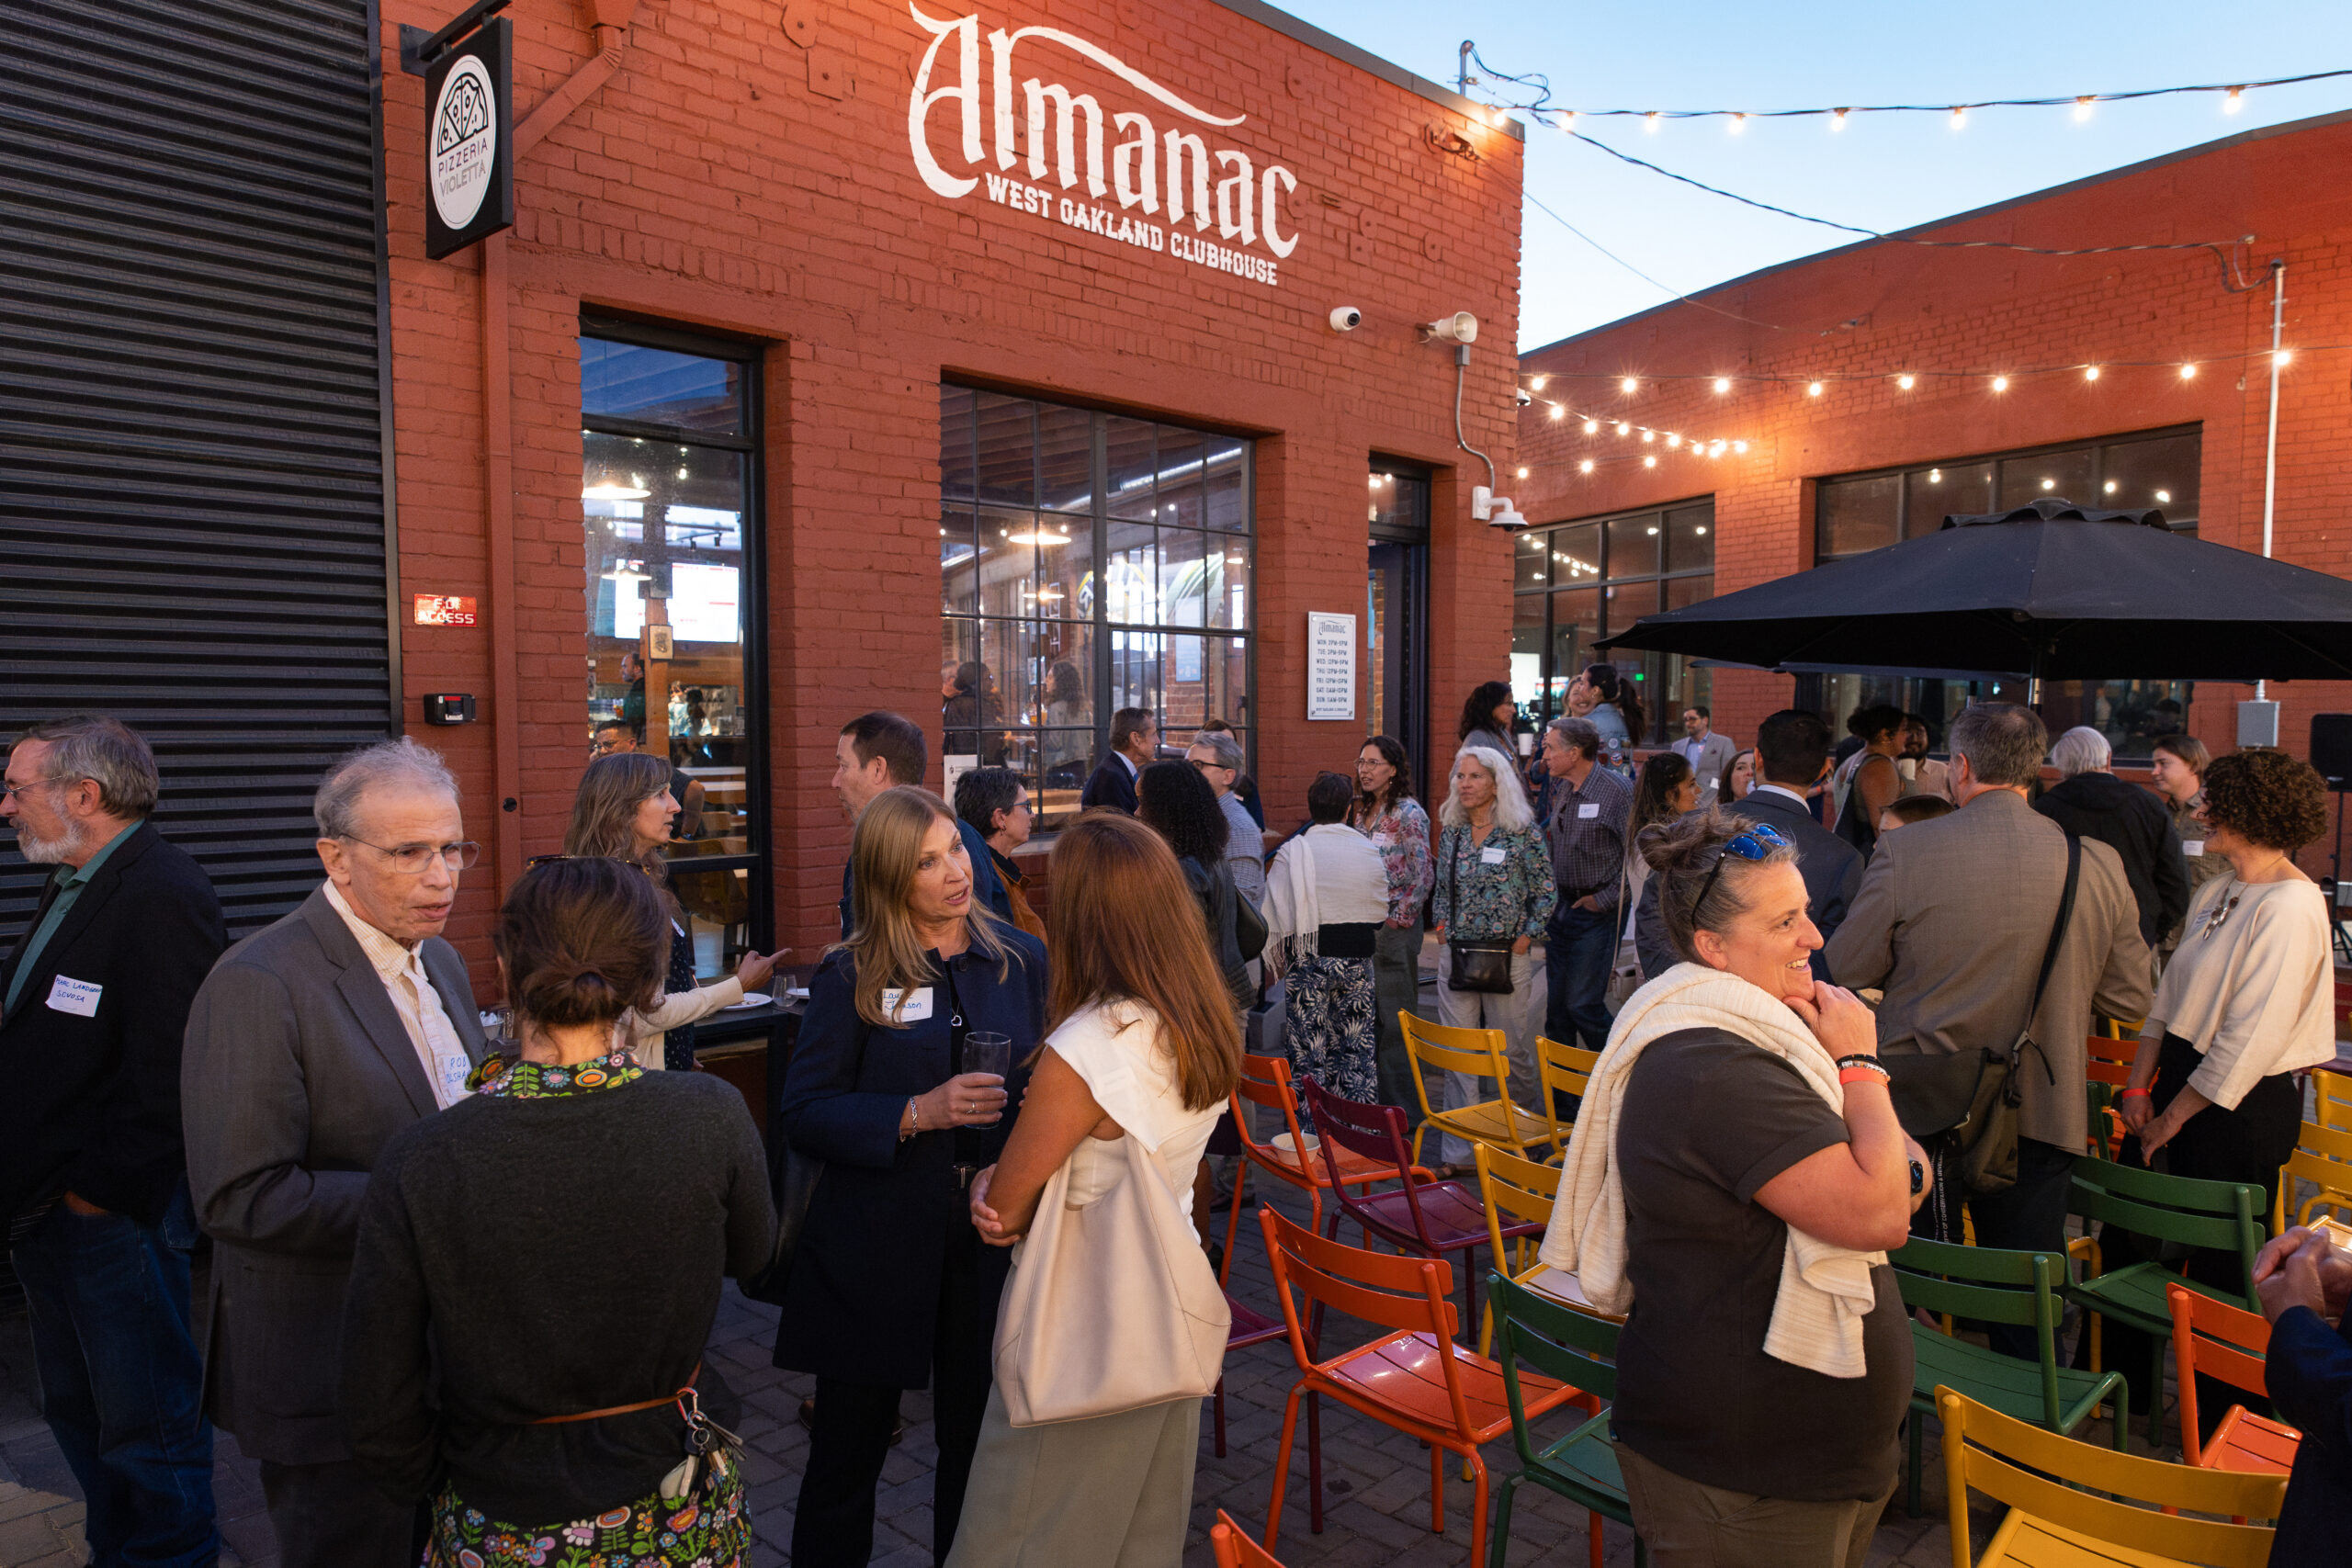
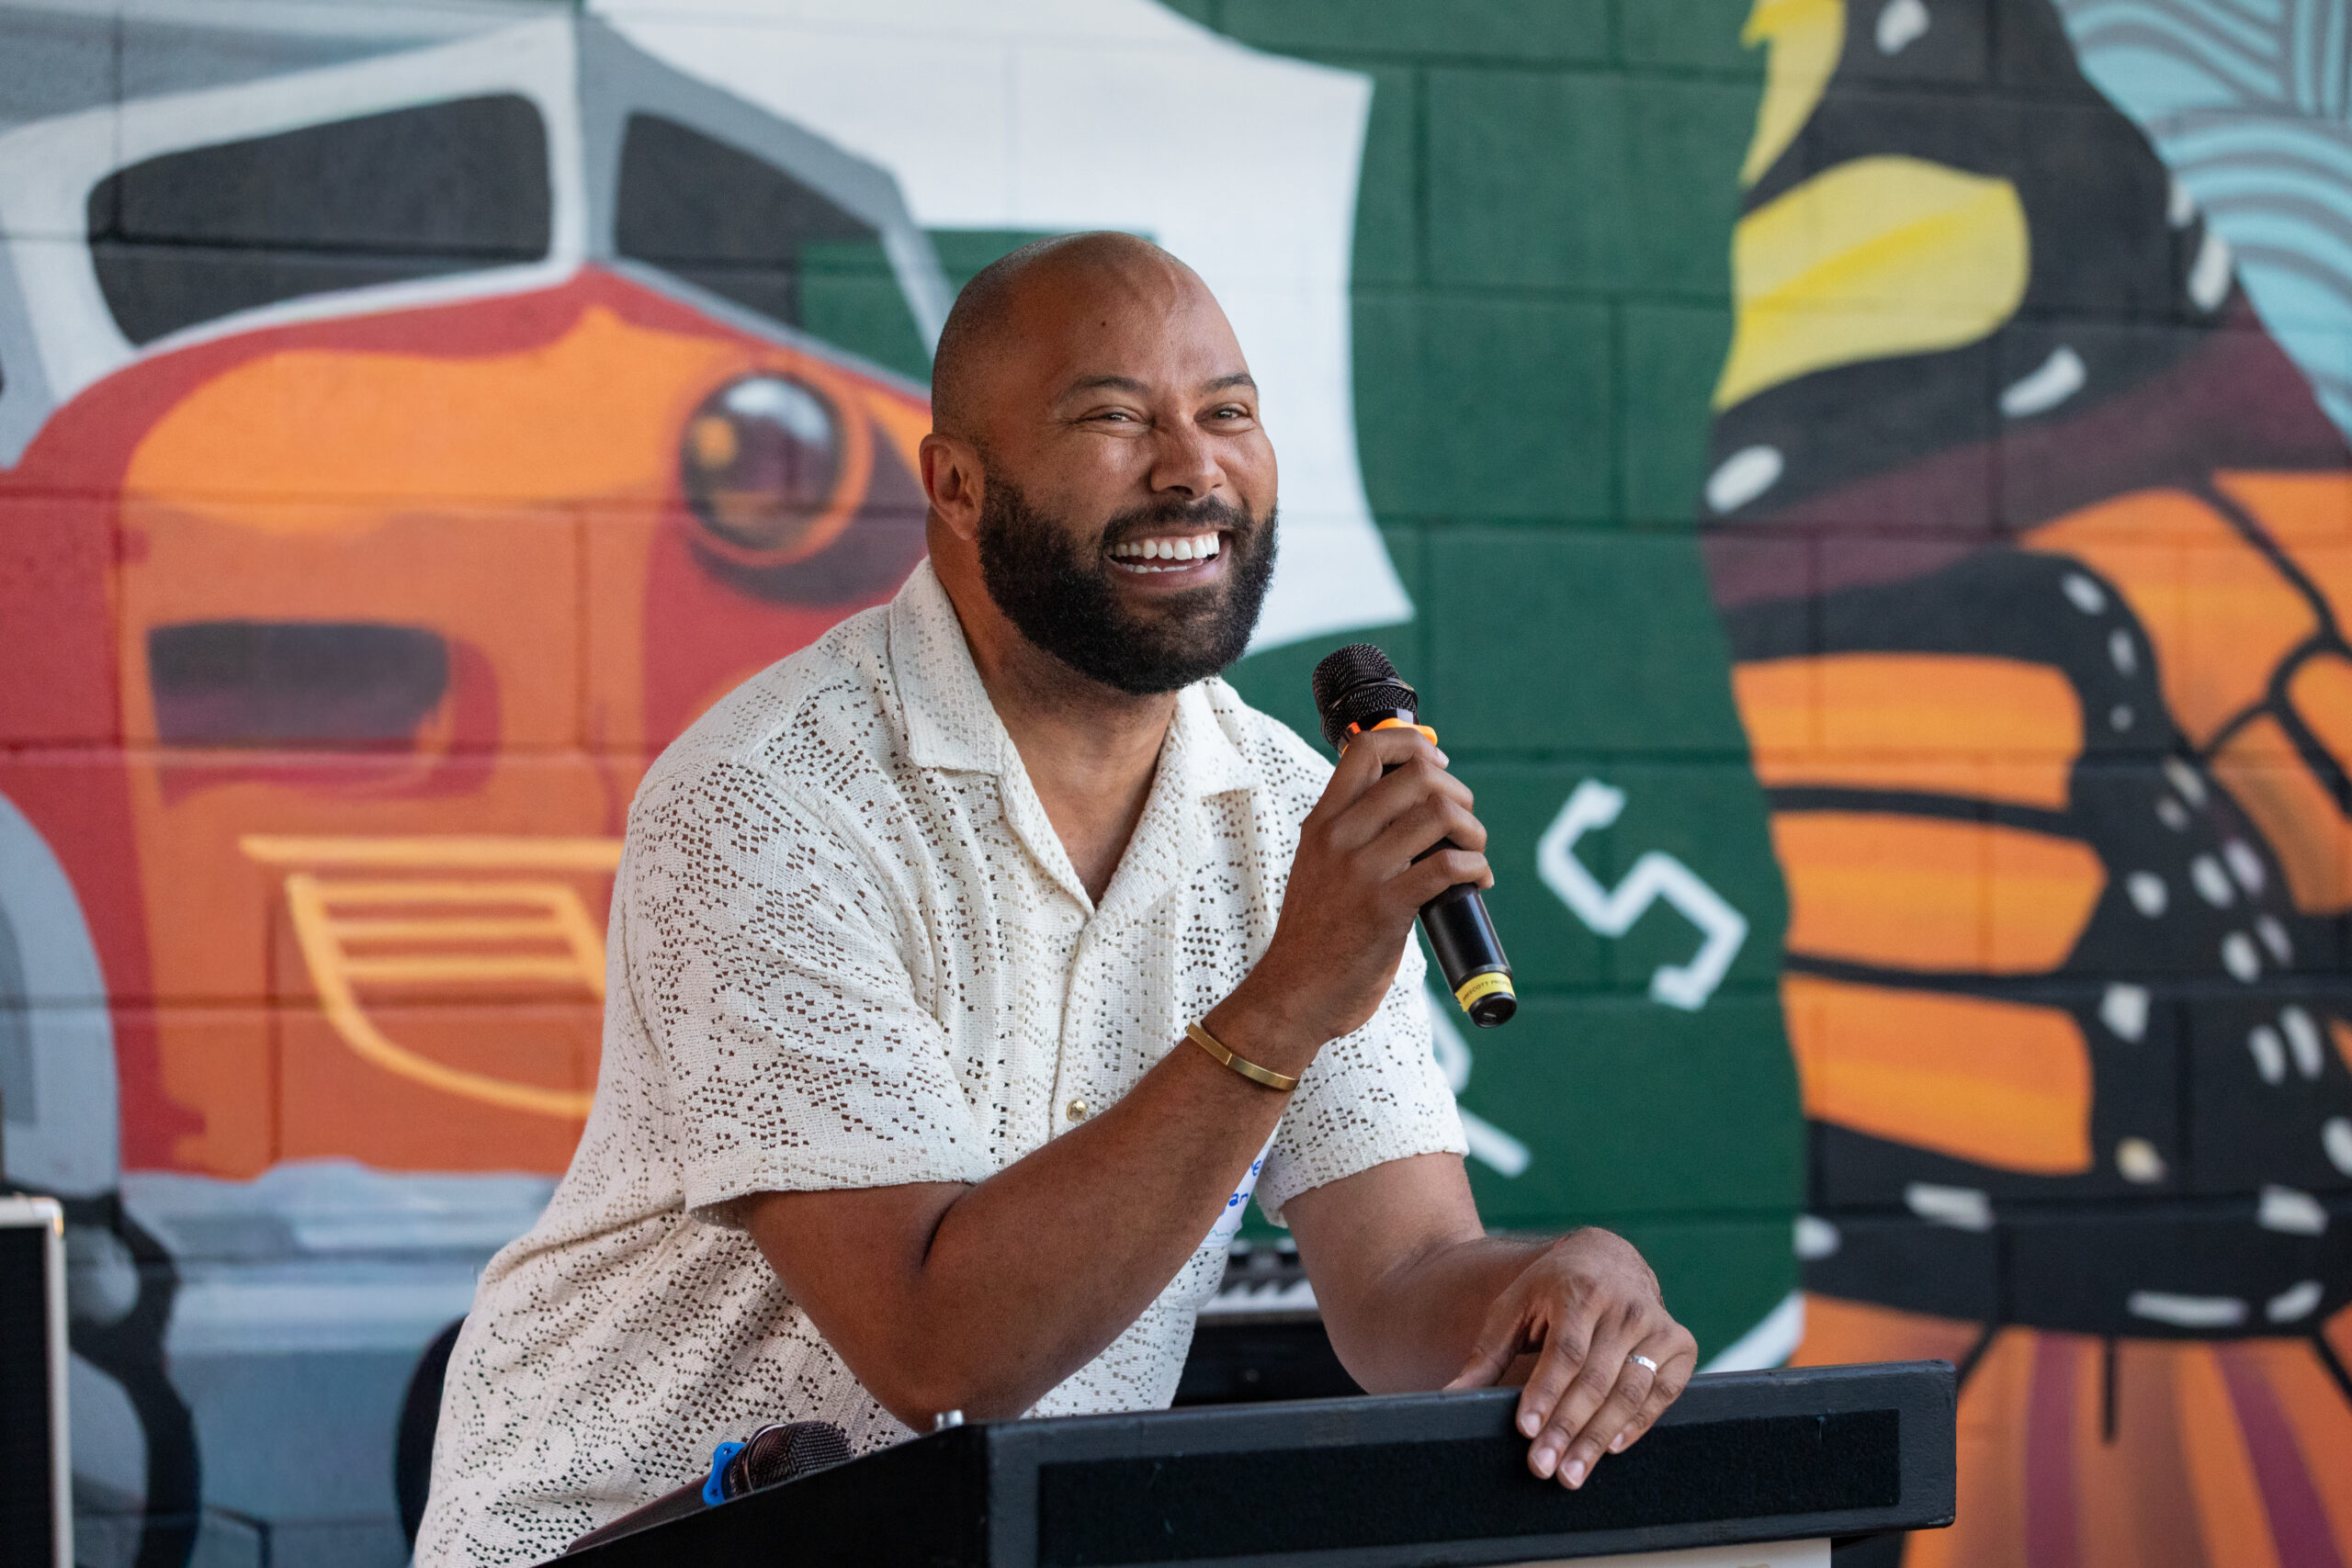
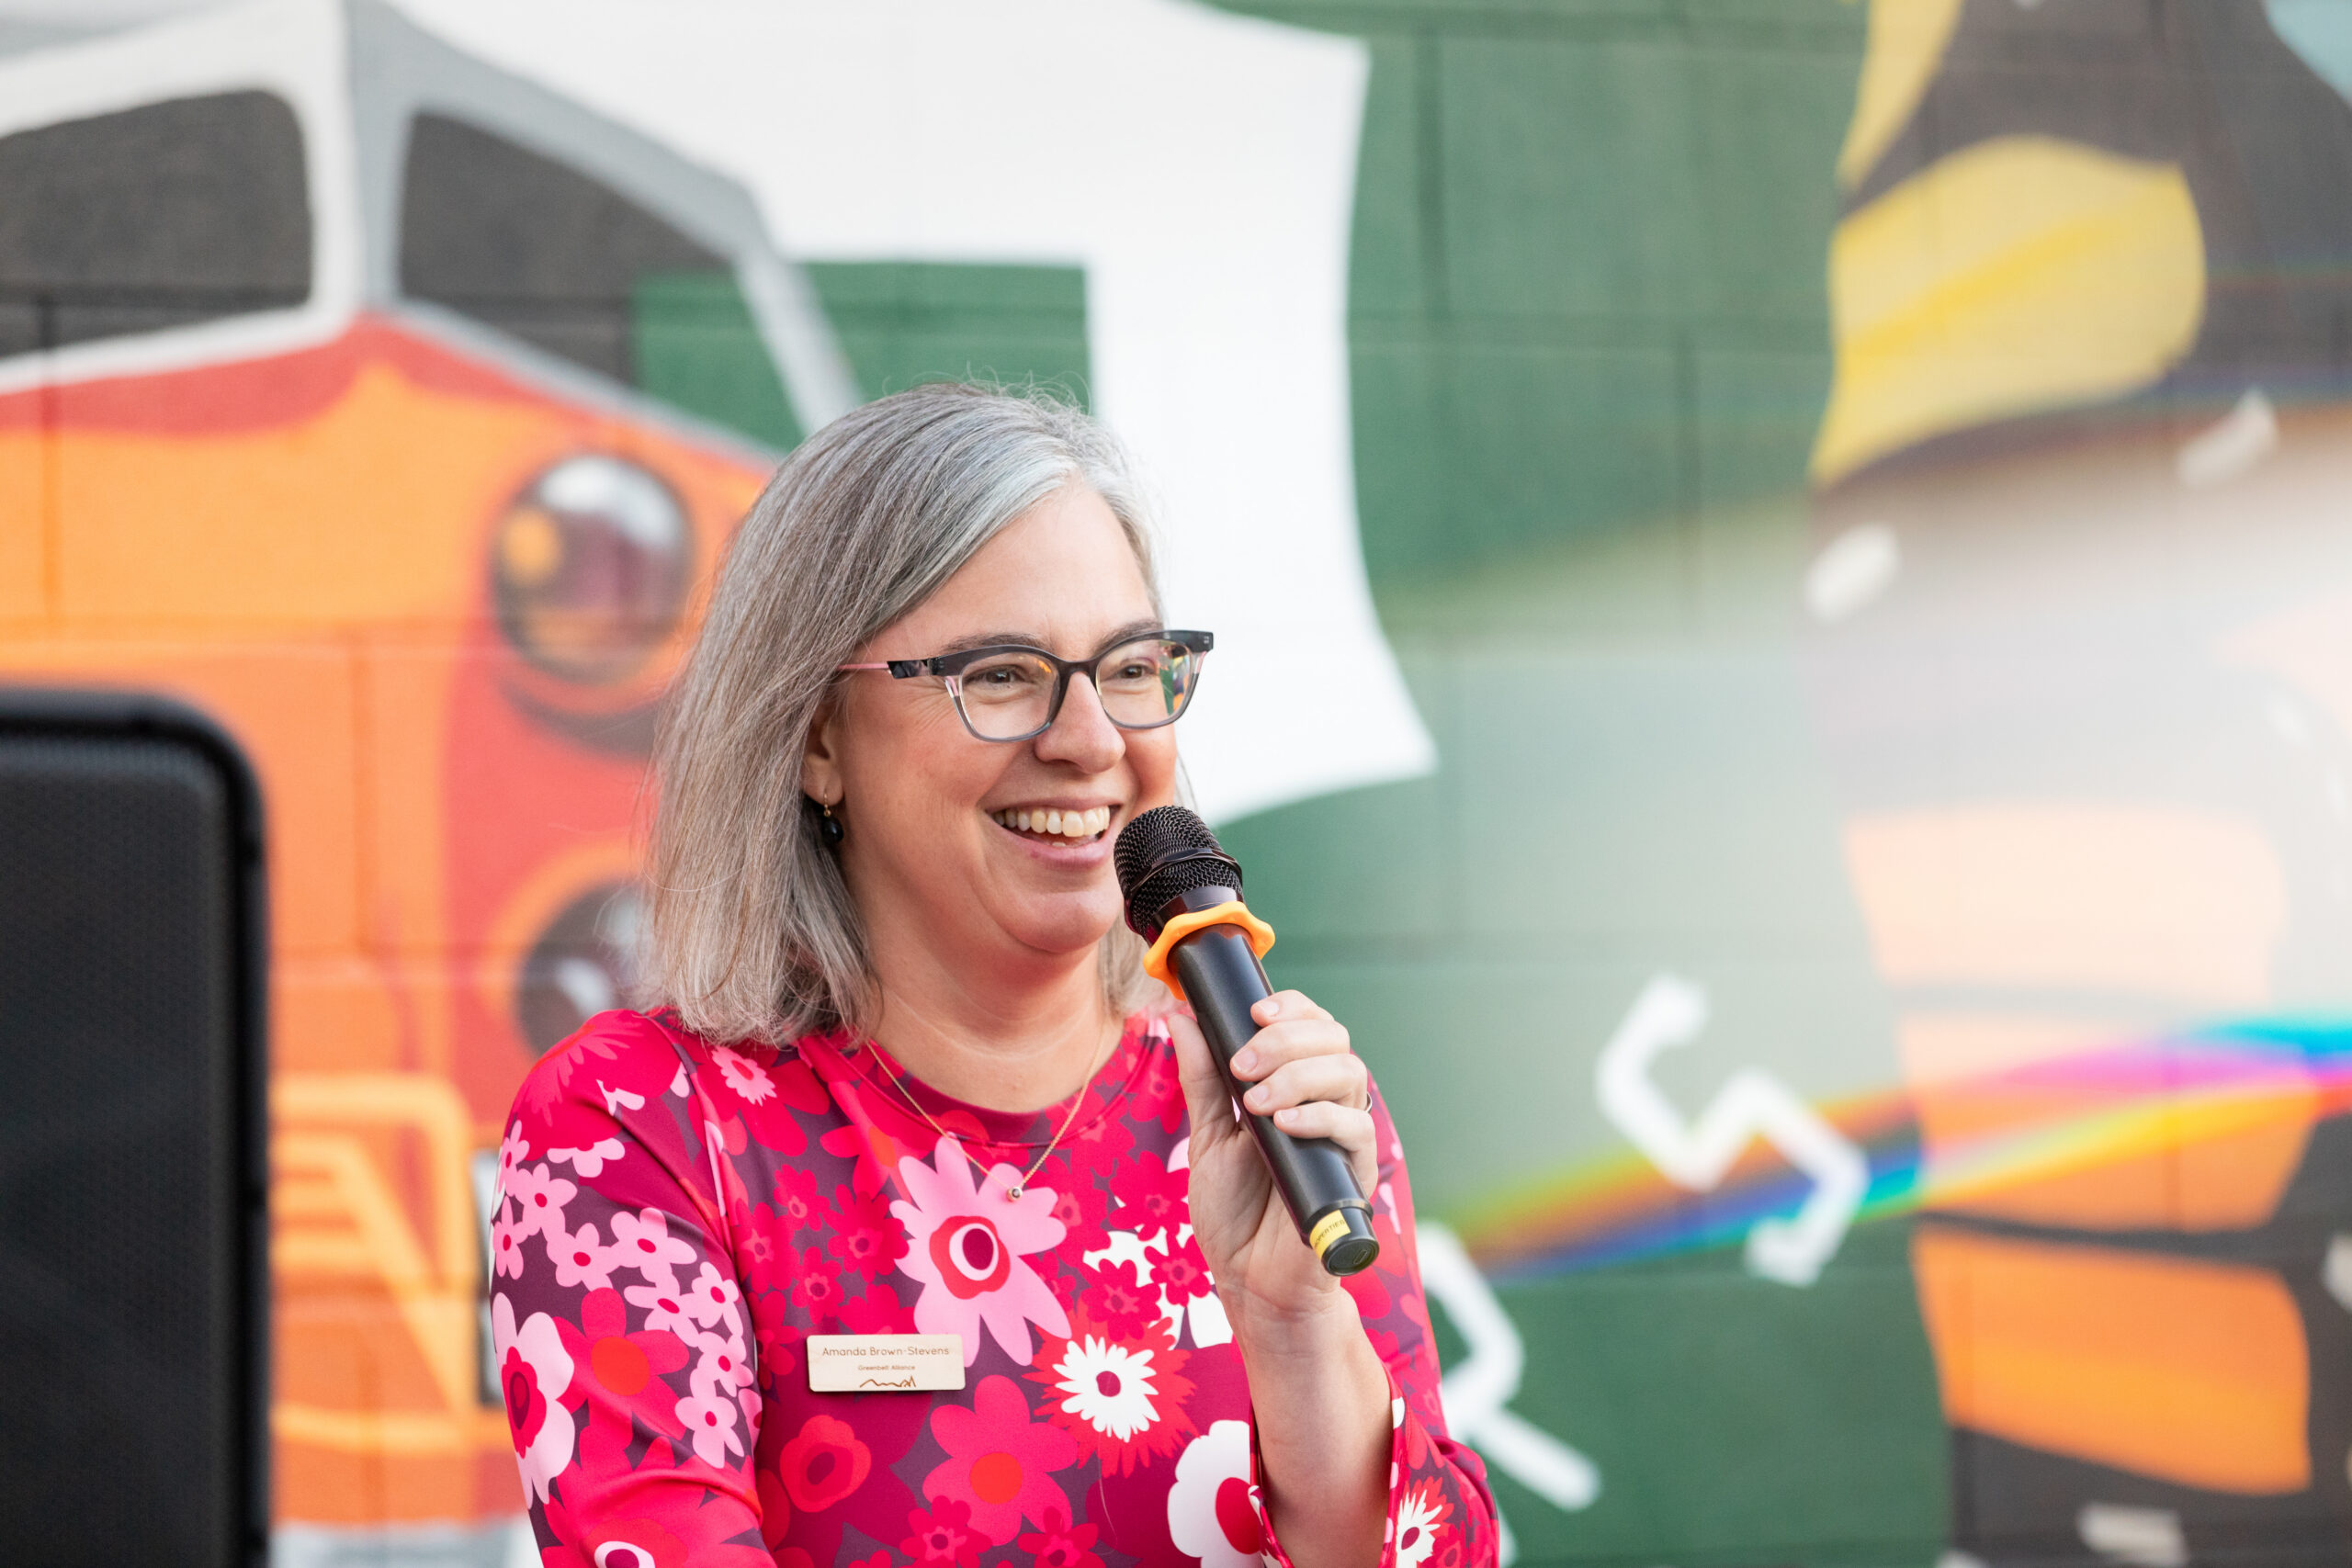
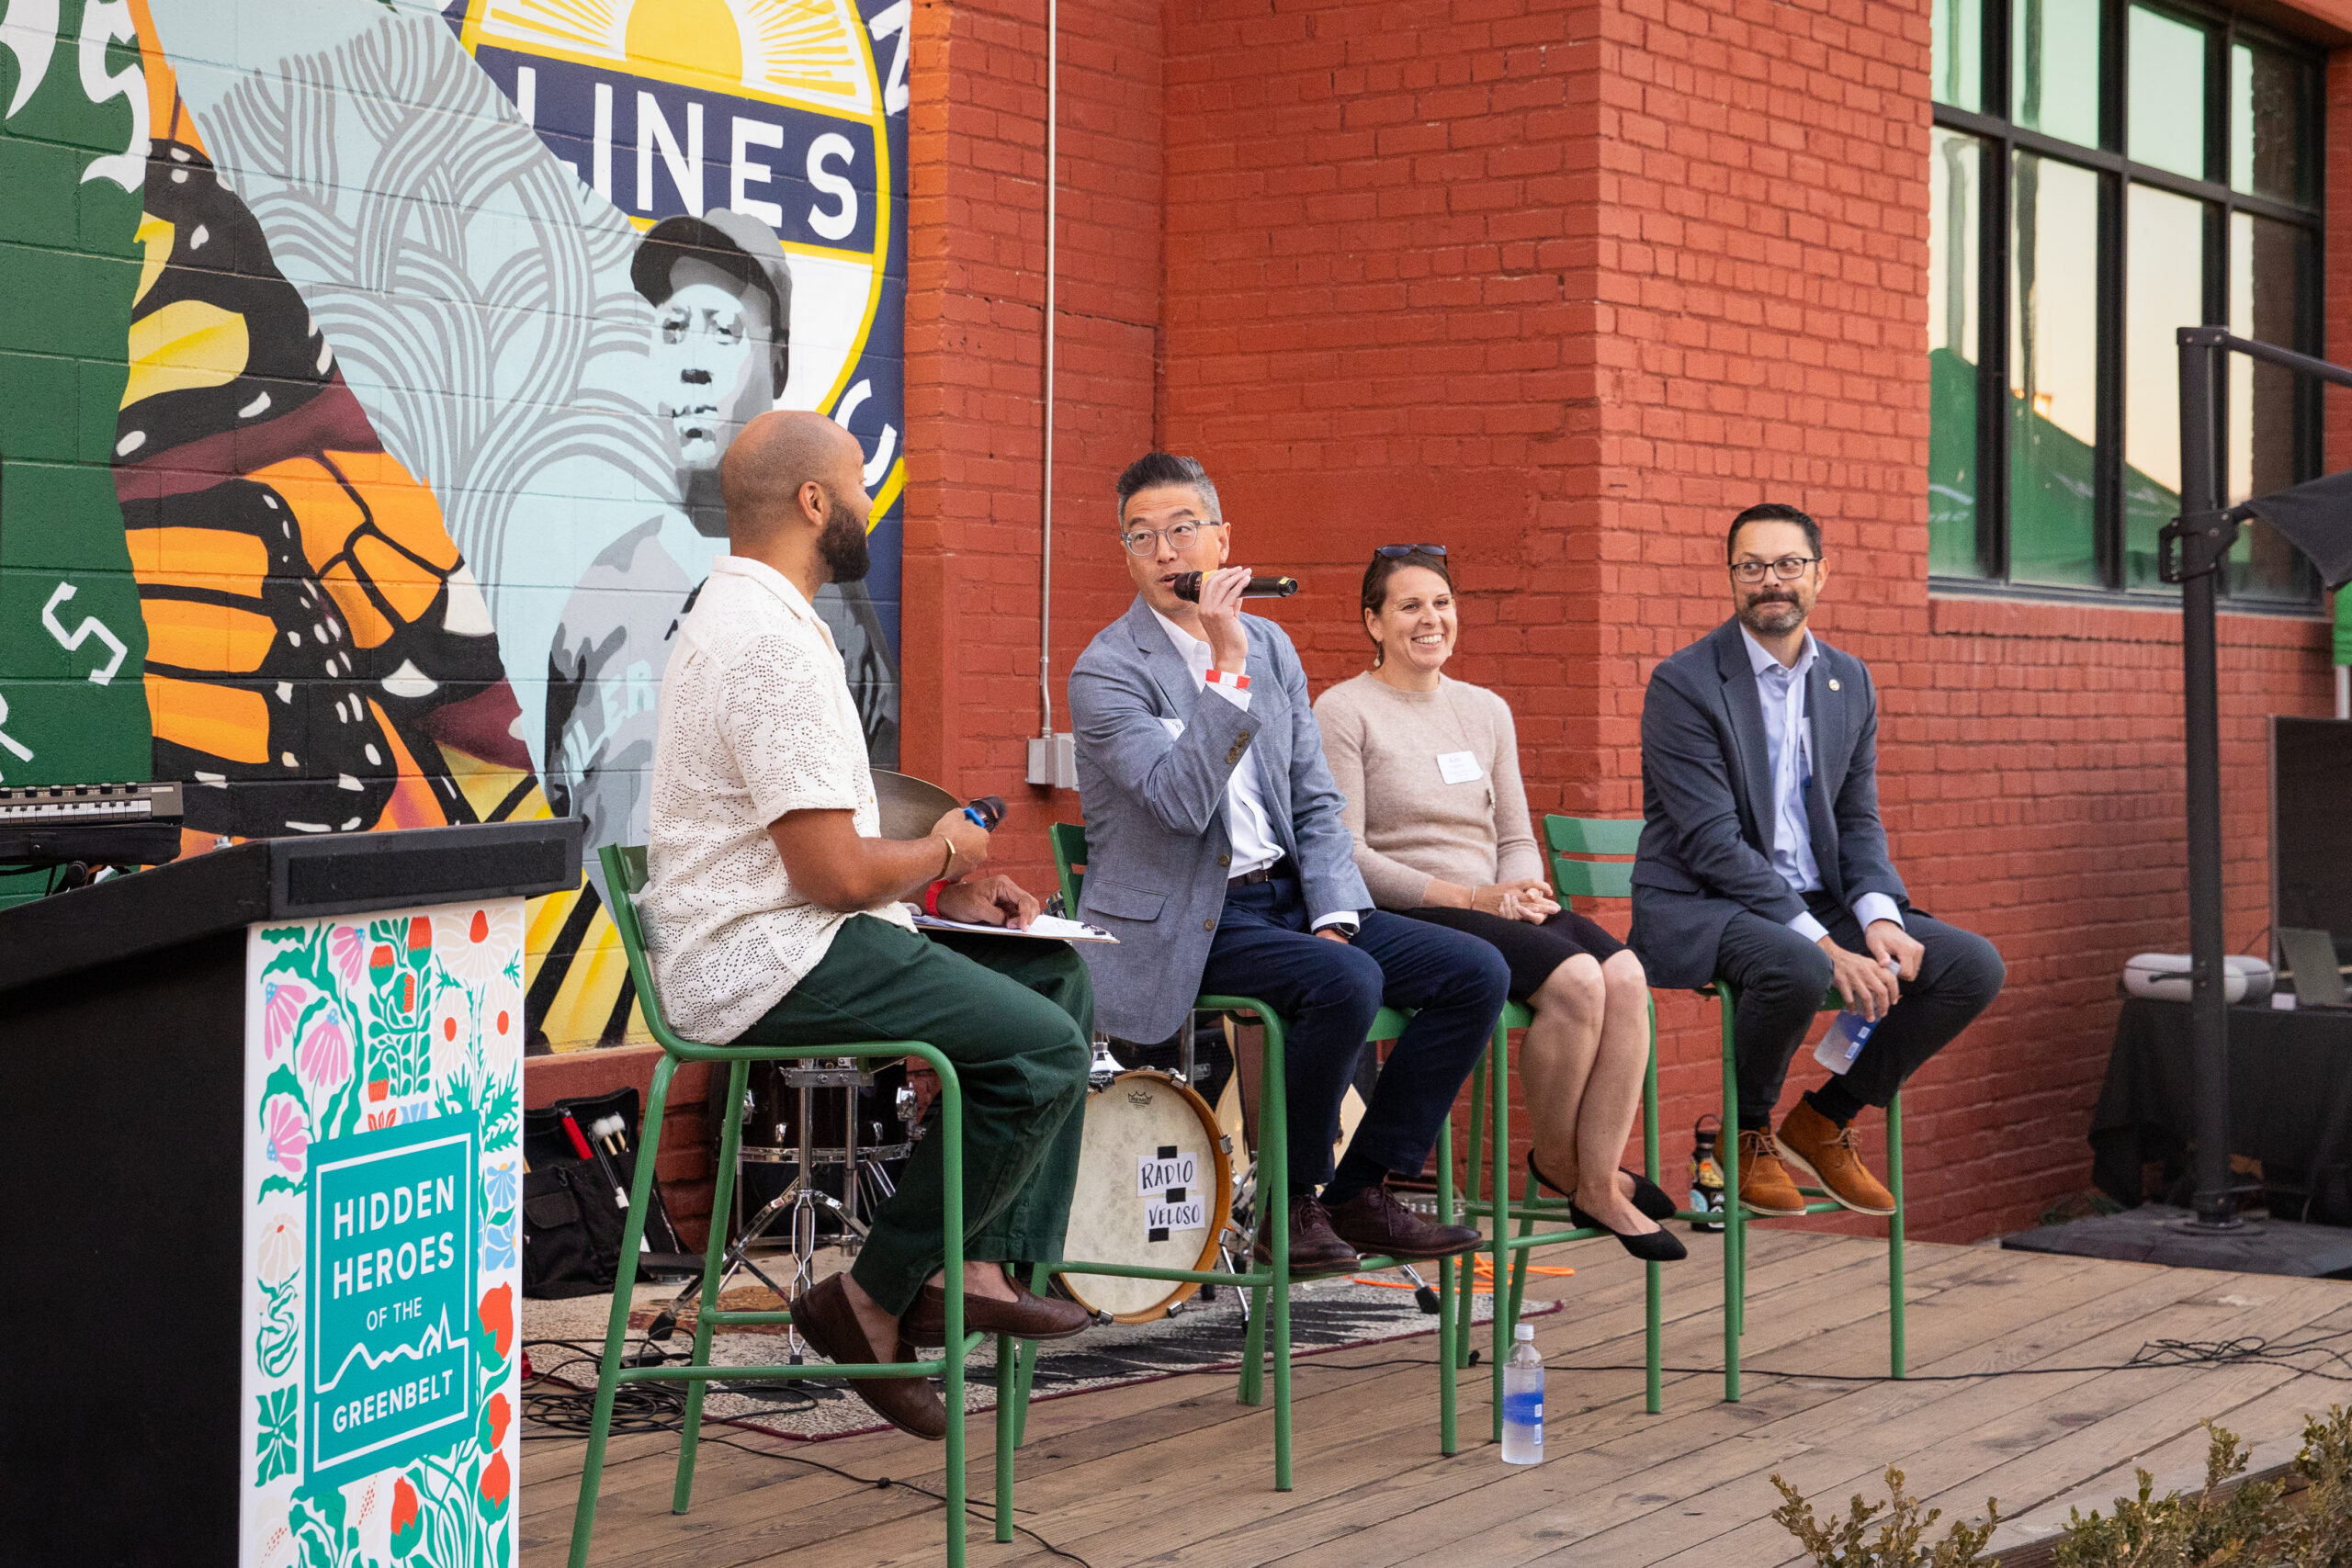
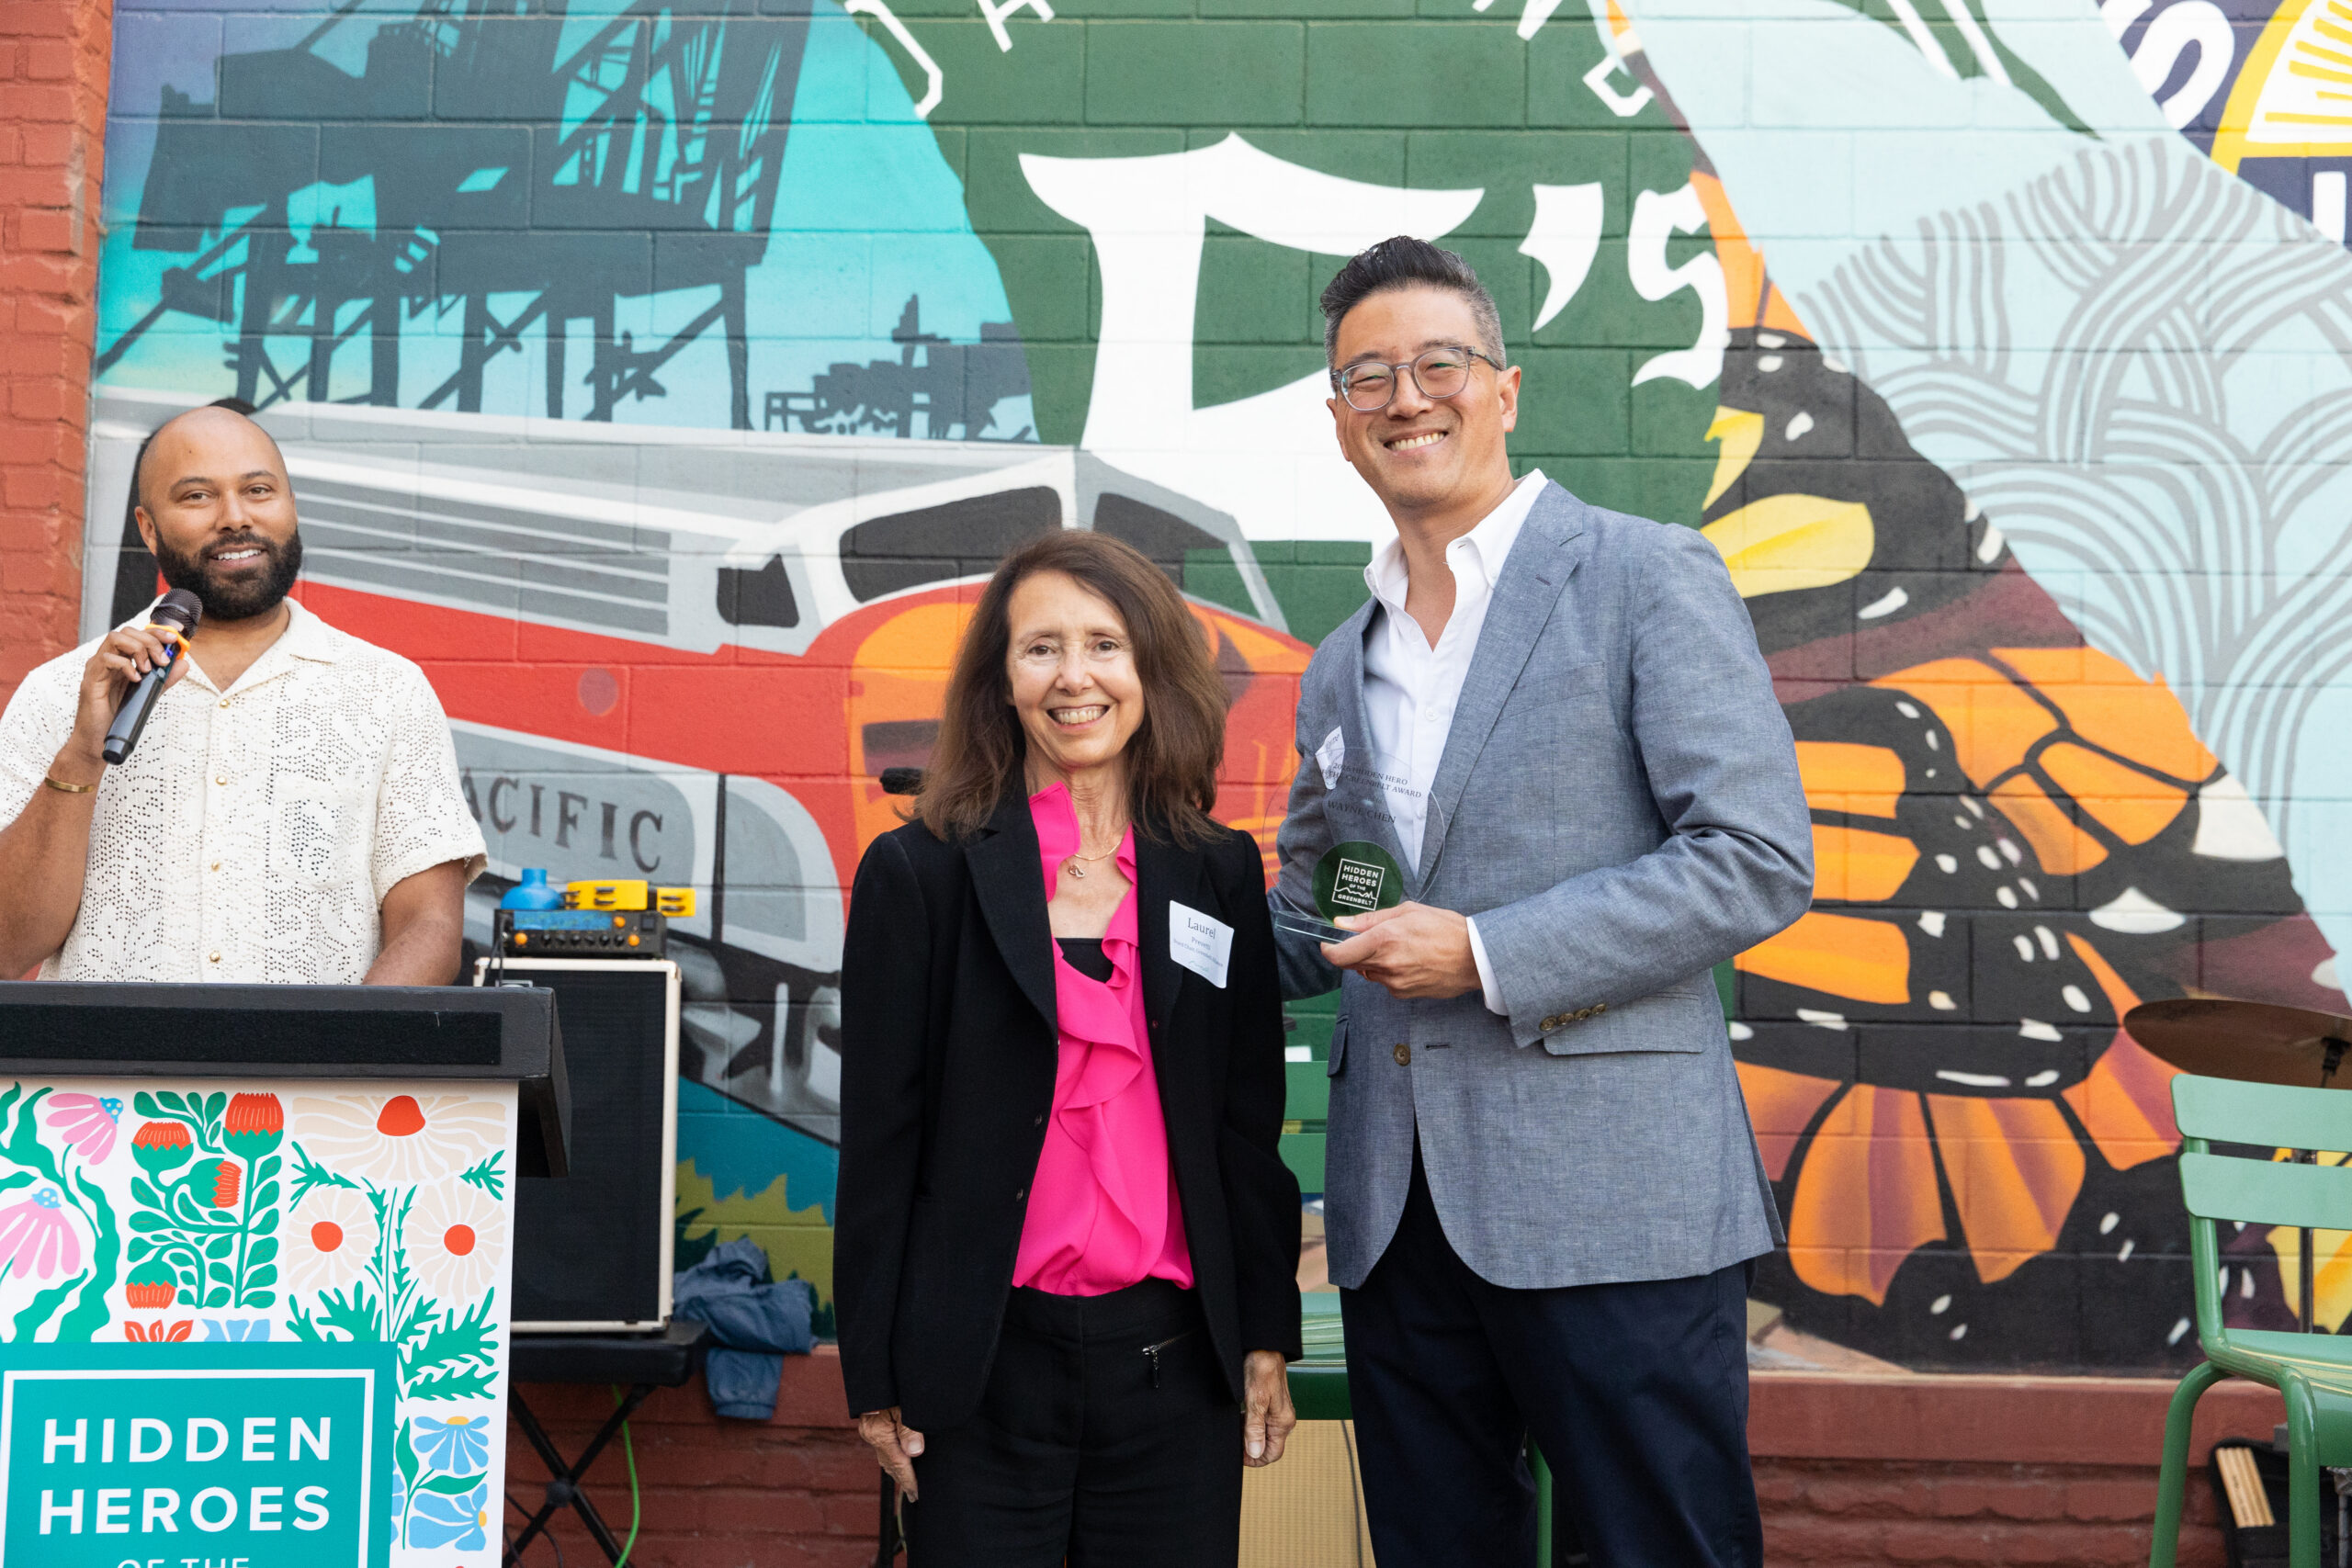
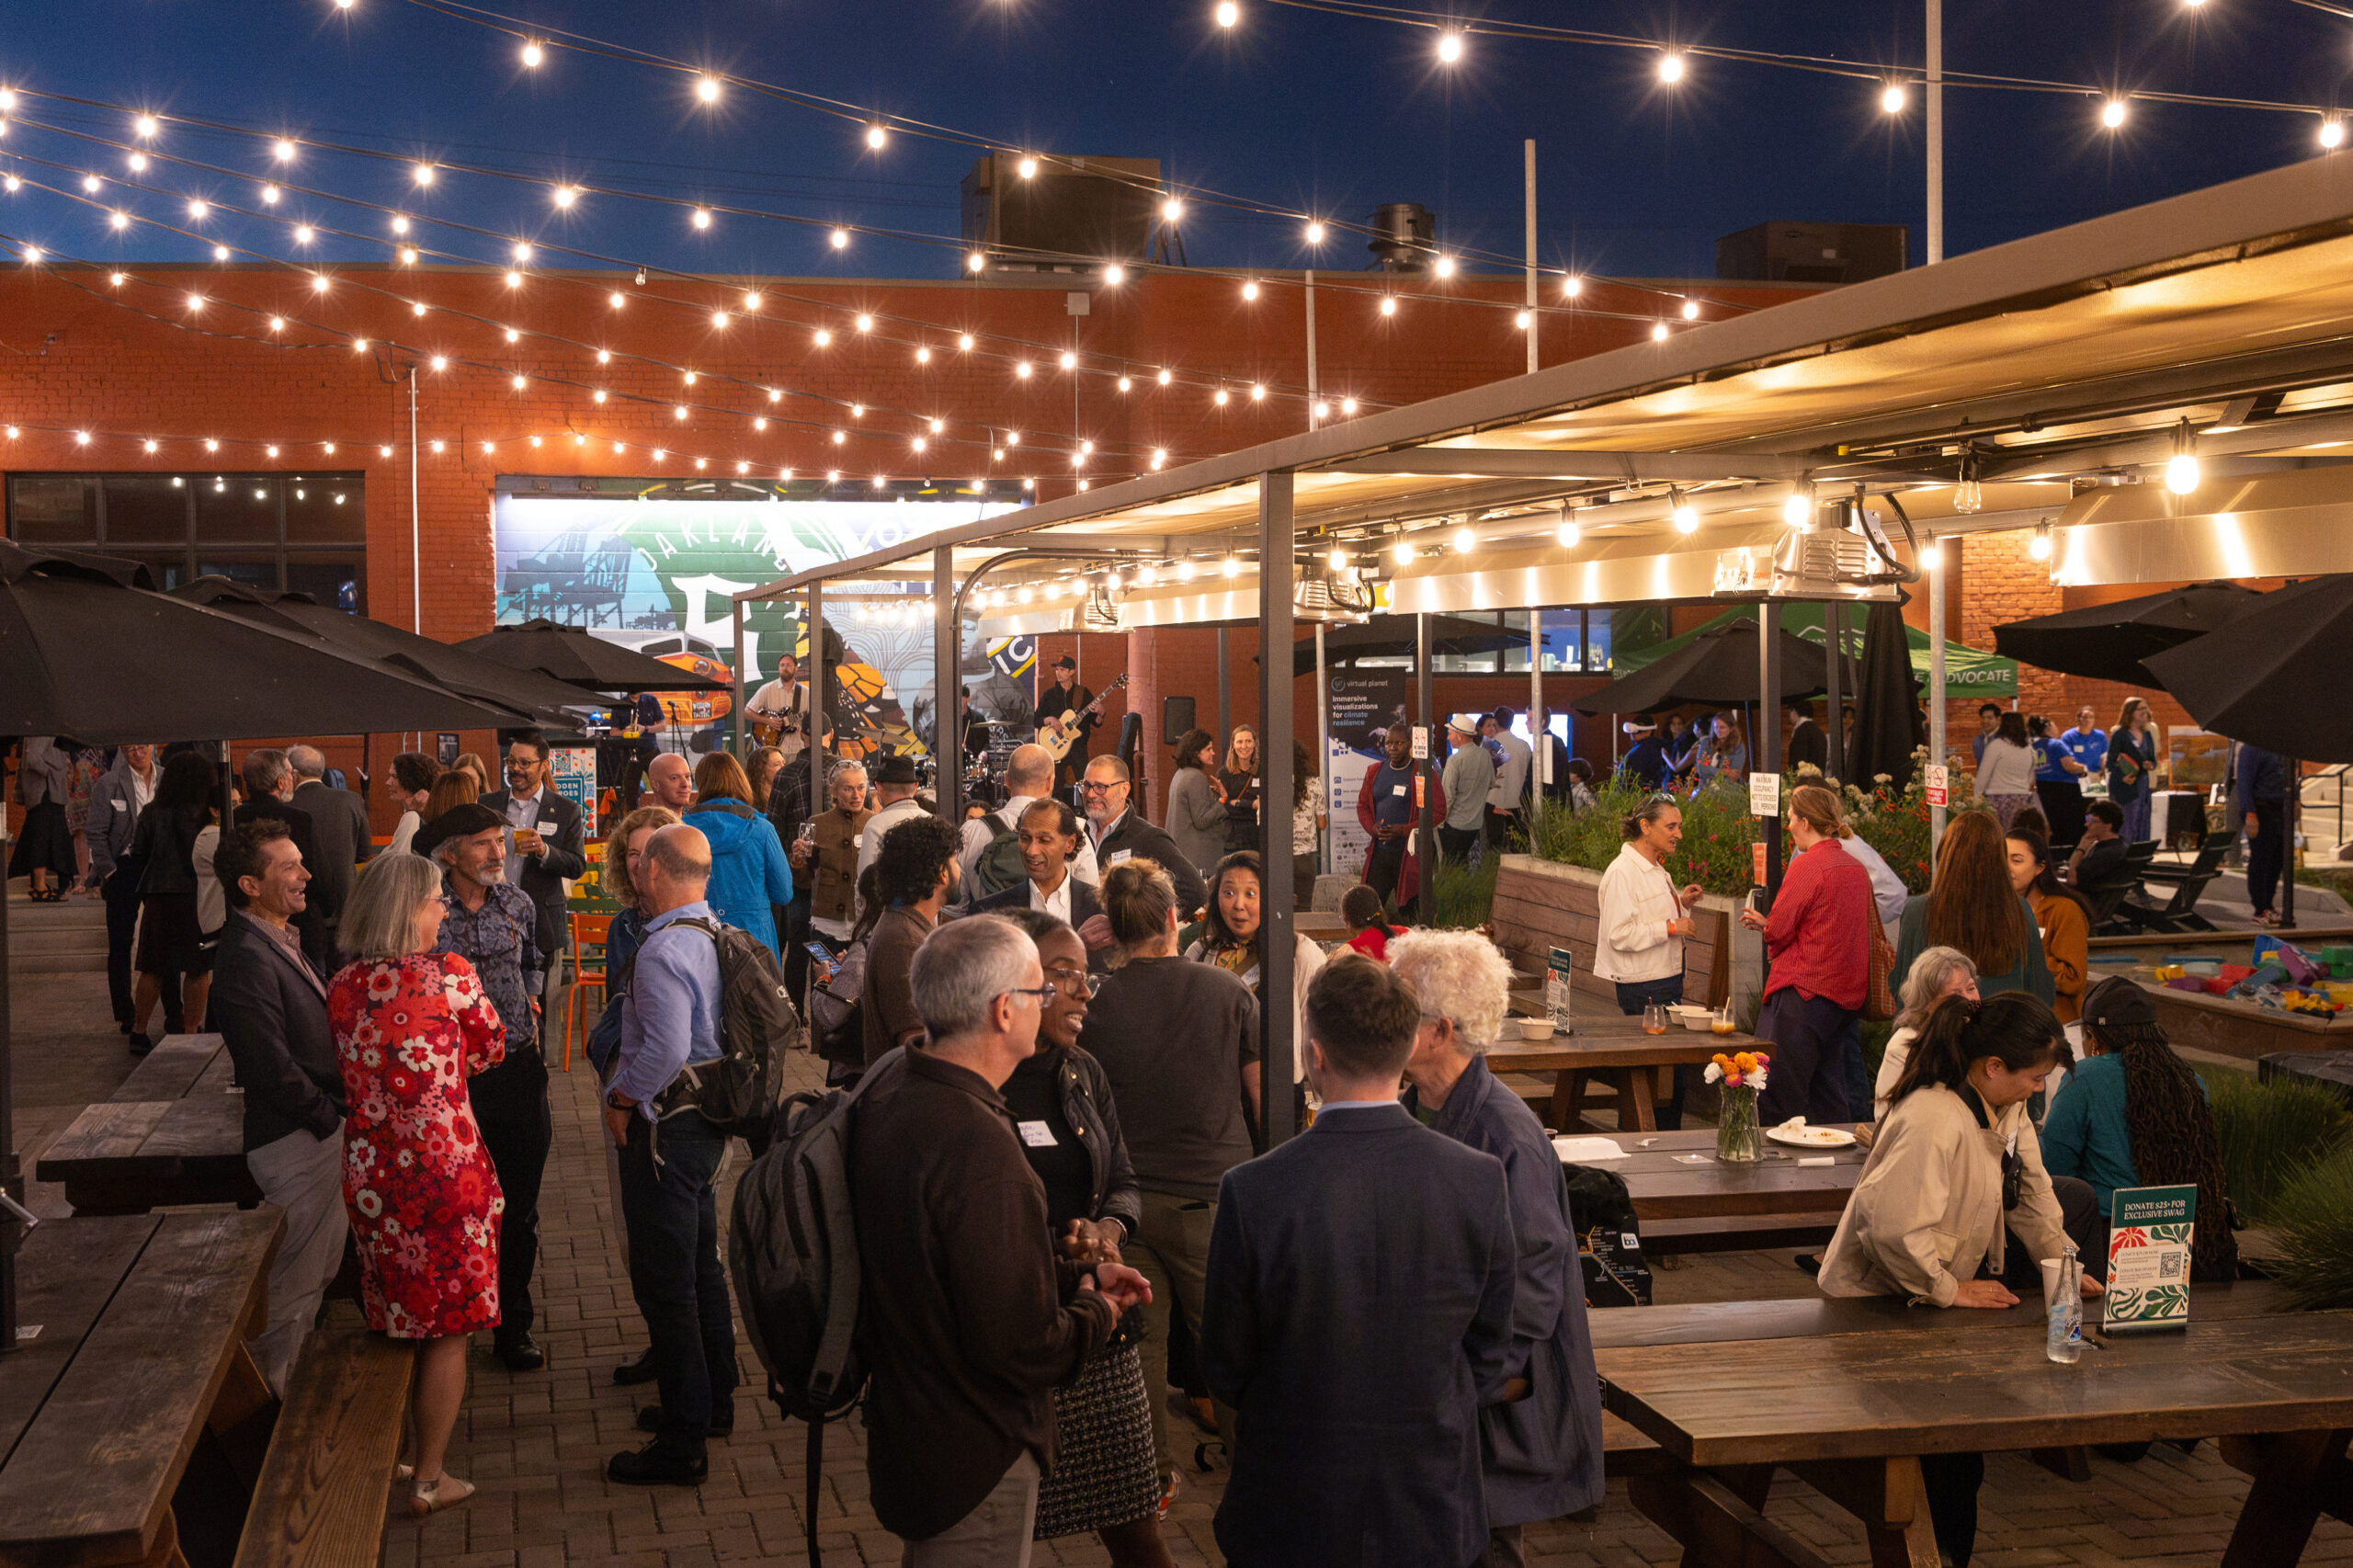
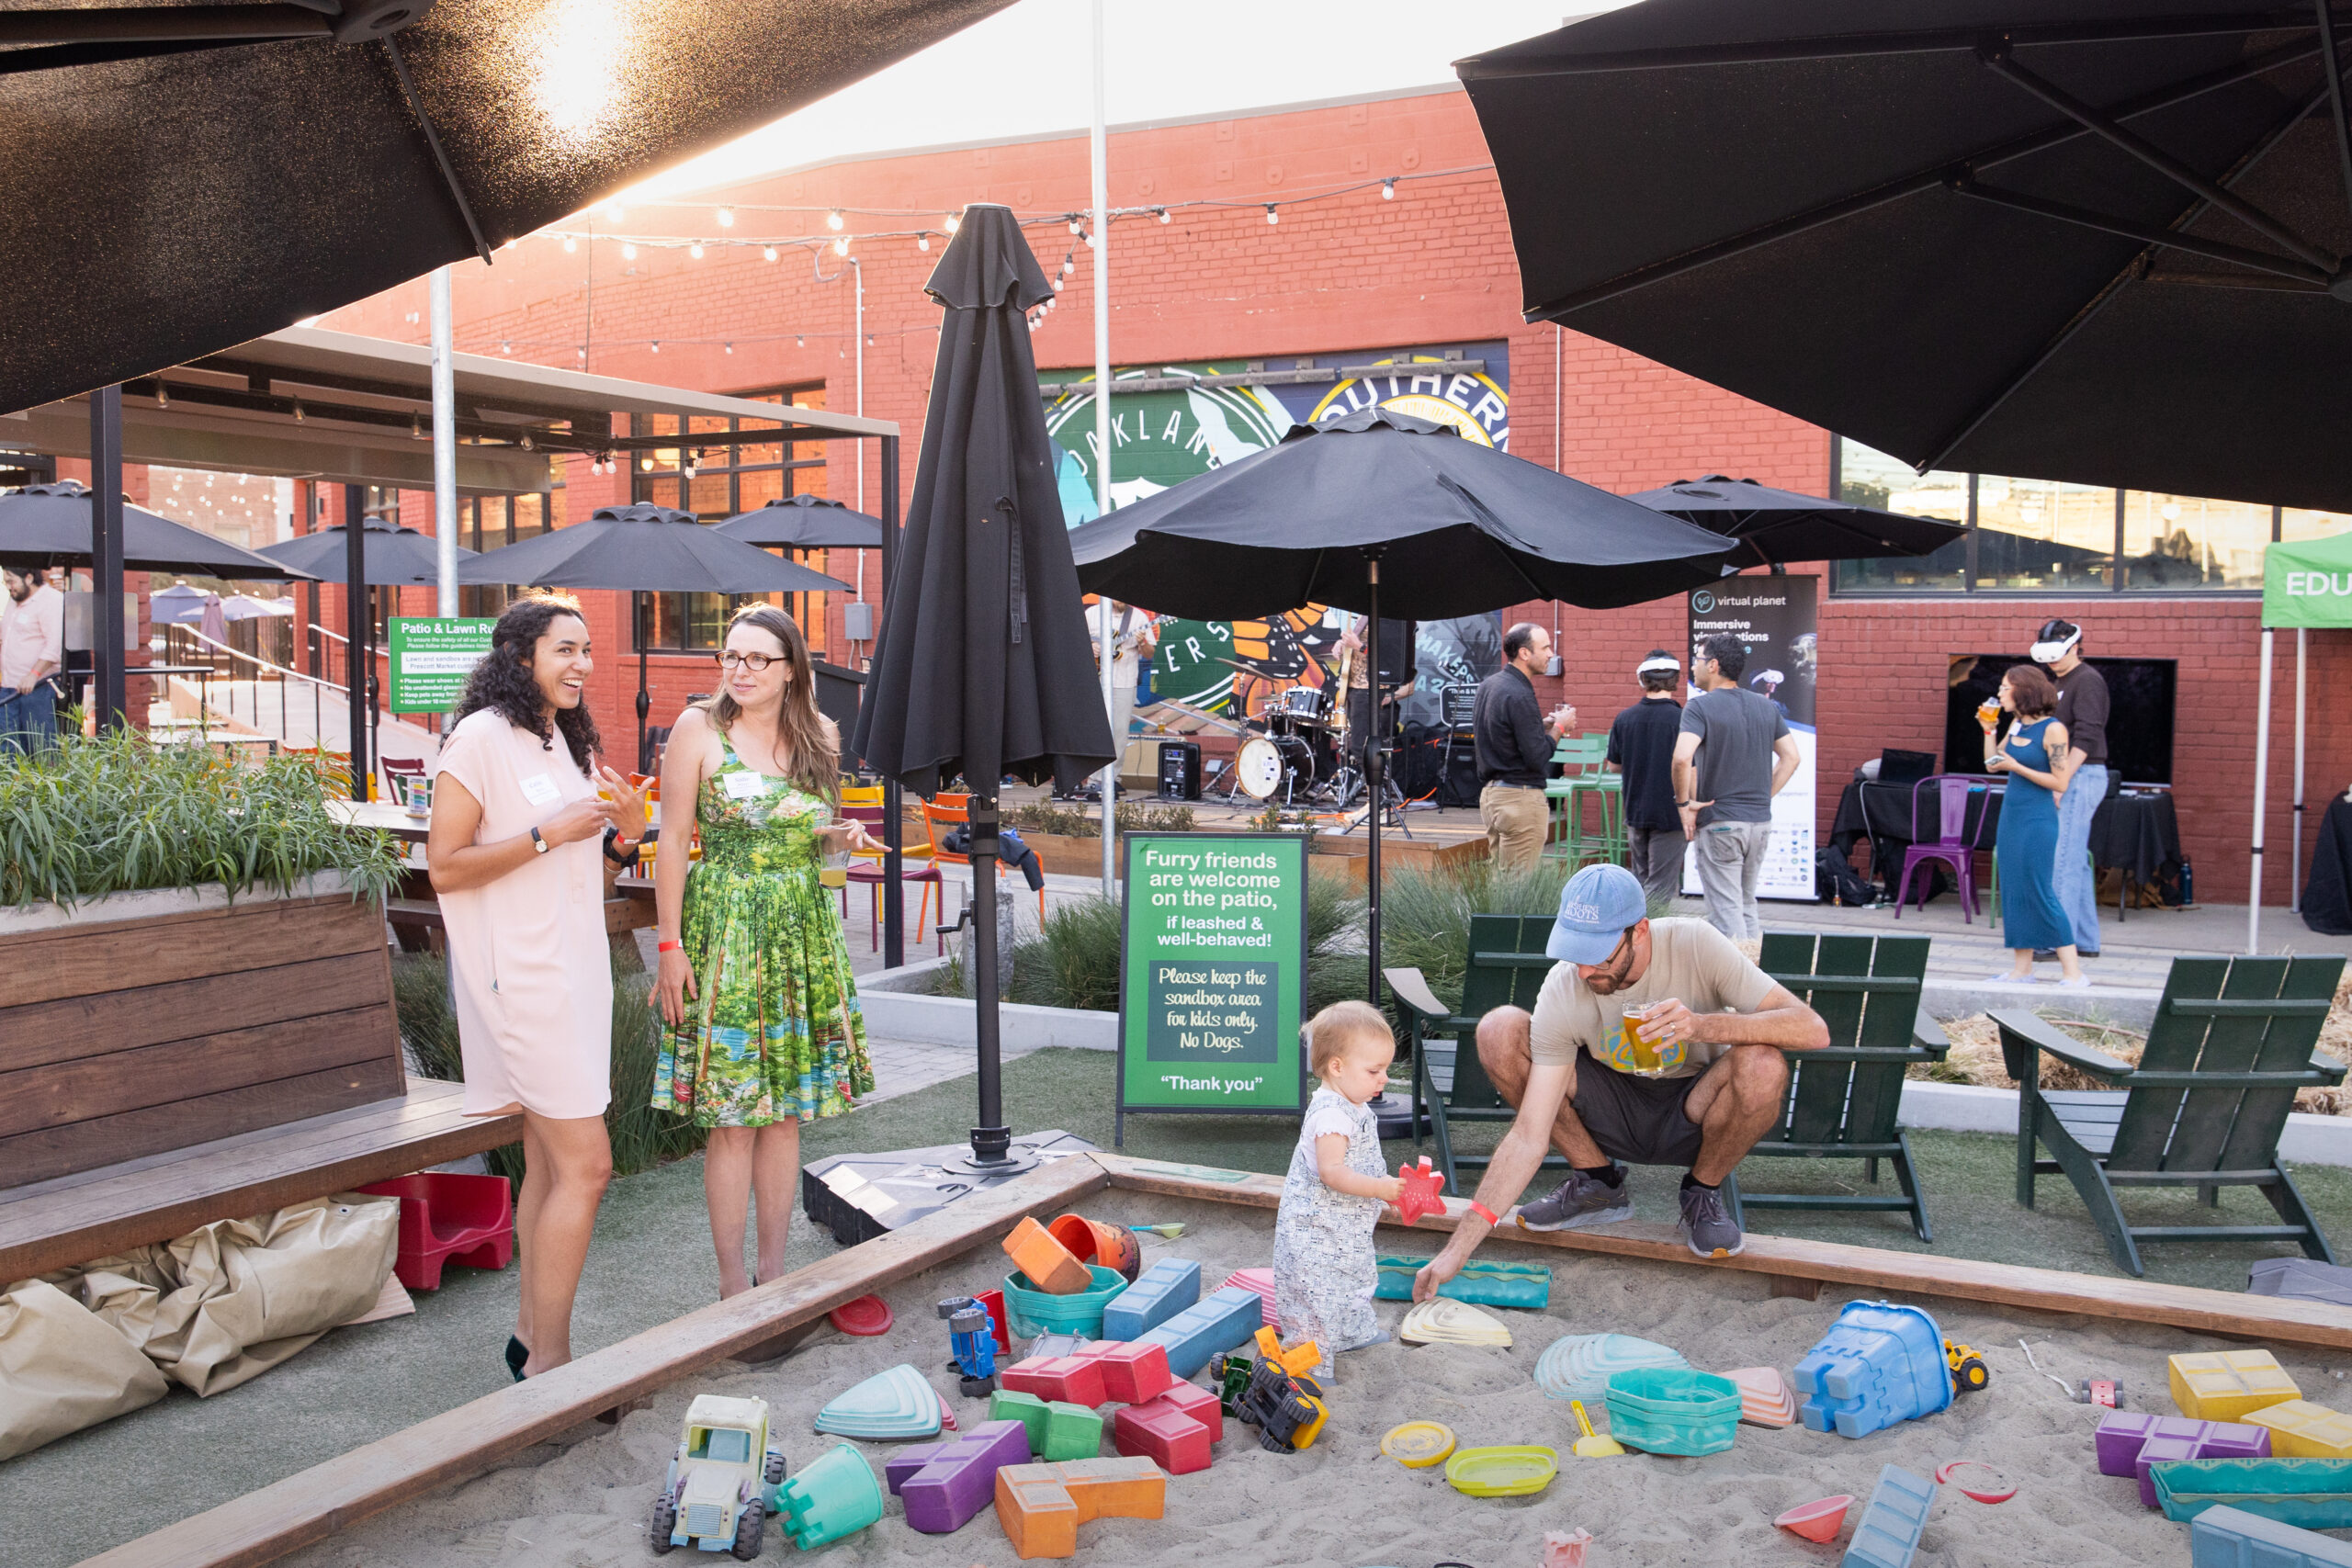
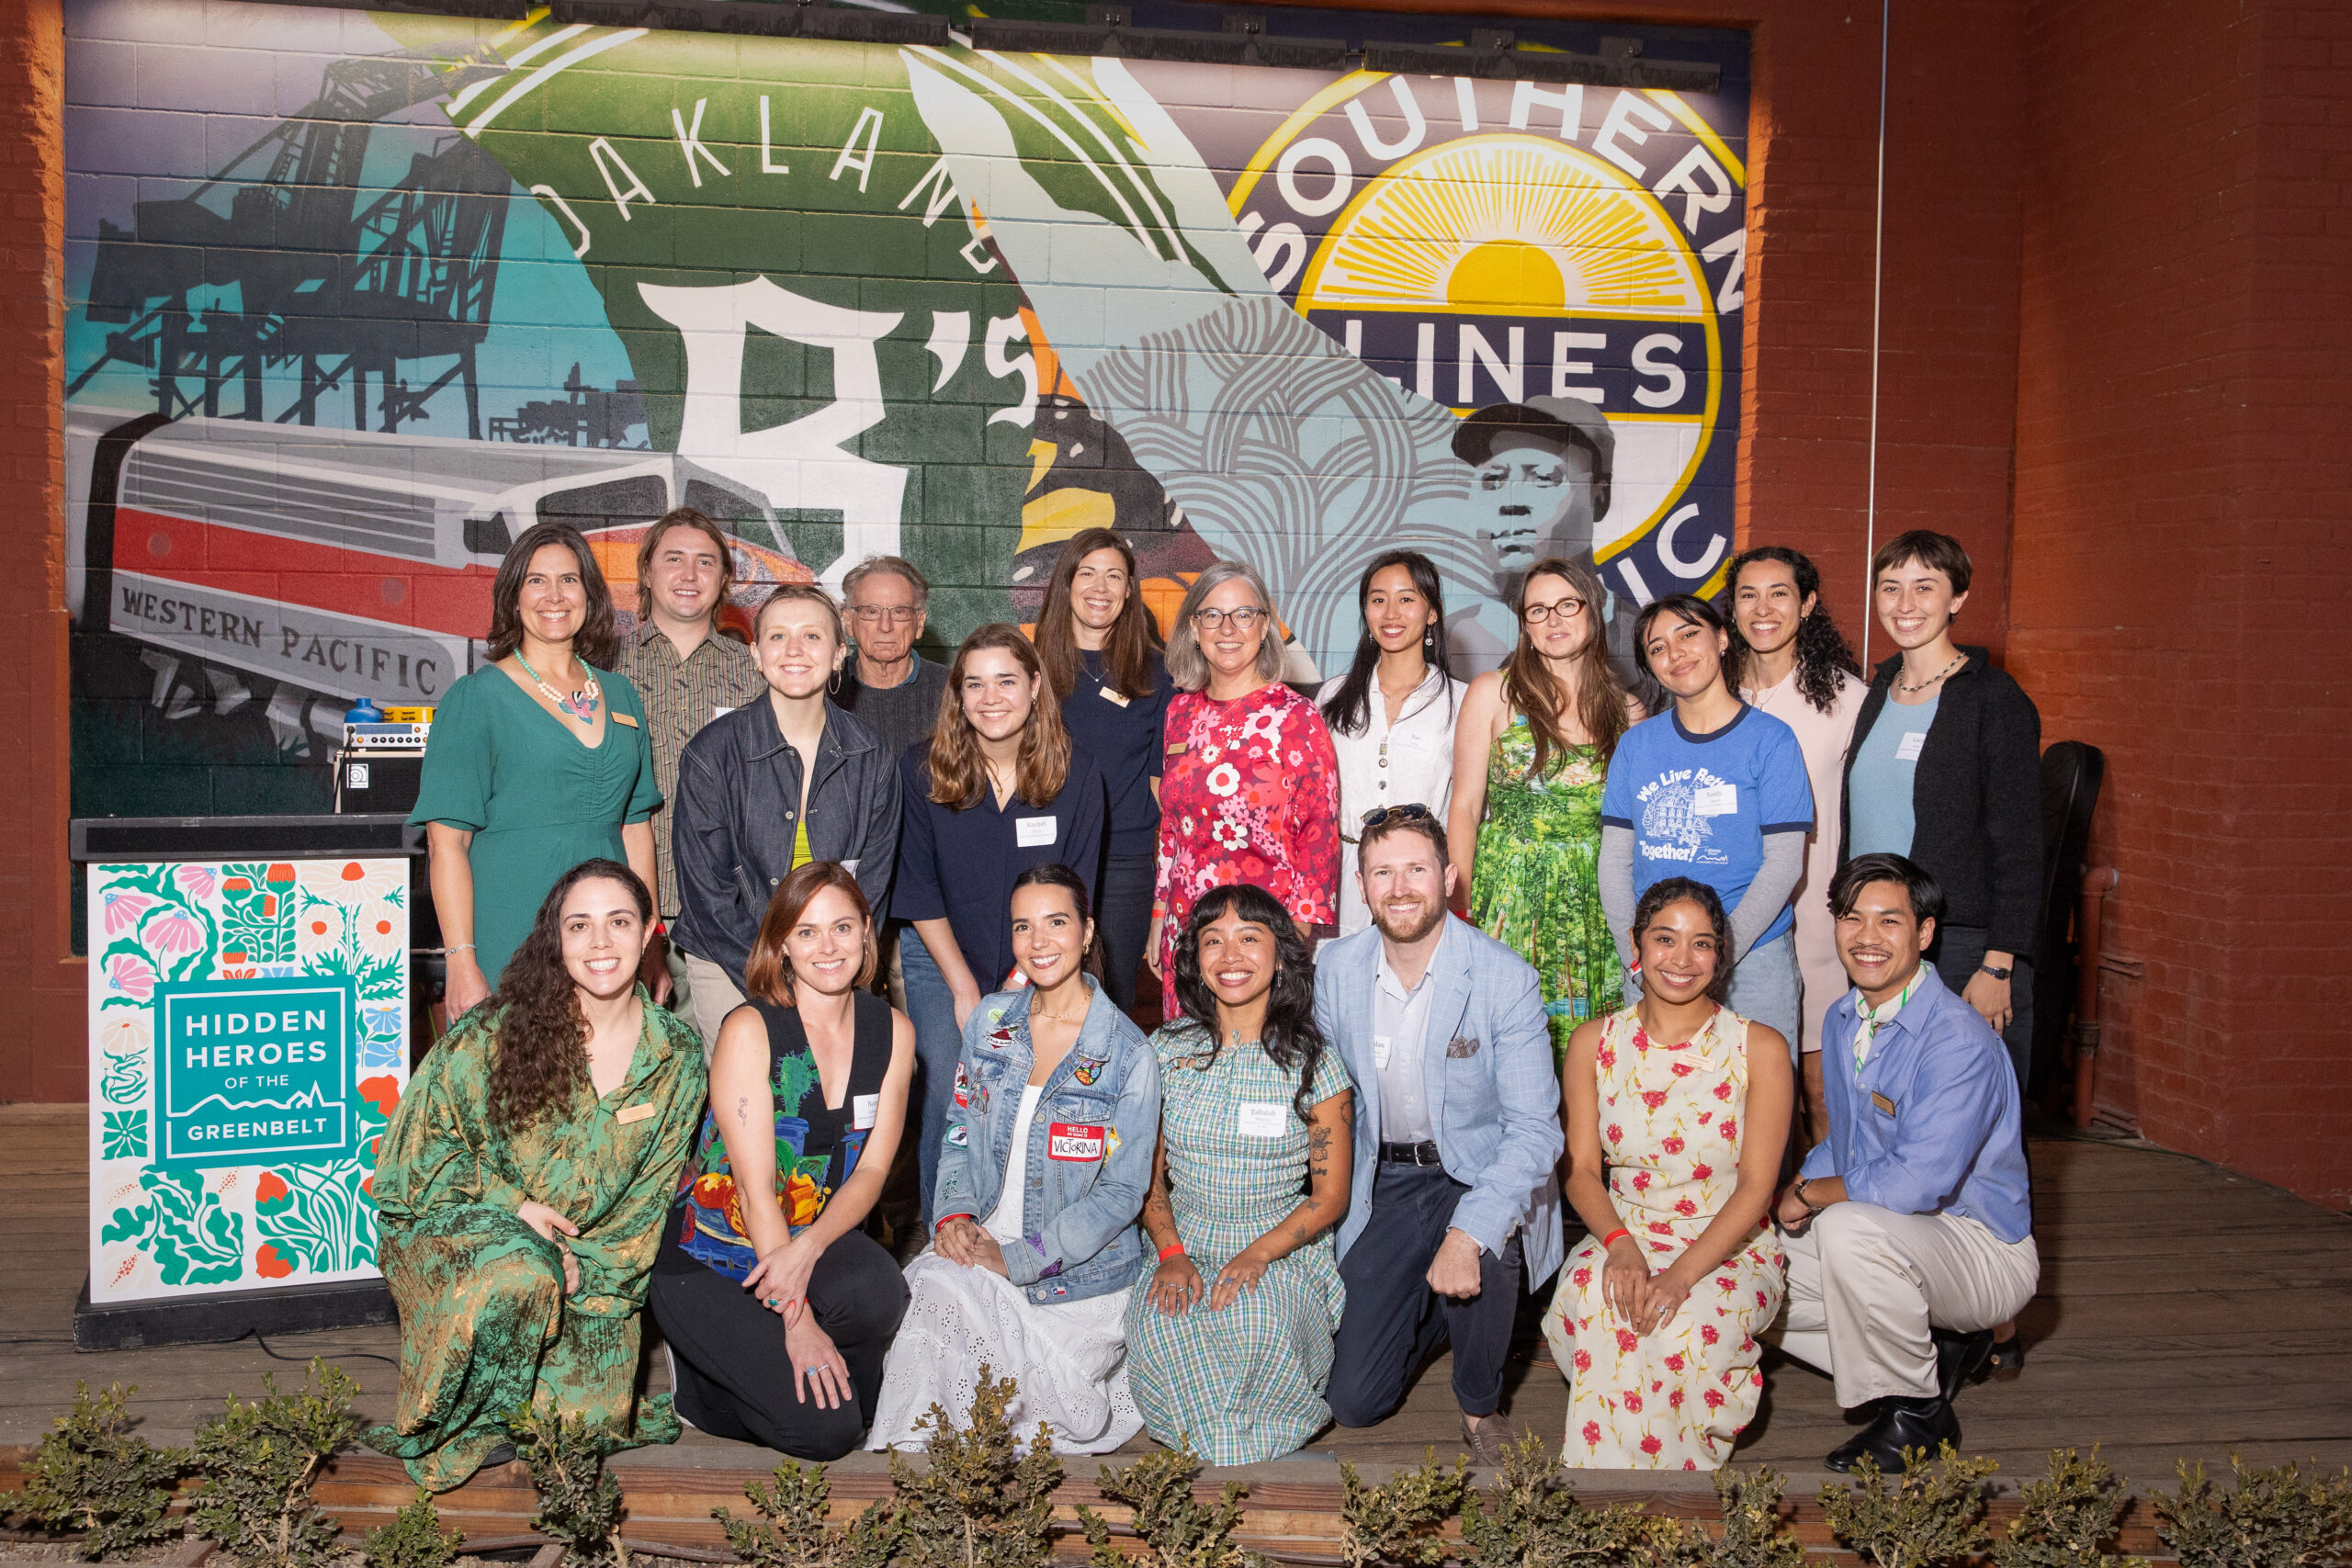
On September 23, more than 200 people came together at Prescott Market in West Oakland for the 6th Annual Hidden Heroes of the Greenbelt Benefit and Awards, an evening celebrating the people working tirelessly behind the scenes to make our Bay Area communities more resilient to climate change.
Relive the highlights of the evening CHECK OUT THE FULL ALBUM A Celebration of CommunityHidden Heroes is about more than the people we honor. It’s a gathering for everyone who believes this work matters: neighbors, advocates, funders, and friends who show up year after year because they know the Bay Area’s future depends on people like this.
Throughout the evening, guests explored virtual reality experiences from Virtual Planet and connected with our tabling partners Hood Planning, Watershed Project, and REAP Climate Center. We’re proud to work alongside organizations like these to advance our shared mission across the region.
We’re also incredibly grateful to the 35 sponsors who helped make this celebration possible and raised funds to advance our mission-driven work.
Support goes far beyond one evening. It helps us continue the work of protecting our region’s open spaces, advancing climate resilience, and building a Bay Area where people and nature can thrive together. You can contribute today to accelerating our mission-driven work. Donate here.
To every sponsor, guest, partner, volunteer, and supporter who helped make the night happen: Thank you.
Championing HopeLocal government workers rarely receive public recognition, yet their work directly shapes how millions of Bay Area residents experience climate impacts and housing security. From county-wide plans to tackle flooding from sea level and groundwater rise to infrastructure conversion to provide housing for vulnerable populations, these leaders are spearheading the plans and initiatives that protect millions of people in the Bay Area from the impacts of the combined climate and housing crises.
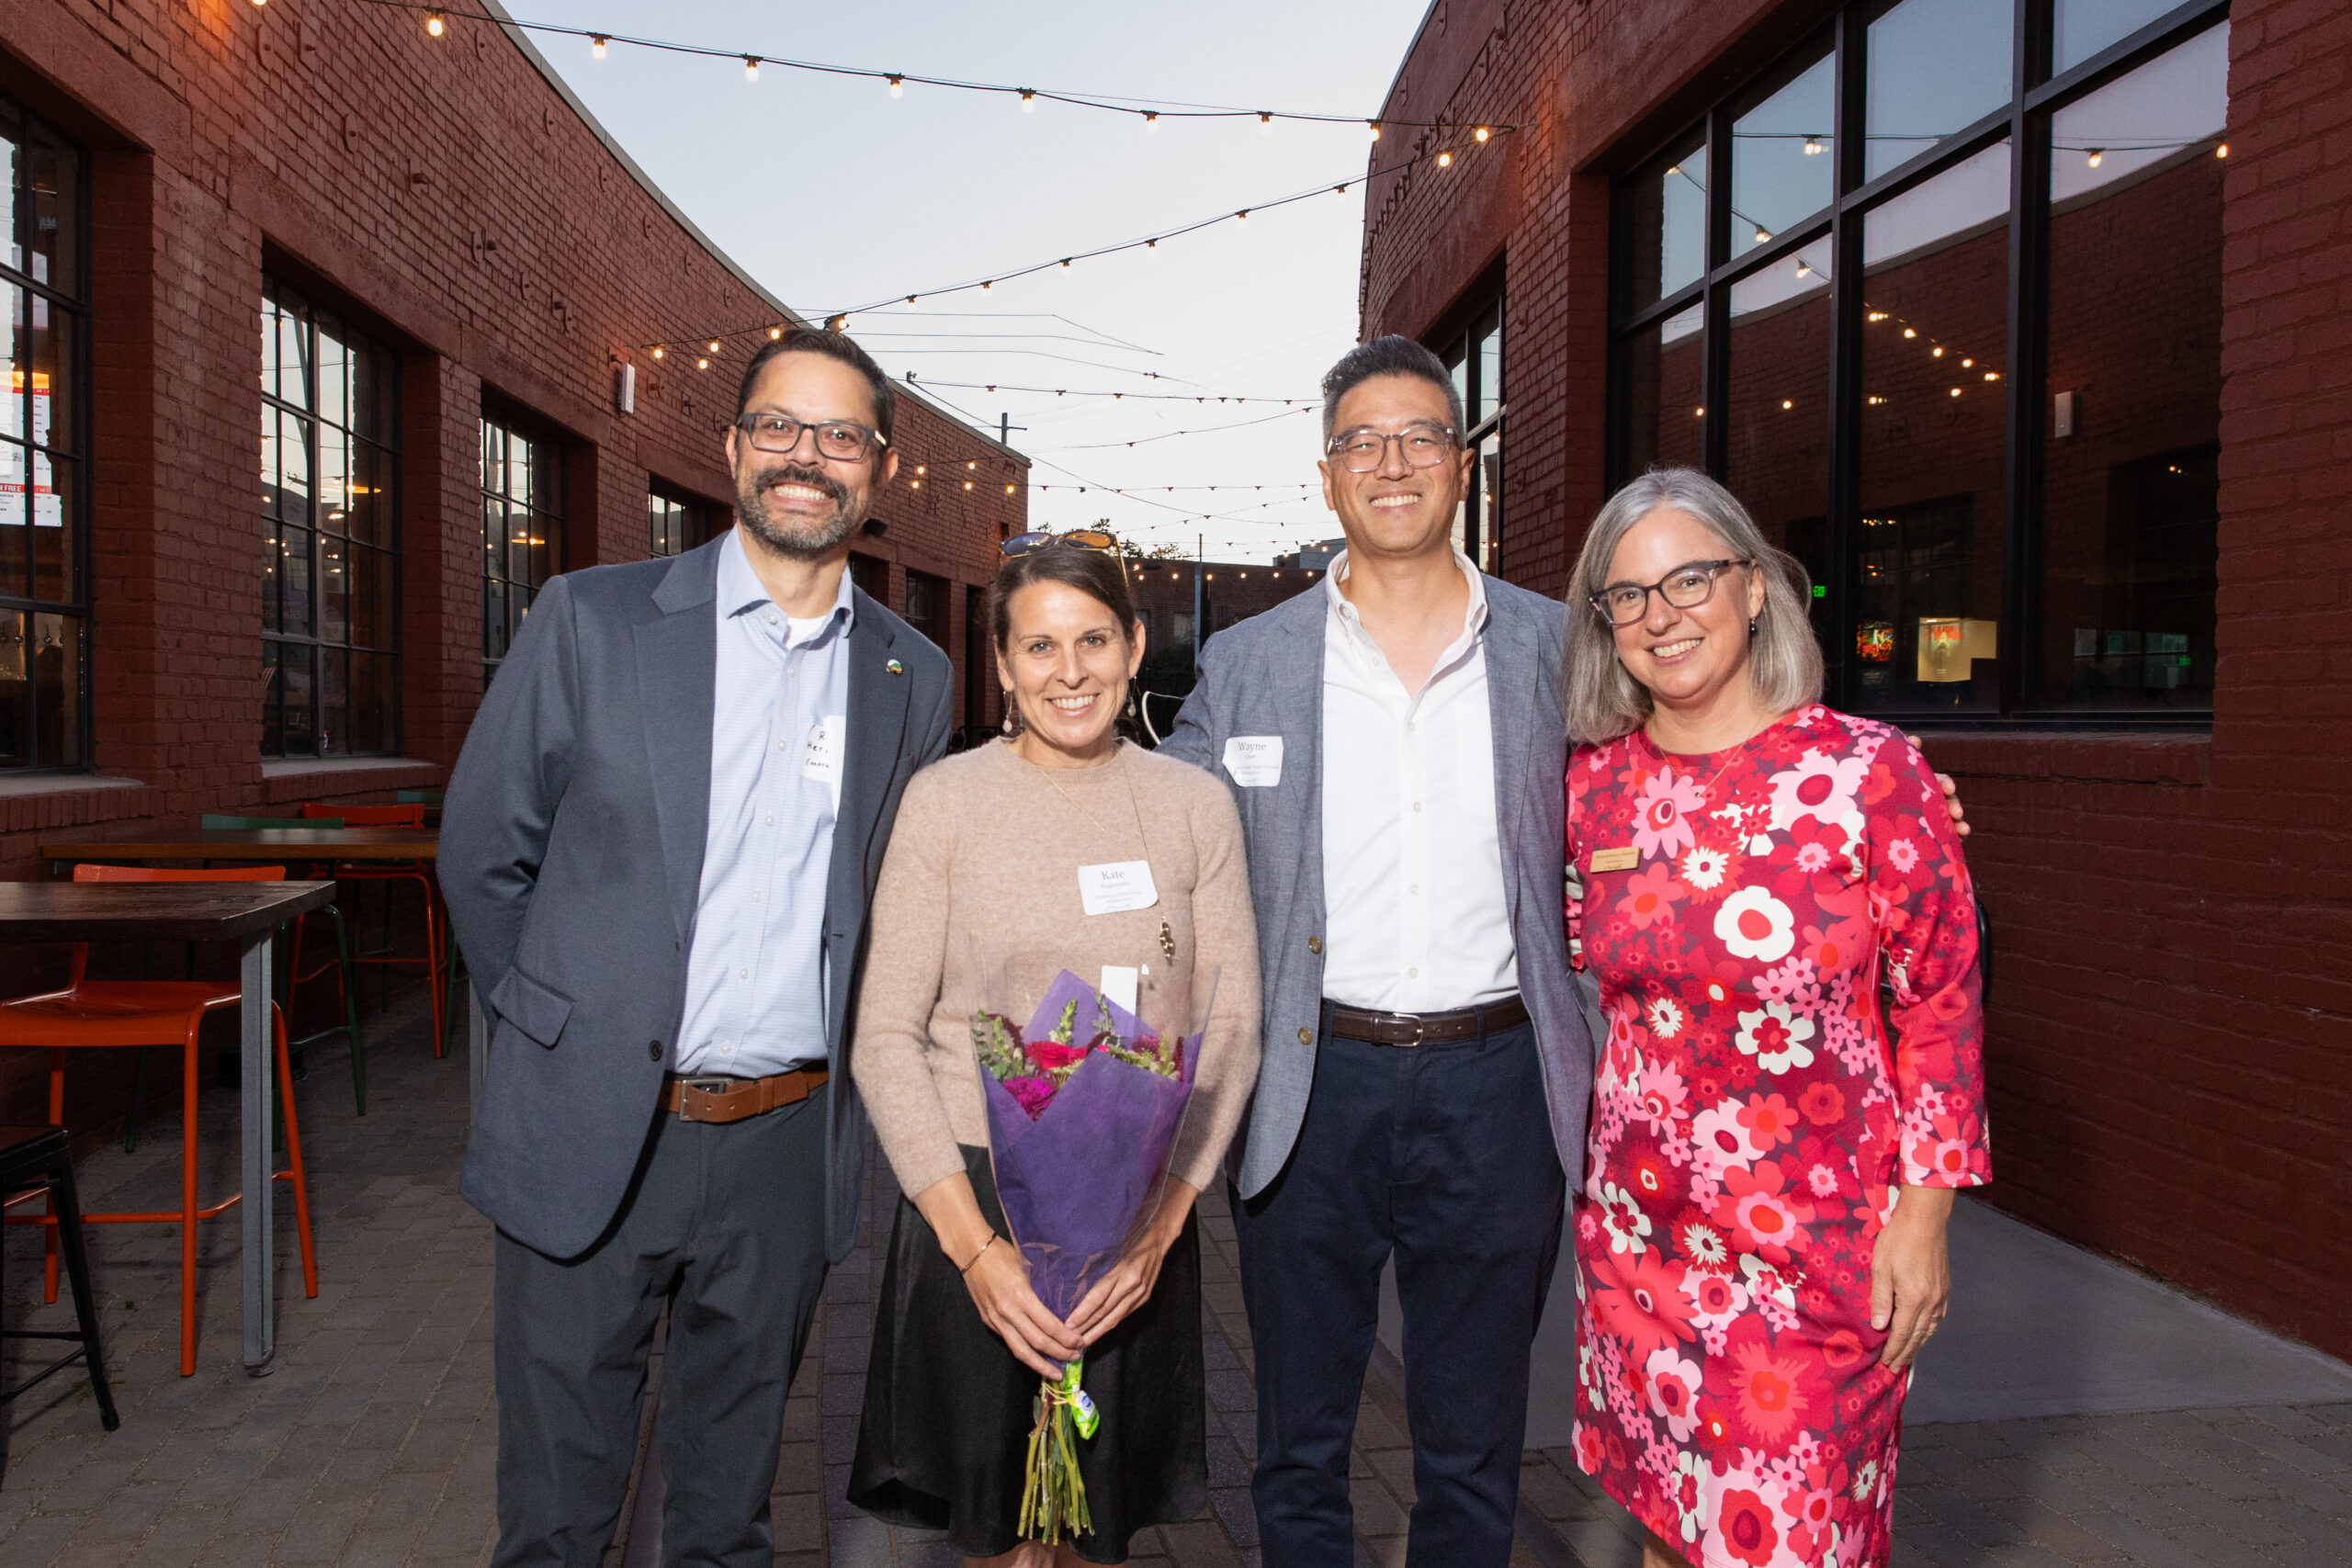
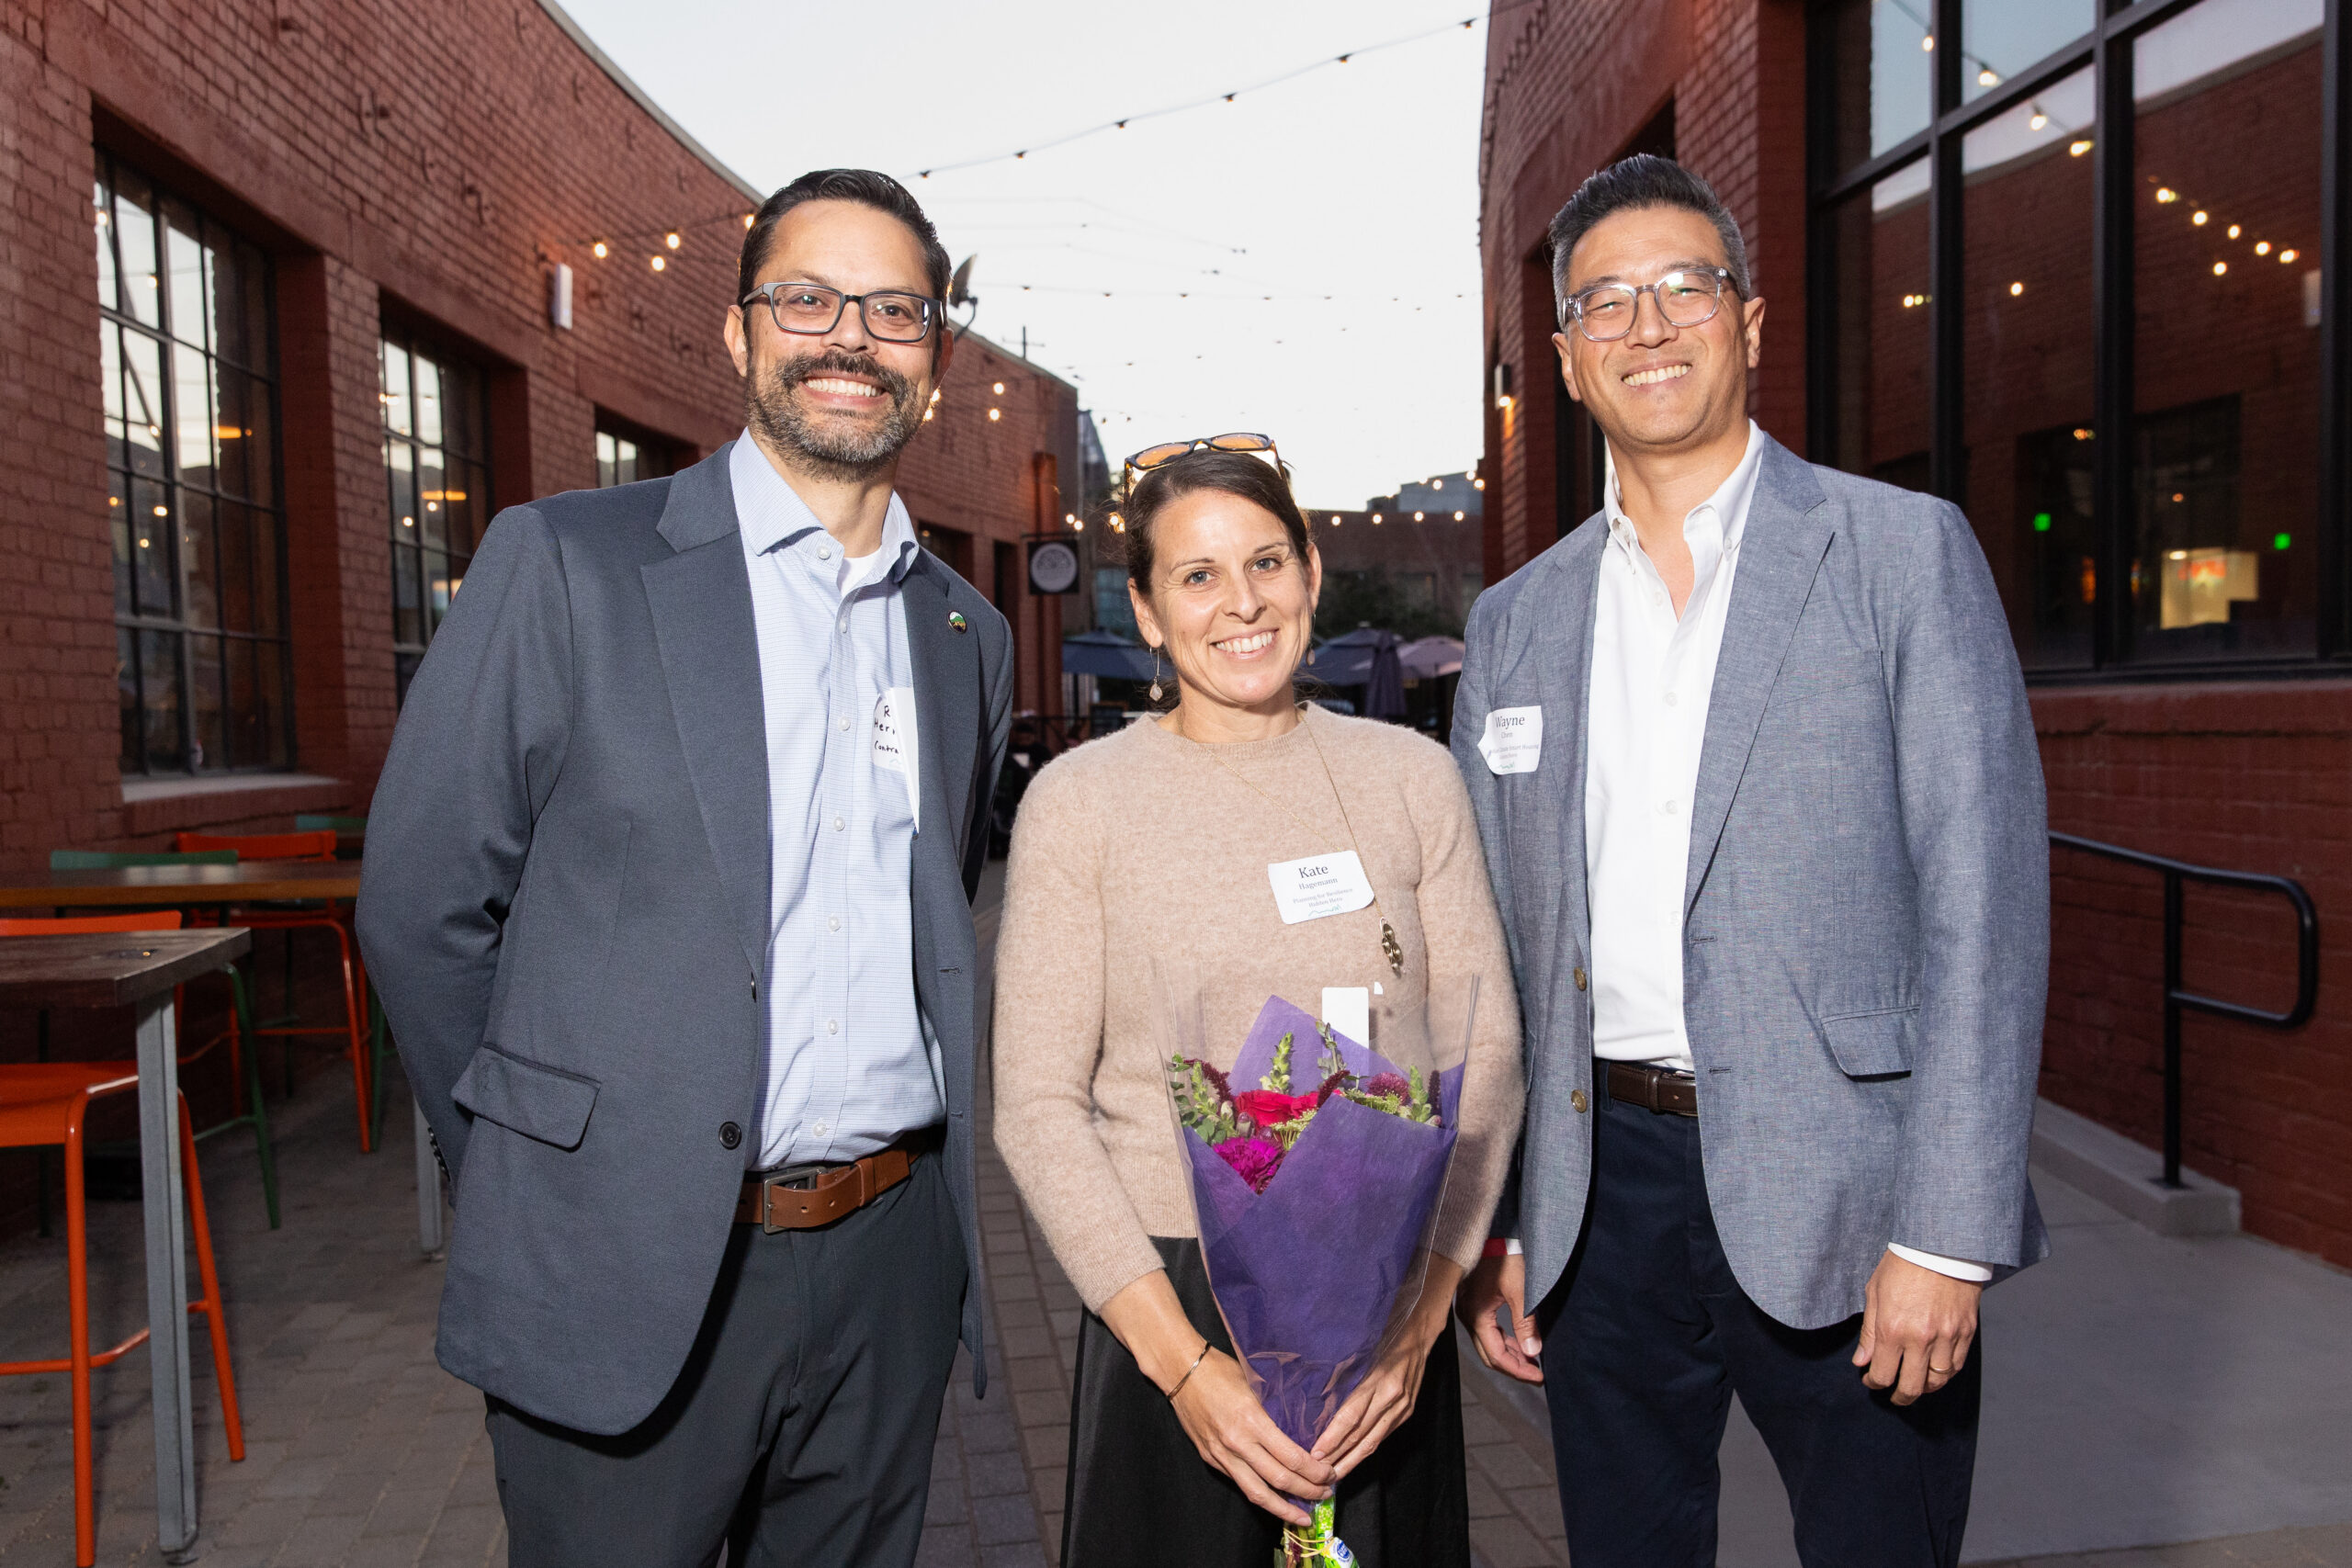
This year, we celebrated three outstanding local government leaders for pioneering solutions at the intersection of climate resilience and land use:
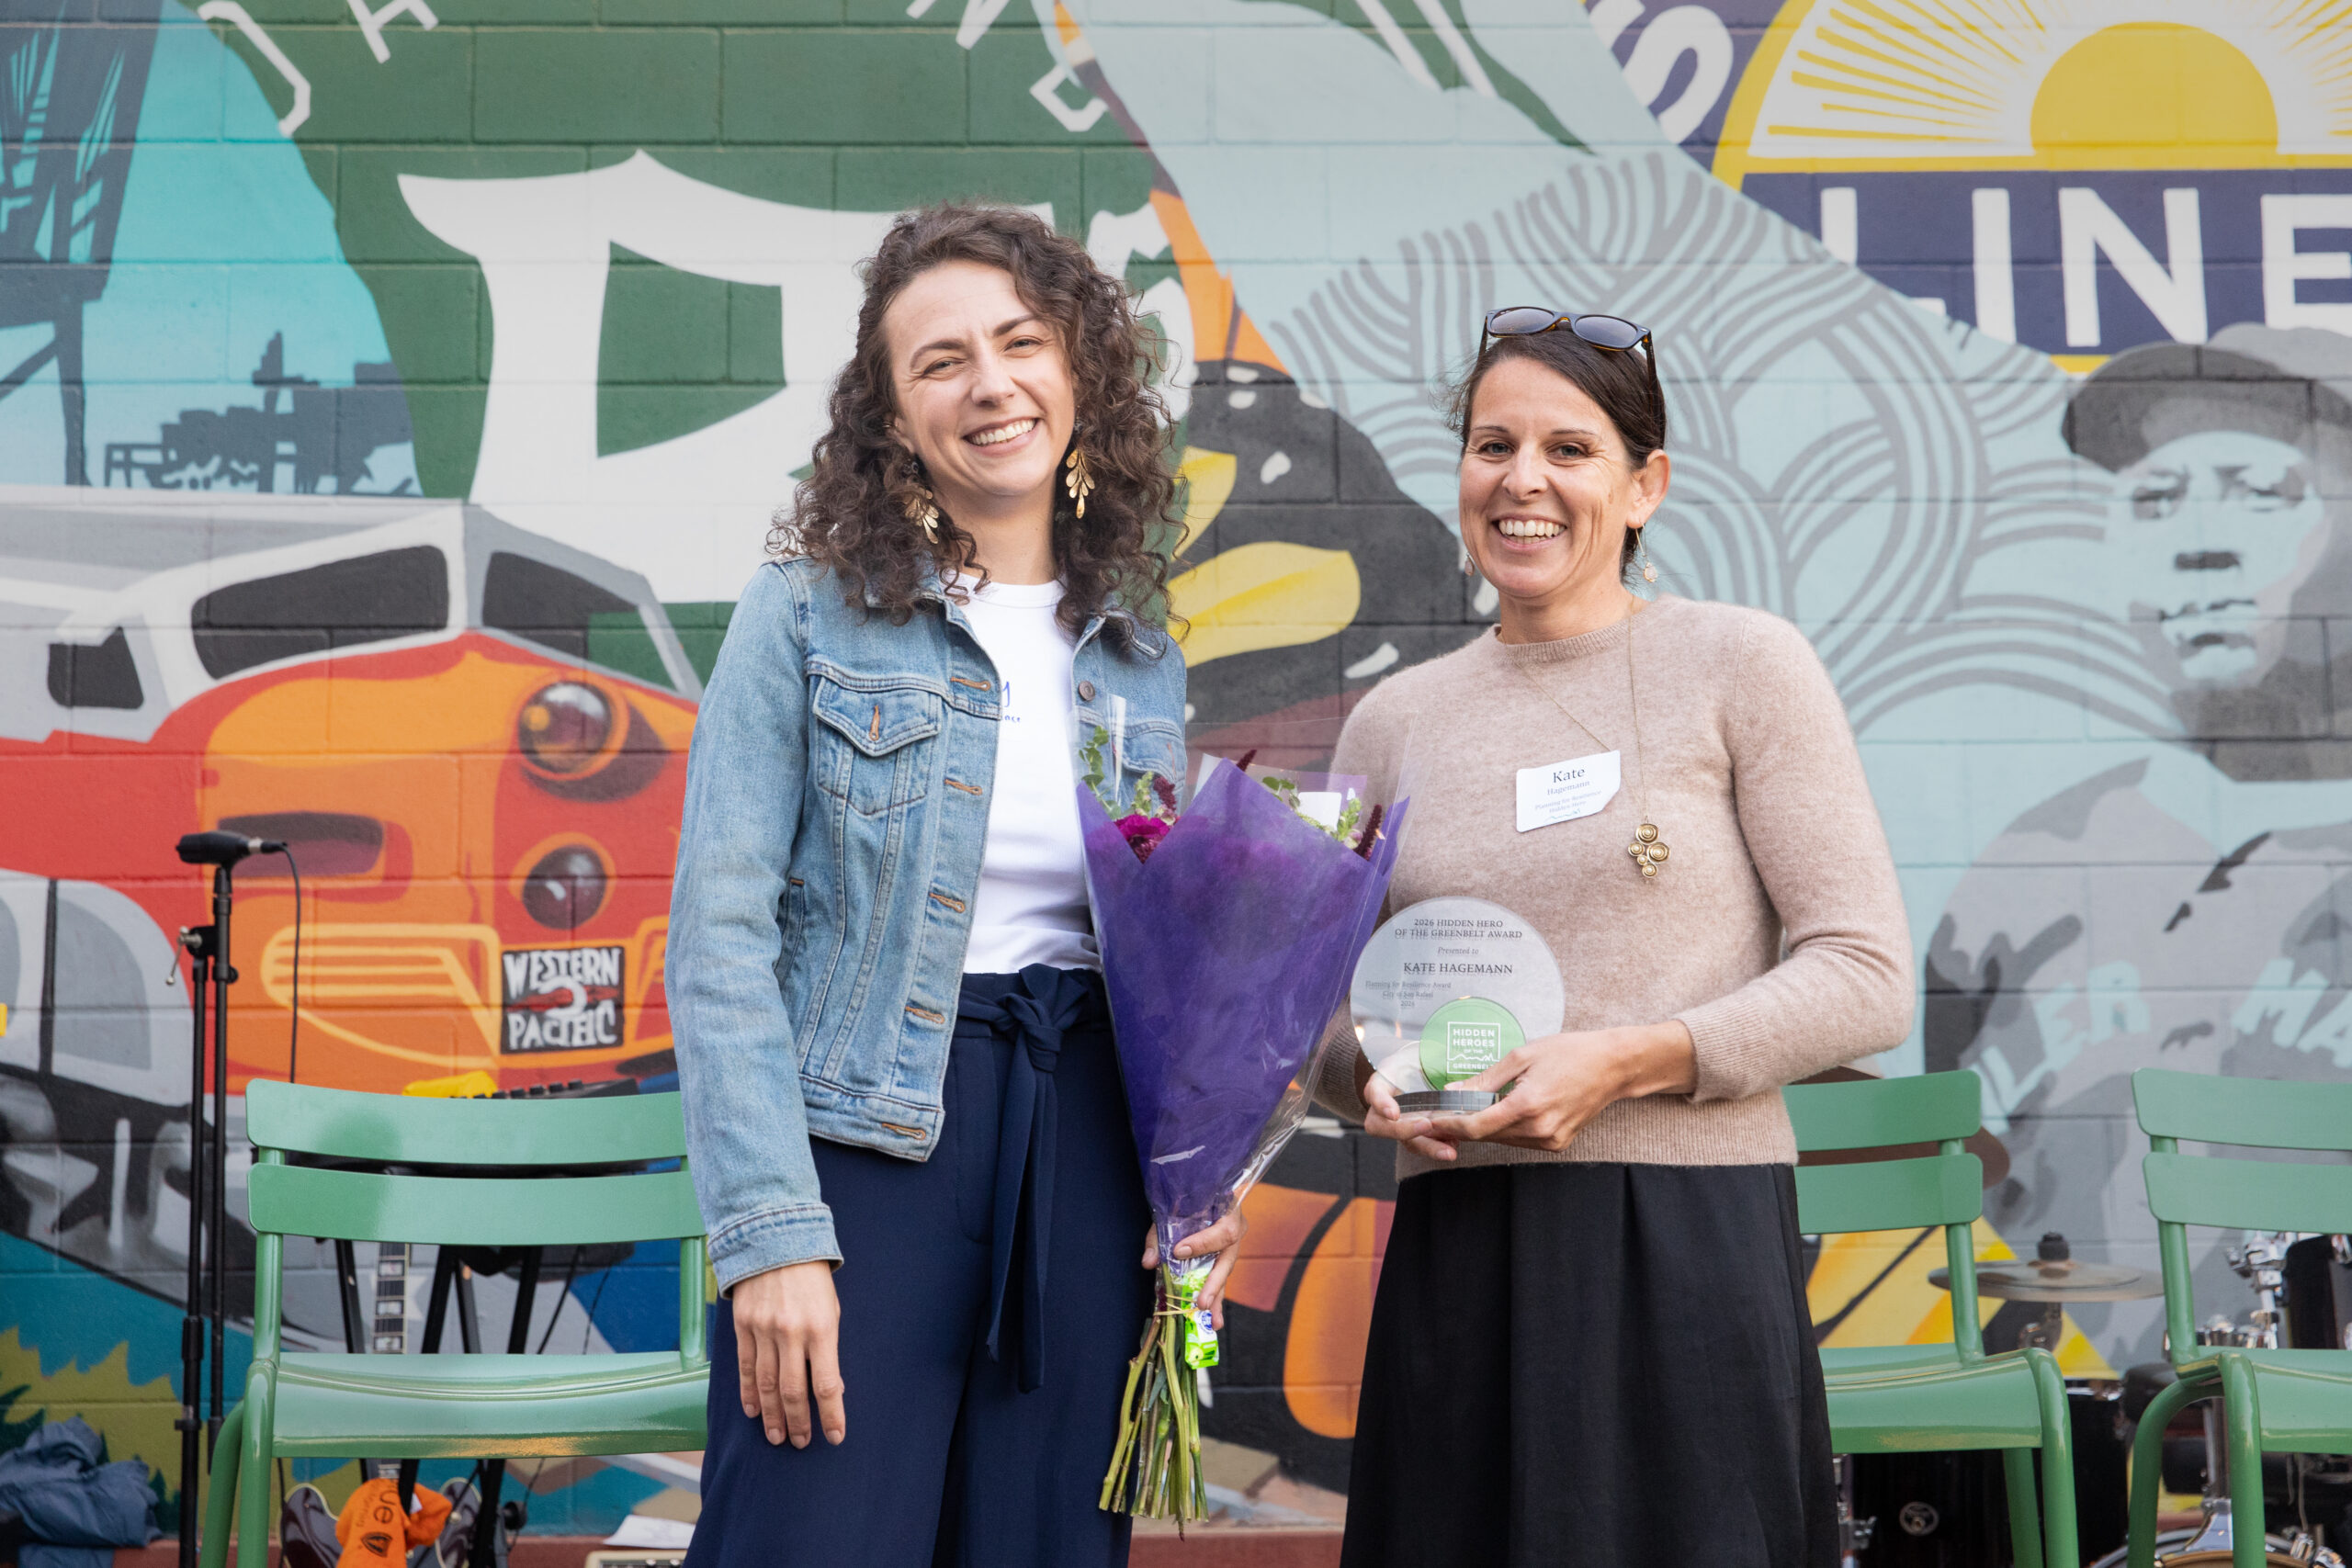
Kate HagemannClimate Adaptation and Resilience Planner, City of San Rafael
Kate was honored for her work advancing climate change resilience and adaptation planning, helping communities prepare for the challenges of a changing climate.
Wayne ChenDirector of Housing Department,
City of Mountain View
Wayne was recognized for his work promoting climate-smart housing and demonstrating how housing and climate resilience can be part of the same conversation.
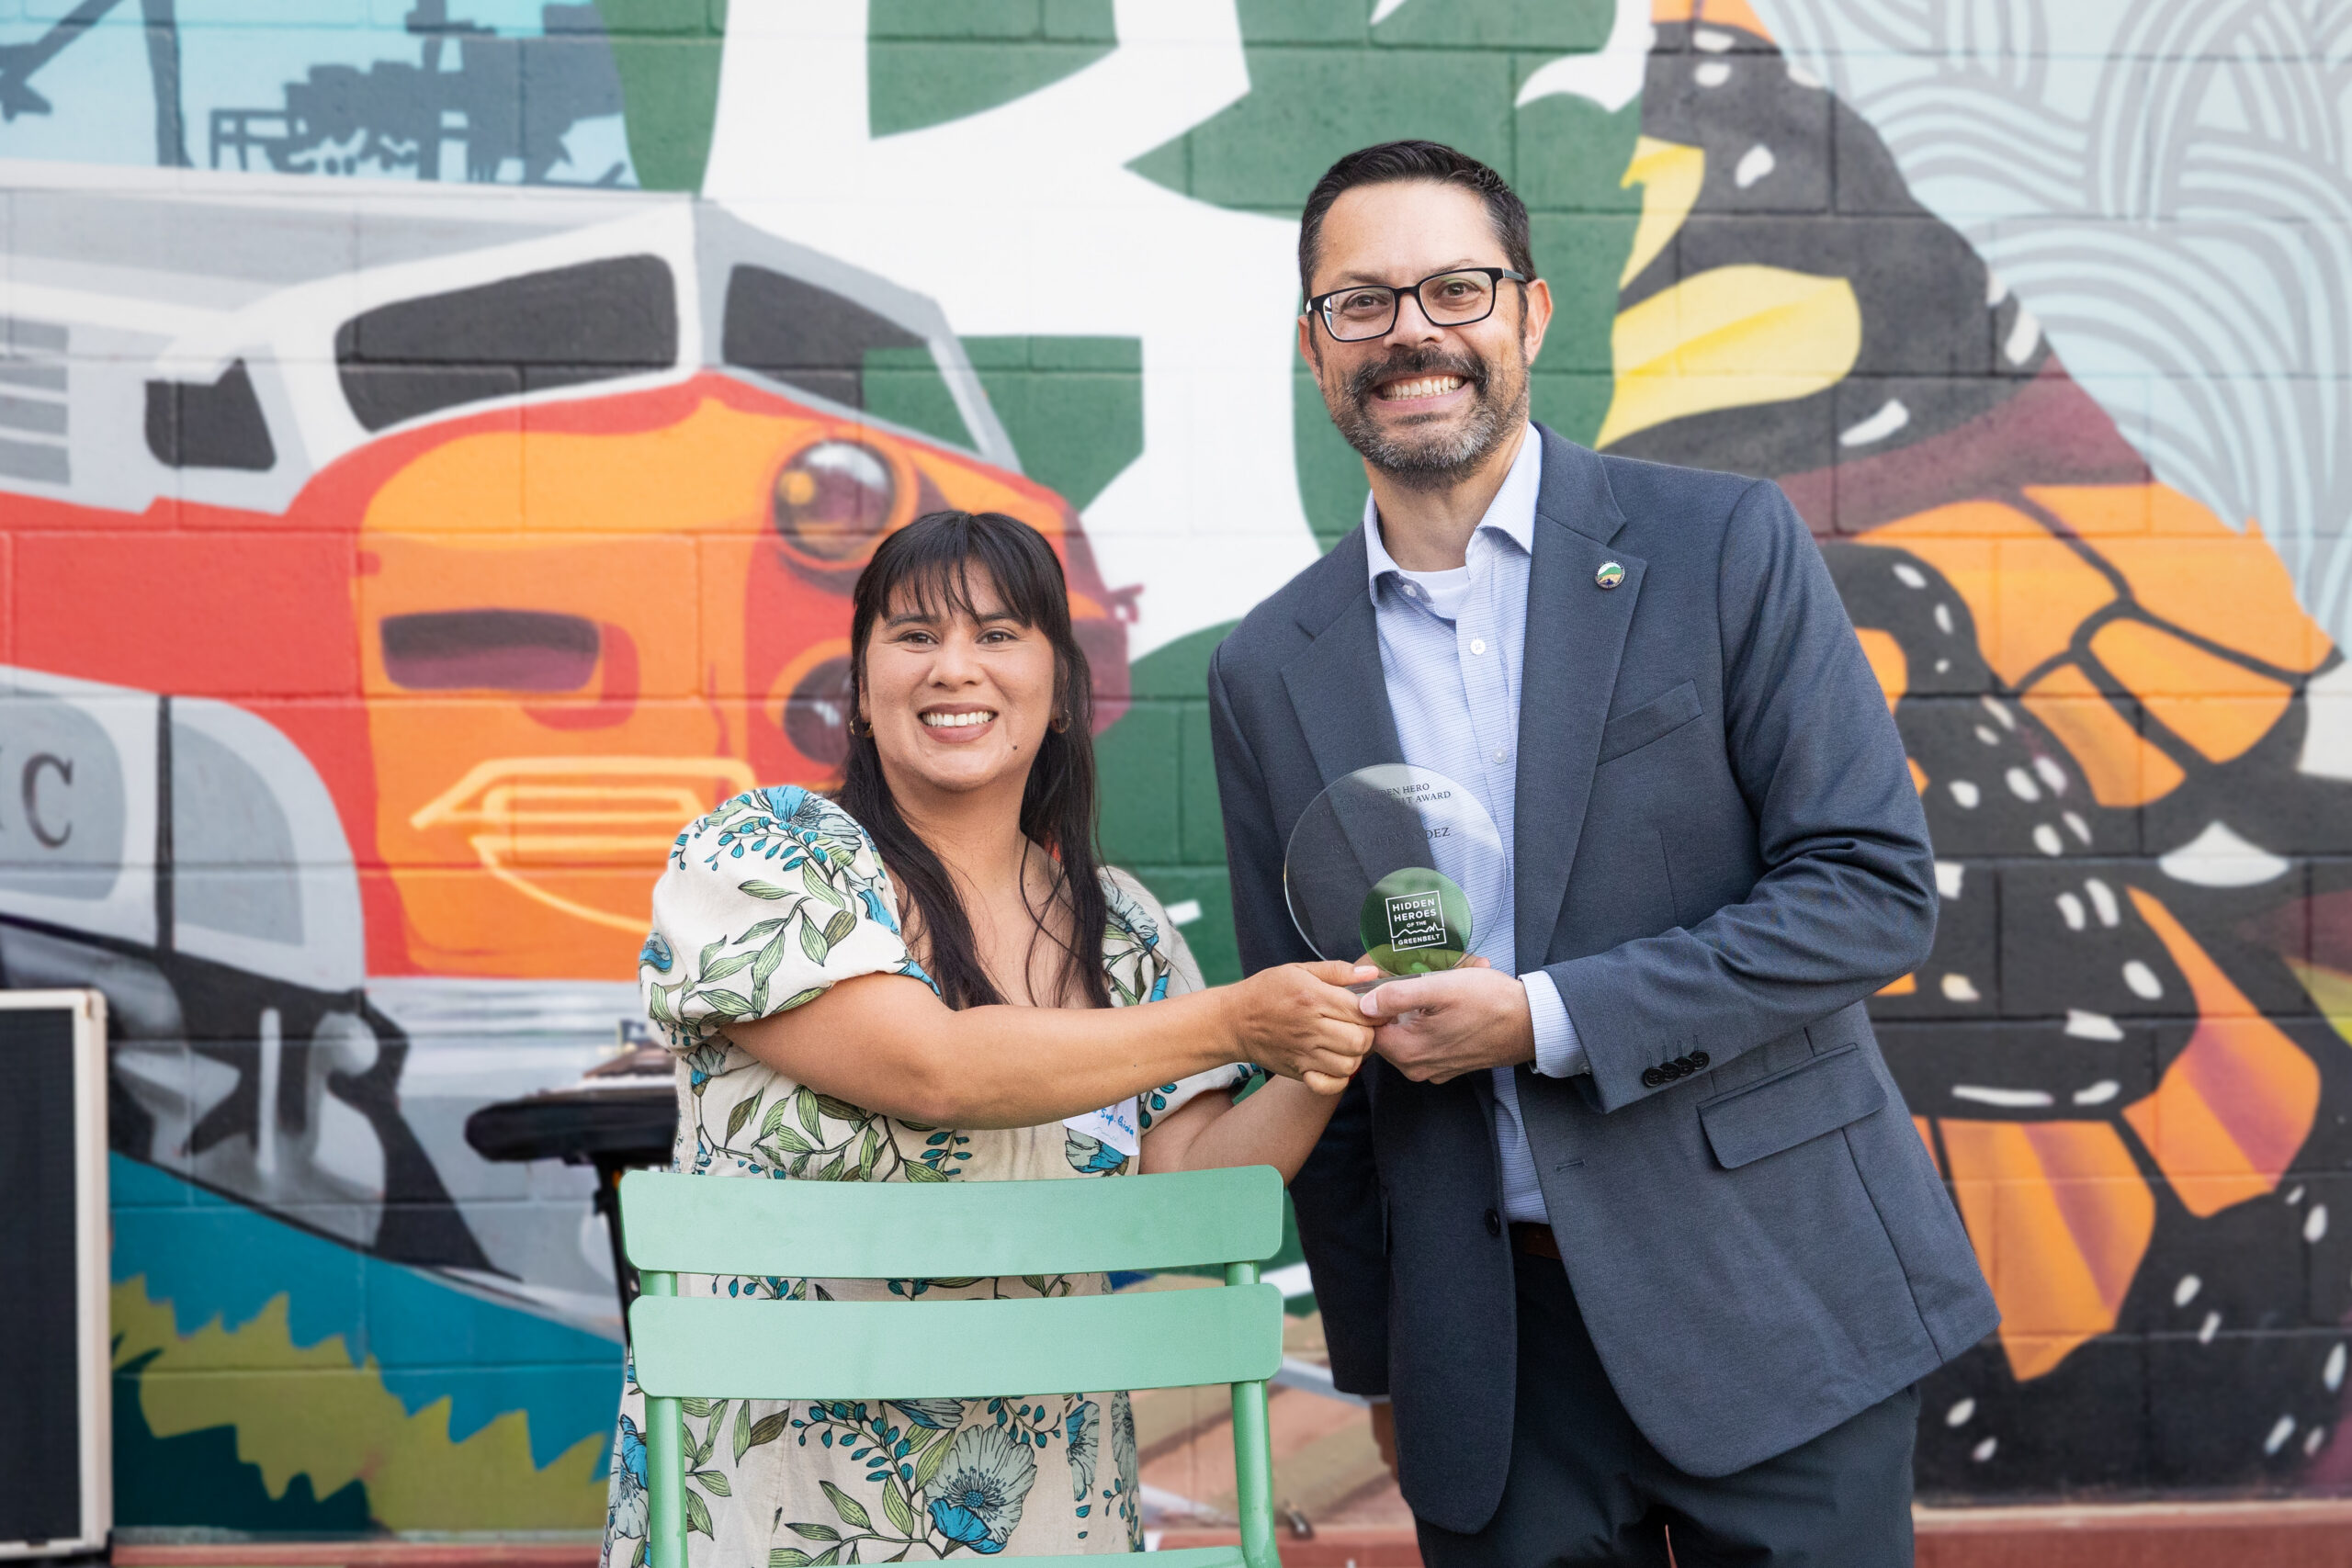
Ryan HernandezAssistant Deputy Director,
Contra Costa County
Ryan was honored for his work advancing nature-based climate adaptation, showing how nature itself can be an important part of how communities respond to a changing climate.
Some evenings stay with you. An evening with Kate, Wayne, and Rayne will do that you: leave you convinced that the Bay Area is in good hands, and those hands are busy.
The Power to Make a Difference Is LocalAt a time when we’re seeing rollbacks on the federal level, Hidden Heroes reminds us that there is still so much we can do, right here at home.
That’s what Hidden Heroes is all about: we shine a light on the people making a difference in their communities, spark curiosity and action elsewhere, and prove that local action matters, especially when the work ahead is urgent.
Thank you for celebrating with us, supporting our mission, and being part of a community that believes we can make a difference right here at home.
The work continues. And we’re in it together.
.elementor-39197 .elementor-element.elementor-element-3007a9da > .elementor-element-populated{padding:30px 0px 30px 0px;}.elementor-39197 .elementor-element.elementor-element-7b48ef7d > .elementor-widget-container{padding:0px 0px 30px 0px;}.elementor-39197 .elementor-element.elementor-element-7b48ef7d{text-align:center;}.elementor-39197 .elementor-element.elementor-element-7b48ef7d .elementor-heading-title{font-size:35px;color:var( --e-global-color-54e1dff );}.elementor-39197 .elementor-element.elementor-element-6604725c{text-align:center;}.elementor-39197 .elementor-element.elementor-element-517afbb{text-align:center;}.elementor-39197 .elementor-element.elementor-element-26d468b{text-align:center;}.elementor-39197 .elementor-element.elementor-element-96da833{text-align:center;}.elementor-39197 .elementor-element.elementor-element-b5671ce{text-align:center;} THANKS TO OUR 2026 HIDDEN HEROES SPONSORS Climate Advocate Sponsors Land Steward SponsorsEast Bay Municipal Utility District | East Bay Regional Park District | Housing Action Coalition | Marin Community Energy (MCE) | The Morley Bros | Skidmore, Owings & Merrill LLP | SPUR | Triad Development
Community Friend SponsorsAlta Housing | Brookfield Properties | Eden Housing | Fairbank, Maslin, Maullin, Metz & Associates | Hanson Bridgett LLP | HOK | MidPen Housing | Nonprofit Housing Association of Northern California | PlaceWorks | Port of San Francisco | San Francisco Bay Area Rapid Transit District – BART | Santa Clara Valley Open Space Authority | Santa Clara Valley Water District | SCAPE Landscape Architecture | Second Nature Ecology + Design | Singer Associates Public Relations | Shute, Mihaly & Weinberger LLP | SOMO Village | Sonoma County Agricultural Preservation & Open Space District | Sonoma Land Trust | Team CivX | The Nature Conservancy | WRT
Greenbelt Ambassador SponsorEnterprise Community Partners | Mithun
The post Hidden Heroes 2026: Champions Empowering Communities for Action appeared first on Greenbelt Alliance.
Achieving Clean Water and Climate Goals through Healthy Soils Management in the Irrigated Lands Regulatory Program
Farms’ nitrogen management approaches have impacts on water quality, soil health, nitrous oxide emissions, and farms’ climate resilience and viability. Synthetic...
The post Achieving Clean Water and Climate Goals through Healthy Soils Management in the Irrigated Lands Regulatory Program appeared first on CalCAN - California Climate & Agriculture Network.
THE SHELL LEAKS FILES: 25 SEPTEMBER 2026
Archive reference: SLF-2007-068
Collection: The Sakhalin Papers
Principal audit cited in the record: 2005 Lenders Tier III HSE Audit for Phase One, RSK ENSR, December 2005
Authenticated corporate source: The Shell Sustainability Report 2005
Lender records: European Bank for Reconstruction and Development Phase I project record and 2005 Annual Report
Contemporaneous reporting: The Observer, June 2005; Financial Times, December 2005
Parliamentary records: German Bundestag Drucksache 16/1668; UK House of Commons Environmental Audit Committee evidence
Judicial record: Export Credits Guarantee Department v Friends of the Earth [2008] EWHC 638 (Admin)
Evidence standard: The underlying RSK ENSR audit has not been located in the publicly available record examined here. Statements about its findings are therefore attributed to the organisations and parliamentarians who cited it. Shell and lender statements are identified as such. No court ruled on the findings of the December 2005 audit.
Yesterday’s file reconstructed the grounding of the dredger Cristoforo Colombo at Kholmsk.
The accident provided a real-world test of emergency preparedness. Sakhalin Energy mobilised an emergency organisation quickly, but its own chronology showed responders arriving at Kholmsk hours later and severe weather initially preventing boom deployment. Early reports put the possible fuel loss at approximately 190–200 tonnes; Sakhalin Energy later reduced its final estimate to 28 tonnes.
That story did not end when the beach was cleaned.
There was another audience watching Sakhalin II.
The banks.Sakhalin II required financing on a scale that brought government-backed financial institutions directly into questions of environmental and safety performance.
And those institutions had leverage.
They could demand documents.
They could commission independent experts.
They could require corrective action.
Ultimately, they could refuse to lend.
1. The lenders were already inside Sakhalin IIThe European Bank for Reconstruction and Development — EBRD — had financed Phase I as early as 1997.
Its official project record shows an EBRD senior loan of US$116 million, accompanied by equal loans from the US Overseas Private Investment Corporation and the Export-Import Bank of Japan. The Phase I project cost was put at US$780 million. EBRD
The environmental conditions attached to that financing were extensive.
EBRD says Phase I was classified as a Category A project requiring an environmental impact assessment and public consultation. It required external expert opinions on oil-spill modelling, birds, fish, marine mammals and consultation. The lenders reviewed environmental procedures and agreed an Environmental Action Plan with Sakhalin Energy. EBRD
Crucially, that Environmental Action Plan included:
an independent environmental audit every two years for the duration of the lenders’ involvement. EBRD
The December 2005 lenders’ audit therefore did not emerge from nowhere.
Independent auditing had been built into the financing structure from the beginning.
2. The lenders had been promised an oil-spill systemThe same EBRD Phase I record is unusually specific about oil-spill preparedness.
It says Sakhalin Energy had produced an oil-spill contingency plan covering different spill volumes and sensitive coastline areas. According to EBRD, the plan identified Tier I, Tier II and Tier III equipment and resources available from the company, elsewhere on Sakhalin and internationally.
EBRD says its independent oil-spill experts reviewed the plan for adequacy before drilling and that it was subsequently subject to monitoring and reporting. EBRD
This creates an important documentary baseline.
By 2004, when Cristoforo Colombo grounded, spill preparedness was not merely an internal Sakhalin Energy aspiration.
It was part of a lender-supervised environmental framework.
3. Then came the December 2005 auditThe report appears in later records under the title:
2005 Lenders Tier III HSE Audit for Phase OneThe auditor is identified as:
RSK ENSRand the date as:
December 2005.A full public copy has not been located in the sources examined for this instalment.
That limitation is important.
Without the audit itself, we cannot responsibly reconstruct its complete methodology, reproduce its 90 audit points, determine precisely what constituted a “negative” result, or establish how individual findings were classified.
But two independent documentary trails cite the same audit.
One leads to environmental organisations.
The other leads to the German Bundestag.
4. The oil-spill equipment allegationOn 28 April 2006, WWF-UK, Friends of the Earth and The Corner House made a detailed submission to the UK Export Credits Guarantee Department concerning Sakhalin II.
Their submission explicitly cited the December 2005 RSK ENSR audit.
It stated that the Phase I audit had criticised:
poor management of oil-spill response equipment
and, more specifically, said that materials used during the response to the Cristoforo Colombo accident had not been replaced. The submission identifies its source in a footnote as the 2005 Lenders Tier III HSE Audit, RSK ENSR, December 2005. WWF Europe
That is an important claim.
But its evidential status must be stated precisely.
We have the environmental organisations’ description of the audit.
We do not presently have the audit page from which they derived it.
Accordingly, this archive does not convert their account into an independent finding of its own.
5. Why replacement of equipment matteredIf the WWF account of the audit is accurate, the issue was not principally what happened during the emergency.
It was what happened afterwards.
Oil-spill equipment is a preparedness system.
Booms, sorbents, protective equipment and other consumables may be damaged, contaminated or exhausted during a response. An emergency plan can therefore look complete on paper while its actual readiness has deteriorated if material used in a previous incident has not been replenished.
That is why the allegation deserves attention.
The September 2004 accident had supposedly tested the system.
The December 2005 audit, according to WWF’s account, found that part of what had been used had still not been replaced.
That would be a readiness issue, not merely an historical criticism of the Kholmsk response.
Again, however, the underlying audit should be obtained before making a stronger conclusion.
6. Then came the figure: two-thirds of 90A second reference appeared in the German parliament.
On 31 May 2006, members of the Bundestag from Bündnis 90/Die Grünen — the German Greens — tabled a formal motion concerning Sakhalin II and the credibility of the EBRD.
The motion cited the same report:
“RSK ENSR Lenders Tier III HSE Audit for Phase One.”
It said that an audit of Phase I had examined 90 points and that, in two-thirds of them, the results concerning compliance with environmental standards were negative. Rewis
That is a striking figure.
But again the provenance is crucial.
This was a statement contained in a parliamentary motion submitted by opposition politicians.
It was not a finding adopted by the Bundestag as a whole.
7. The German motion was rejectedThe parliamentary history supplies an important safeguard against overstating the evidence.
A Bundestag committee subsequently recommended rejection of the Greens’ motion. The recommendation identified the Sakhalin II proposal and called for its rejection with the votes of the governing CDU/CSU and SPD parliamentary groups. Rewis
That does not mean the committee disproved the audit figure.
Nor does it mean the Bundestag verified it.
A parliamentary vote on a political motion is not an evidentiary trial of every supporting statement contained within that motion.
The correct documentary formulation is therefore narrow:
German Green parliamentarians cited the December 2005 lenders’ audit as showing negative environmental-compliance results in two-thirds of 90 points examined. Their motion was subsequently rejected.
Anything stronger would go beyond the record presently available.
8. Shell’s own report confirms a separate compliance failureThere is, however, one important part of the story that does not depend upon environmental campaigners or opposition politicians.
It comes from Shell itself.
The Shell Sustainability Report 2005 describes the extraordinary scale of the onshore pipeline system. Sakhalin Energy’s pipelines would cross more than 1,000 rivers and streams, around 180 of them considered potentially environmentally sensitive. Shell
A river-crossing strategy had been developed with outside experts. Contractors were instructed to use particular low-impact methods at high-risk crossings.
Then Shell states plainly:
“Contractors did not always comply with the strategy”
during the winter of 2004–05. Shell
Sakhalin Energy stopped the winter work programme when it learned what was happening. Shell
That is an authenticated Shell admission.
9. What Sakhalin Energy did nextShell’s report says the river-crossing strategy was revised and monitoring strengthened for winter 2005–06.
Individual action plans were drawn up for the remaining sensitive crossings.
Contractors were retrained.
Contracts were rewritten to include incentives and penalties connected to compliance.
And independent, technically qualified external observers were invited to watch the remaining sensitive river crossings. Their reports and photographs were then published. Shell
This is important evidence on both sides of the ledger.
It establishes a failure of contractor compliance.
It also establishes corrective action.
A documentary history should record both.
10. The lenders had already become alarmedThe pressure was visible months before the December audit.
On 19 June 2005, The Observer reported that EBRD was refusing to move forward with financing while environmental problems surrounding pipeline construction remained unresolved.
The newspaper quoted an EBRD spokesman saying the project was, at that stage, not in “material compliance” with the bank’s policy and the company’s commitments. EBRD nevertheless said the problems could be resolved. The Guardian
That contemporaneous report matters because it shows the December audit did not arrive during a period of unqualified lender confidence.
Environmental compliance had already become a financing issue.
11. December produced an apparently contradictory developmentNow compare June with December.
Shell’s own Sustainability Report records that in late 2005 EBRD decided Sakhalin Energy’s approach to environmental, social and health-and-safety impacts was:
“fit for the purpose of public consultation.” ShellContemporaneous Financial Times reporting explained what that meant.
EBRD had previously considered the documentation inadequate to continue through its approval process. After further work with Shell and its Japanese partners, it decided that the material was sufficiently developed to enter a 120-day public consultation. Shell News
EBRD president Jean Lemierre stressed that the bank had not decided to finance Sakhalin II. Shell News
That distinction is fundamental.
“Fit for consultation” did not mean:
environmentally approved.
It did not mean:
audit passed.
And it certainly did not mean:
loan granted.
12. EBRD’s own record confirms the distinctionThe EBRD Annual Report for 2005 records that Sakhalin Energy was then owned 55 per cent by Shell, 25 per cent by Mitsui and 20 per cent by Mitsubishi, and that EBRD had already financed Phase I in 1997. EBRD
The bank says it spent 2005 consulting affected communities, NGOs and Sakhalin Energy about environmental and social concerns.
Only on 20 December 2005 did EBRD begin the formal 120-day consultation period concerning potential Phase II finance.
Its annual report explicitly says a final decision on whether to lend would come after that consultation and after the bank had assessed the findings. EBRD
So the lender position at the end of 2005 was neither rejection nor approval.
It was continued due diligence.
13. Why Shell wanted the EBRDThe amount contemplated from EBRD was small compared with the enormous overall cost of Sakhalin II.
The Financial Times reported that Lemierre put the prospective EBRD participation at around €200–300 million. But the significance of the bank went beyond the amount of money involved.
A refusal by an international development bank on environmental grounds could affect the confidence of other lenders. Shell News
The wider financing plan was enormous.
Evidence later supplied to the House of Commons Environmental Audit Committee recorded contemplated loans of approximately US$3.7 billion from Japanese export-credit agencies, US$250 million from the US side, around US$1.5 billion of commercial lending and a potential US$600 million EBRD facility, alongside shareholder equity. UK Parliament
Britain’s Export Credits Guarantee Department was separately considering approximately US$650 million of support linked to UK-supplied goods and services. UK Parliament
Environmental performance was therefore not peripheral to the financing.
It sat inside it.
14. British officials also found the project below some standardsThe later UK parliamentary record is particularly useful because it is not written by Shell or an environmental campaign group.
Evidence concerning ECGD’s handling of Sakhalin II states that British officials and other financial institutions concluded that the project did not fully meet some relevant World Bank Group guidelines.
They nevertheless believed Sakhalin Energy could take corrective action.
ECGD made a conditional support offer in March 2004 subject to requirements being met. UK Parliament
The same record says pressure from the lending institutions resulted in Sakhalin Energy publishing a much more extensive set of commitments in late 2005, including an HSE and Social Action Plan containing more than 2,000 specific commitments. UK Parliament
That puts the December audit into a much larger system of lender supervision.
The financial institutions were not simply asking whether Sakhalin II had environmental policies.
They were asking whether commitments were actually being implemented.
15. And that would become the harder questionThe House of Commons evidence contains a revealing later assessment.
It says that because construction had already begun in 2003, ECGD and other institutions had to do two jobs simultaneously:
assess whether the project’s plans met international standards;
and monitor whether Sakhalin Energy was actually observing the commitments it had made.
The parliamentary evidence then says that by 2006–07 it was becoming clear that some commitments were not being observed, leading to a Remedial Action Plan in August 2007 concerning the onshore pipelines. UK Parliament
That later development does not prove every claim attributed to the December 2005 audit.
But it demonstrates why the distinction between policy and implementation mattered.
16. The audit trail eventually reached the High CourtThe finance controversy later generated an English court record.
In Export Credits Guarantee Department v Friends of the Earth [2008] EWHC 638 (Admin), Mr Justice Mitting recorded that approximately US$650 million of UK-backed project finance had been sought for Sakhalin II and described the potentially serious environmental consequences, including effects on the western gray whale. vLex
The dispute concerned access to environmental information held by government.
It did not decide whether the December 2005 RSK ENSR audit was correct.
It did not determine whether two-thirds of 90 audit points had failed.
It did not rule that Shell had breached environmental law.
And it did not determine whether Cristoforo Colombo response equipment had been replaced.
Its relevance is institutional.
The environmental scrutiny surrounding Sakhalin II financing had become important enough that disputes about what the British government knew eventually reached the High Court.
17. There is a documentary paradoxBy the end of 2005, several propositions coexisted.
Shell acknowledged contractor non-compliance at sensitive river crossings and said it had stopped work and imposed stronger controls. Shell
Earlier that year, EBRD had publicly indicated that the project was not yet in material compliance with its policies and Sakhalin Energy’s commitments. The Guardian
Environmental organisations later cited a December lenders’ audit as finding poor management of spill-response equipment. WWF Europe
German Green MPs cited the same audit as producing negative environmental-compliance results in two-thirds of 90 matters examined. Rewis
Yet in December EBRD also concluded that the documentation had reached the point where formal public consultation could begin. EBRD
There is no necessary contradiction.
A project can have deficiencies and still possess enough documentation to begin consultation about whether those deficiencies can be corrected.
The mistake would be to translate “fit for consultation” into “environmentally cleared.”
The contemporaneous record does not support that translation.
Documentary FindingsEstablished. EBRD financed Sakhalin II Phase I in 1997 through a US$116 million loan, alongside equal OPIC and Japanese government-backed loans. The lender Environmental Action Plan provided for recurring independent environmental auditing. EBRD
Established. EBRD’s Phase I record says Sakhalin Energy’s oil-spill contingency arrangements and response equipment were subject to lender review and continuing monitoring. EBRD
Established. A document identified as the 2005 Lenders Tier III HSE Audit for Phase One, prepared by RSK ENSR in December 2005, is cited by both a 2006 environmental-group submission and a formal German parliamentary motion. WWF Europe
Attributed, not independently verified from the audit itself. WWF, Friends of the Earth and The Corner House said the audit criticised poor management of oil-spill response equipment and reported that material used during the Cristoforo Colombo response had not been replaced. WWF Europe
Attributed, not independently verified from the audit itself. German Green MPs stated that the audit produced negative environmental-compliance results in two-thirds of 90 matters examined. Their motion was subsequently recommended for rejection and did not become an adopted Bundestag finding. Rewis
Established from Shell’s own report. Pipeline contractors did not always comply with Sakhalin Energy’s river-crossing strategy during winter 2004–05. Sakhalin Energy halted the winter programme, revised procedures, retrained contractors, introduced contractual incentives and penalties, strengthened monitoring and invited independent external observers. Shell
Established. EBRD began a formal 120-day consultation on potential Phase II financing on 20 December 2005. No financing decision had then been made. EBRD
Established. British export-credit officials later recorded that Sakhalin II did not initially meet some relevant World Bank Group guidelines and that financial institutions pressed Sakhalin Energy to produce improved plans and commitments. UK Parliament
What is not establishedThe complete December 2005 RSK ENSR audit has not been located in the publicly accessible sources reviewed for this file.
We therefore cannot presently establish the precise wording of all its findings, identify each of the 90 matters said to have been examined, determine how “negative” results were defined, or independently verify the calculation cited in the German parliamentary motion.
It is not established that Shell itself failed two-thirds of 90 legal requirements.
It is not established that every negative audit observation amounted to a breach of law, a breach of a loan covenant or a serious environmental incident.
It is not established from the audit material presently available exactly what Cristoforo Colombo response equipment was allegedly not replenished, in what quantity, for how long, or whether it was subsequently replaced.
The German parliamentary motion was not an adjudication and was not adopted.
The environmental organisations’ submission was advocacy material and is treated as such.
Conversely, EBRD’s decision that the documentation was fit for public consultation was not approval of the loan and should not be represented as an environmental clean bill of health. EBRD
CommentaryThe significance of the December 2005 audit is not that it supplies a convenient numerical accusation against Shell.
Until the report itself is obtained, the number must remain exactly where the evidence places it:
inside attributed secondary accounts of the audit.
The more compelling story is structural.
Sakhalin II had reached a stage where the project’s own systems were being measured against promises made to international lenders.
Those lenders had environmental covenants.
They had outside specialists.
They had audit rights.
They had reporting requirements.
And, unlike campaigners standing outside the project, they had something Shell and its partners wanted very badly:
money. The difference between having a standard and enforcing itShell’s river-crossing admission may be the clearest illustration.
The project had a strategy.
External experts had helped prepare it.
High-risk rivers had special procedures.
Contractors had instructions.
Yet Shell acknowledges that contractors did not always comply.
The response was to stop work, rewrite arrangements, retrain contractors, impose incentives and penalties and bring in independent observers. Shell
That sequence tells us something fundamental about large industrial projects.
A policy on paper is the beginning of a control system.
It is not proof that the control system works.
The same question hangs over the alleged spill-response finding.
Having lists of Tier I, II and III equipment satisfied one part of preparedness.
Knowing whether equipment remained available, serviceable and replenished after an actual emergency was another matter altogether.
The lenders’ dilemmaThere was an additional difficulty.
By the time the institutions were deciding whether to finance Phase II, much of Sakhalin II was already being built.
The UK parliamentary record later acknowledged precisely this problem: financiers were assessing an enormous development against international standards while construction was already under way. UK Parliament
That weakened the simplicity of the lender sanction.
If a bank refused money before construction began, a project could stop.
If billions had already been committed and infrastructure was already in the ground, environmental due diligence became partly an exercise in correcting a moving project.
That distinction would become increasingly important.
And it raises the question at the centre of the next file.
Source RecordThe authenticated EBRD Phase I project record confirms the US$116 million EBRD loan, the equal OPIC and Japanese co-financing, the Environmental Action Plan, lender review of oil-spill arrangements and the requirement for recurring independent environmental audits. EBRD
EBRD — Sakhalin II Phase I project record
The Shell Sustainability Report 2005 is the principal authenticated Shell source. It acknowledges that contractors did not always comply with the river-crossing strategy, describes Sakhalin Energy’s corrective action and records EBRD’s late-2005 decision that the project’s environmental, social and health-and-safety documentation was fit for public consultation. Shell
Shell — The Shell Sustainability Report 2005
The WWF/Friends of the Earth/The Corner House submission to ECGD of 28 April 2006 explicitly cites the 2005 Lenders Tier III HSE Audit, RSK ENSR, December 2005 and attributes to it the criticism concerning oil-spill equipment used during the Cristoforo Colombo response. WWF Europe
WWF/Friends of the Earth/The Corner House — Sakhalin II submission to ECGD
German Bundestag Drucksache 16/1668, dated 31 May 2006, records the Greens’ statement that two-thirds of 90 points examined in the Phase I audit produced negative results regarding environmental-standard compliance and names the RSK ENSR lenders’ audit as its source. Rewis
German Bundestag — Drucksache 16/1668 on Sakhalin II
The subsequent committee recommendation, Drucksache 16/2925, recommended rejection of that motion, an important qualification when describing its parliamentary status. Rewis
German Bundestag — Committee recommendation on Drucksache 16/1668
EBRD’s authenticated 2005 Annual Report records the consultations throughout 2005 and the opening on 20 December 2005 of the formal 120-day consultation period, while making clear that a financing decision would come later. EBRD
The Observer reported on 19 June 2005 that EBRD was withholding progression of financing while pipeline environmental problems remained unresolved and quoted the bank as saying the project was not then in material compliance with policy and company commitments. The Guardian
The Observer — EBRD freezes Shell Sakhalin loan, 19 June 2005
The Financial Times reported on 15 December 2005 that EBRD considered the documentation ready for public consultation but that bank president Jean Lemierre stressed no financing decision had been taken. Shell News
Financial Times report preserved by ShellNews.net — 15 December 2005
Evidence published by the House of Commons Environmental Audit Committee records the proposed financing structure, ECGD’s US$650 million contemplated support, shortcomings identified against World Bank Group guidelines and the later lender monitoring programme. UK Parliament
The judicial context is Export Credits Guarantee Department v Friends of the Earth [2008] EWHC 638 (Admin). Mr Justice Mitting recorded the proposed US$650 million UK-backed financing and the project’s environmental sensitivity. The case concerned disclosure of environmental information, not adjudication of the RSK ENSR audit findings. vLex
High Court — ECGD v Friends of the Earth [2008] EWHC 638 (Admin)
Archive disclaimer: The underlying December 2005 RSK ENSR lenders’ audit has not been located in the publicly available sources examined for this instalment. Statements about its contents are therefore attributed to the documents that cite it rather than presented as independently verified audit findings. Shell’s own statements are identified separately, as are lender, parliamentary, campaign-group and judicial records. The existence of an adverse audit observation does not by itself establish a breach of law or corporate liability.
Site-wide disclaimer applies.
Next instalment The Sakhalin Papers LIX: The 120-Day Test — When the Banks Put Shell’s $20 Billion Project Out for JudgmentOn 20 December 2005, EBRD opened its formal 120-day consultation.
Shell called the development a major milestone.
Environmental groups regarded it very differently.
The lenders now had more than 2,000 environmental, health, safety and social commitments against which Sakhalin Energy could be measured. British officials later acknowledged the difficulty: construction was already progressing, so the financial institutions were trying to judge not merely what Shell promised to do, but what was actually happening on the ground. UK Parliament
Public meetings followed on Sakhalin, Hokkaido, in Moscow and in London. EBRD
But the financing story was about to collide with something much larger than environmental due diligence.
Russia was becoming increasingly hostile to the terms under which Shell controlled Sakhalin II.
Costs had doubled.
Regulators were applying pressure.
And Gazprom was waiting.
The next file will examine what happened during the 120-day consultation, what the lenders demanded, what Shell promised — and how an environmental financing process became entangled with the political struggle that would ultimately cost Shell control of Sakhalin II.
THE SHELL LEAKS FILES: 25 SEPTEMBER 2026 was first posted on September 25, 2026 at 8:25 pm.©2018 "Royal Dutch Shell Plc .com". Use of this feed is for personal non-commercial use only. If you are not reading this article in your feed reader, then the site is guilty of copyright infringement. Please contact me at john@shellnews.net
Taxpayer-Funded Trump Ad Violates the Hatch Act
A television ad boosting the image of President Donald Trump, which was paid for by government funds, violates laws prohibiting the use of government resources for propaganda, the Hatch Act, and other related laws, according to a complaint filed today by Public Citizen.
The complaint, sent to the U.S. Government Accountability Office (GAO) and the U.S. Office of Special Counsel, takes issue with ads airing in two media markets that include a disclaimer: “Paid for by the U.S. government.” Both markets airing the ad contain key districts in the upcoming midterm elections.
“For anyone with a modicum of ethics, common sense or respect for the law, it’s the most basic thing: Taxpayer funds cannot pay for partisan political propaganda,” said Lisa Gilbert, co-president of Public Citizen. “These ads should immediately be pulled from the air, and the White House’s many apparent violations of the law should be investigated.”
“This administration’s repeated and flagrant violations of the law, including the Hatch Act, are an affront to taxpayers and our democracy,” said Craig Holman, Ph.D., a government ethics expert with Public Citizen. “Public Citizen has filed a dozen Hatch Act complaints with OSC over the past year and, to our knowledge, all have been ignored by the agency. That negligence is dangerous, and creates conditions that allow for the situation we are responding to today.”
The full complaint is available to read here.
Following SCOTUS Ruling, Common Cause Vows Immediate Legal Action Against Any Attempts to Disenfranchise Voters Using Flawed System
Common Cause condemned the Supreme Court’s ruling today allowing the federal government to continue using the flawed SAVE system.
Statement from Common Cause President & CEO Virginia Kase Solomón:
“The Supreme Court’s decision to allow DHS and states to use an error-ridden system is completely unacceptable and didn’t need to happen this close to the election. This DHS system, which the federal government itself admits is flawed, has always been part of the Trump administration’s campaign to interfere in our elections and sow distrust — and it will fail.
“As the Court noted in its decision, it is flatly illegal for states to conduct mass removals of voters from the rolls within 90 days of an election. If any state official attempts to disenfranchise eligible voters using this flawed database, we will take them to court immediately, just like Common Cause is already doing in Texas.
“Our elections remain safe and secure, and nothing will stop voters from making their voices heard.”
Last year, Texas officials removed multiple eligible voters from the voter rolls based on this same flawed DHS system, without any investigation or further checks into even the state’s own records that could confirm these voters’ citizenship. Common Cause filed a lawsuit to stop this illegal voter purge, and we are ready to do so again.
Common Cause will continue leading the charge to safeguard the right to vote for every American. We urge all voters to check their registration status today and reach out to 866-OUR-VOTE by call or text for accurate, nonpartisan assistance.
Common Cause’s nonpartisan Election Protection volunteers will also be on the ground and staffing hotlines nationwide throughout early voting and on Election Day.
Publicaciones
Publications
assembly:2026:indonesia:cover_bangungreport_small.jpg - created
SCOTUS Greenlights the Misuse of Social Security Data
The following is a statement from Nancy Altman, President of Social Security Works, in response to today’s Supreme Court decision greenlighting the use of Social Security data for determining voter eligibility:
“In the name of non-existent voter fraud, the Supreme Court has given the Trump administration the power to misuse Social Security data to deprive American citizens of their right to vote. This is an obvious effort to undermine free and fair elections.
The personal data that Americans provide to the Social Security Administration is intended for one purpose only: To get people the benefits they’ve earned. Only those who are lawfully present in this country are eligible for benefits.
Because Social Security data was never intended for verifying voter eligibility, SSA has no reason to keep people’s immigration status up to date in cases where it isn’t relevant for their benefits. Indeed, it would be a misuse of trust fund monies for SSA to spend resources updating that information.
That means that some of the data is inaccurate or outdated. As a result, U.S. citizens could wrongfully lose their right to vote.
Today’s Supreme Court decision is a violation of the trust that the American people place in Social Security.”
Tejiendo esperanza en tiempos de crisis: Informe de la 2.ª Asamblea presencial del Tejido Global de Alternativas
es:assembly:2026:indonesia:cover_bandung_esp.jpg - created
Pages
The Fine Print I:
Disclaimer: The views expressed on this site are not the official position of the IWW (or even the IWW’s EUC) unless otherwise indicated and do not necessarily represent the views of anyone but the author’s, nor should it be assumed that any of these authors automatically support the IWW or endorse any of its positions.
Further: the inclusion of a link on our site (other than the link to the main IWW site) does not imply endorsement by or an alliance with the IWW. These sites have been chosen by our members due to their perceived relevance to the IWW EUC and are included here for informational purposes only. If you have any suggestions or comments on any of the links included (or not included) above, please contact us.
The Fine Print II:
Fair Use Notice: The material on this site is provided for educational and informational purposes. It may contain copyrighted material the use of which has not always been specifically authorized by the copyright owner. It is being made available in an effort to advance the understanding of scientific, environmental, economic, social justice and human rights issues etc.
It is believed that this constitutes a 'fair use' of any such copyrighted material as provided for in section 107 of the US Copyright Law. In accordance with Title 17 U.S.C. Section 107, the material on this site is distributed without profit to those who have an interest in using the included information for research and educational purposes. If you wish to use copyrighted material from this site for purposes of your own that go beyond 'fair use', you must obtain permission from the copyright owner. The information on this site does not constitute legal or technical advice.
 This site is not the official webpage of the Industrial Workers of the World.